TL;DR summary:
- Flood insurance cost in Texas is set home by home. Under FEMA’s Risk Rating 2.0, your National Flood Insurance Program (NFIP) premium depends on your building’s features and flood risk, not just the flood zone on a map.
- FEMA’s numbers show a wide range. As of August 31, 2023, 37% of U.S. single-family NFIP policies had a full-risk cost of $0 to $1,000 a year, and another 32% fell between $1,000 and $2,000.
- In Texas, FEMA projected that 97% of existing policyholders’ premiums would either decrease or increase by $20 a month or less under Risk Rating 2.0.
- Every NFIP bill also carries set fees, including a $25 HFIAA surcharge for a primary residence and a $47 Federal Policy Fee for most policies.
- You can lower the price in some cases with an elevation certificate, flood openings, raised equipment, a higher deductible or a Community Rating System (CRS) discount. Lubbock takes part in CRS.
Flood insurance cost in Texas used to come down mostly to one question: what flood zone is the house in? Since FEMA moved to Risk Rating 2.0, the answer is more personal. Two houses on the same street can pay very different amounts. This guide explains what drives an NFIP premium, what FEMA’s own numbers show, which fees appear on every bill, and what you can do to lower the price. It also covers the flood picture in Lubbock and how to get a quote you can trust. It draws on FEMA, FloodSmart, Texas Department of Insurance (TDI) and City of Lubbock guidance.
Table of Contents
- Key Takeaways
- How FEMA Prices Flood Insurance in Texas
- What FEMA’s Numbers Show About Cost
- Fees and Caps on Every NFIP Bill
- Ways to Lower Your NFIP Premium
- Flood Risk and Discounts in Lubbock
- NFIP vs Private Flood Insurance
- How to Get an Accurate Flood Quote
- Our Take: Price the House, Not the Map
- How Hettler Insurance Agency Helps Texas Homeowners With Flood Insurance
- Sources
- Frequently Asked Questions
Key Takeaways
Flood insurance pricing is more specific to your home than it used to be. These are the points that matter most.
| Point | Details |
|---|---|
| Your home sets the price | Risk Rating 2.0 looks at foundation type, first-floor height, distance to water, rebuilding cost and other features of your building. |
| Most home policies exclude flood | TDI says most home insurance policies don’t cover flood damage. Flood coverage is a separate policy. |
| Low-risk zones still flood | TDI says 40% of NFIP claims come from outside high-risk flood areas. |
| Increases are capped for most renewals | FEMA says that by law, rates can’t go up more than 18% a year for most policyholders. The cap usually doesn’t apply to new policies. |
| Discounts are real but specific | Flood openings, raised machinery and equipment, elevation data and CRS discounts can lower an NFIP premium when your home qualifies. |
| Buy early | A new NFIP policy usually has a 30-day waiting period before coverage starts. |
How FEMA Prices Flood Insurance in Texas
Most Texas flood policies are written through the NFIP, which FEMA runs. Under Risk Rating 2.0, FEMA prices each building on its own flood risk instead of leaning mainly on its flood zone. FloodSmart sorts the rating factors into three groups: where the home is built, how it is built, and what is covered.
- Where it is built: distance to flooding sources such as rivers, lakes and the coast, the ground elevation compared with the land around it, and the community the home is in, including any CRS discount.
- How it is built: foundation type, first-floor height, number of floors, construction type, flood openings and whether machinery and equipment sit above the first floor.
- What is covered: the home’s replacement cost, the building and contents limits you choose, and your deductibles.
FEMA also lists levee performance and the cost to rebuild among the factors for single-family homes. That is why a quote for one house says little about the house next door.
For a broader look at what an NFIP policy covers, see our guide to Texas flood insurance for homeowners.
What FEMA’s Numbers Show About Cost
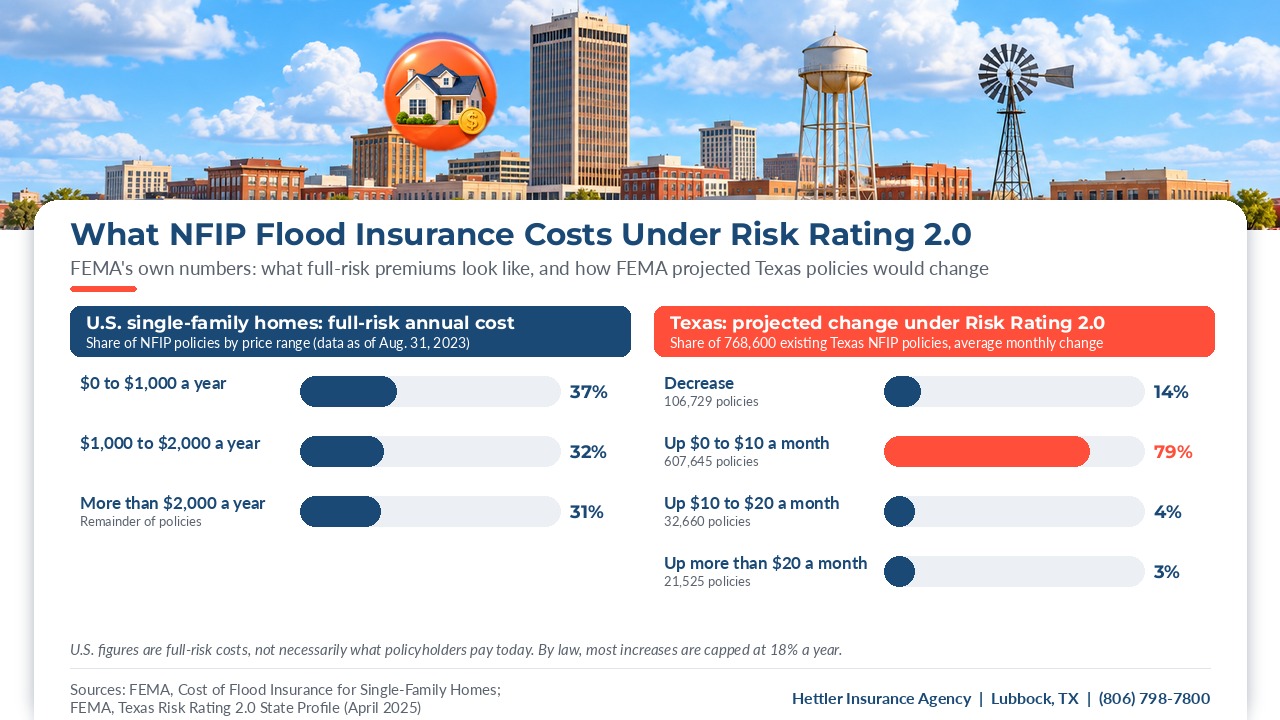
FEMA publishes cost ranges instead of a single average, because a single number would hide how much premiums vary.
Two points stand out:
- Nationally, FEMA says 37% of single-family NFIP policies had a full-risk cost of $0 to $1,000 a year and 32% had a full-risk cost of $1,000 to $2,000, based on policies in force on August 31, 2023. Full-risk cost is what the policy would cost without the caps and statutory discounts that still apply to many renewals.
- In Texas, FEMA’s state profile projected how 768,600 existing policies would change under Risk Rating 2.0: about 14% would see an immediate decrease, 79% an average increase of $0 to $10 a month, 4% an increase of $10 to $20 a month, and 3% an increase of more than $20 a month.
Neither figure is a quote for your house. They show the spread, and they show why it pays to price your own home instead of relying on a neighbor’s number.
Fees and Caps on Every NFIP Bill
Your declarations page breaks the total into premium, discounts, fees and surcharges. These line items come from FloodSmart.
| Line item | What it is |
|---|---|
| Annual increase cap | Limits yearly increases to 18% to 25% for most policyholders. It usually doesn’t apply to new policies. |
| Reserve Fund Assessment | 18% of the discounted premium, used to support the NFIP Reserve Fund. |
| HFIAA surcharge | $25 for a primary residence and $250 for all other occupancies, such as a second home or rental. |
| Federal Policy Fee | $47 for most policies. |
| Increased Cost of Compliance (ICC) premium | 1.9% of the building and contents premium, up to $75. It pays toward bringing a badly damaged home up to local floodplain rules. |
| Probation surcharge | $50 per policy, charged only if FEMA places the community on probation. |
The fee on a second home or rental is ten times the primary-residence surcharge, so tell your agent how you use the property.
Ways to Lower Your NFIP Premium
Some of the factors behind your price are fixed. Others you can change or document.
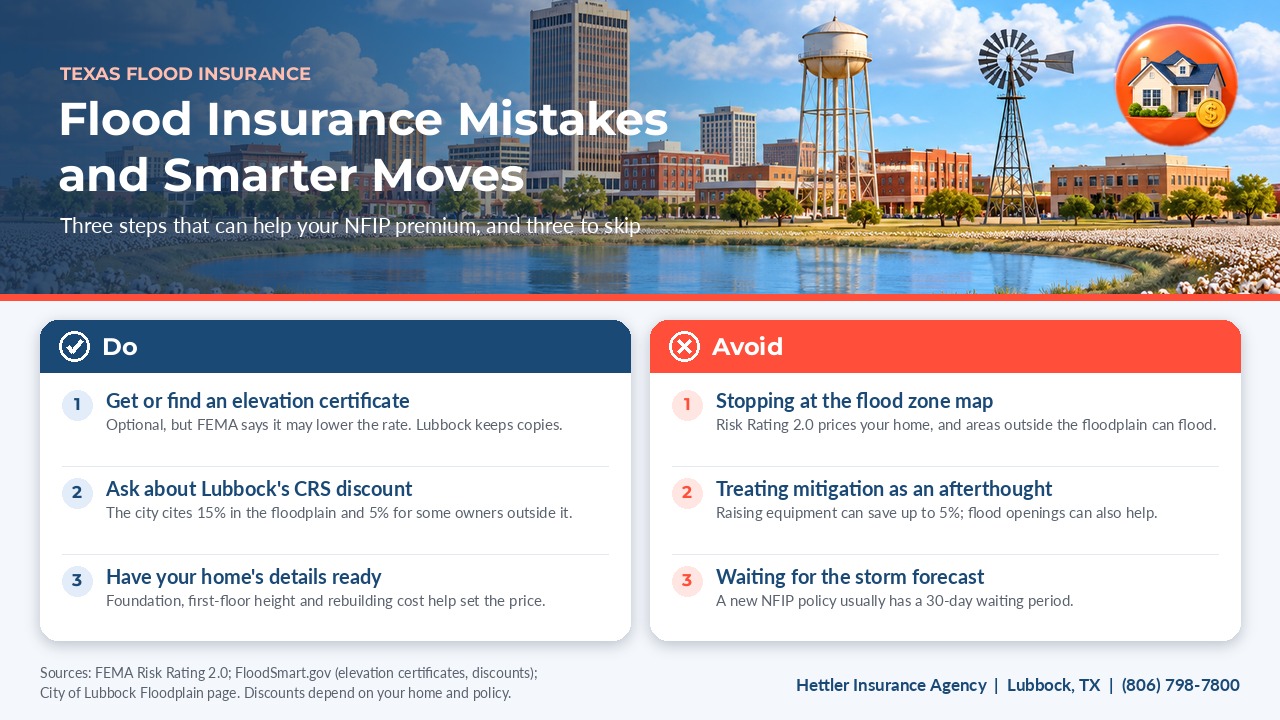
- Get or find an elevation certificate. FloodSmart says most homeowners don’t need one, though it may be required in some high-risk zones (Zones A and V). Elevation certificates don’t set your rate, but they can help identify discounts. FEMA’s Risk Rating 2.0 fact sheet says an elevation certificate is optional but may lower the rate.
- Raise machinery and equipment. FloodSmart’s guidance for agents says properly elevating covered machinery and equipment, such as a water heater, above the first floor can save up to 5% on a premium.
- Add proper flood openings. FloodSmart lists flood openings as a mitigation discount for elevated homes with an enclosure or crawlspace. Its example shows savings of around 5% for a 5-foot crawlspace.
- Elevate the home. This is a major project, but FloodSmart’s example shows that raising a building from 0 to 5 feet above the ground can save 34% on the premium.
- Review your deductible. A higher deductible can lower the premium, but you pay more after a flood. Our Texas deductible guide walks through that trade-off.
- Ask about mitigation help. FEMA’s Texas profile says NFIP policyholders in high-risk areas can use Increased Cost of Compliance coverage after a flood to access up to $30,000 toward elevating, relocating or demolishing a substantially damaged home, meaning repairs cost 50% or more of its pre-flood market value. FEMA Hazard Mitigation Assistance grants flow through the state, and the City of Lubbock points property owners to state-run mitigation grants through the Texas Water Development Board.
For a quick recap, here are three smarter moves and three mistakes to skip:
Flood Risk and Discounts in Lubbock
Lubbock isn’t on the coast, but the City of Lubbock says its flood zones generally sit next to the playa lakes and the Canyon. The city says Lubbock is prone to flash flooding from short but intense rain, as well as street and low-lying urban flooding, and that even areas outside the mapped floodplain may flood. In September 2008, the city recorded 7.8 inches of rain in 24 hours.
A few local points can affect your price:
- CRS discount. The City of Lubbock says it participates in the CRS. The city says this lets property owners in the floodplain get a 15% discount, and some owners outside the floodplain may get 5%. Under FEMA’s current pricing, CRS discounts apply to eligible NFIP policies anywhere in a participating community, so check which discount appears on your declarations page.
- Elevation certificates on file. The city keeps elevation certificates for structures built in the floodplain and provides copies on request at (806) 775-2347.
- Mortgage-length odds. The city says a home in the floodplain has a 26% chance of flooding over the life of a 30-year mortgage.
To check your property, start with the FEMA Flood Map Service Center. Then read whether your Lubbock home or business is in a floodplain.
NFIP vs Private Flood Insurance
TDI says you can get a flood policy from your insurance company or the NFIP. Here’s how the two compare.
| Feature | NFIP policy | Private flood policy |
|---|---|---|
| Coverage limits | Up to $250,000 for the building and $100,000 for contents | Set by each insurance company and policy form |
| Pricing | FEMA’s Risk Rating 2.0, with federal fees, caps and discounts | Set by the insurance company’s own rating |
| Waiting period | Usually 30 days, with some exceptions | Varies by company |
| CRS discount | Applies to eligible policies in participating communities | CRS is an NFIP discount. Ask the company whether it offers its own discounts. |
If rebuilding your home would cost more than the NFIP building limit, ask your agent to price both options. Read the policy form line by line before you switch.
How to Get an Accurate Flood Quote
A good flood quote starts with good information about the house.
- Look up your address on the FEMA Flood Map Service Center.
- Find any elevation certificate, survey or construction details you have. In Lubbock, ask the city whether one is on file.
- Note the foundation type, how high the first floor sits, and where the furnace, water heater and other equipment are.
- Decide on building and contents limits and a deductible you could pay.
- Buy early. The NFIP Flood Insurance Manual sets a 30-day waiting period for most new policies. Exceptions include coverage bought in connection with making, increasing, extending or renewing a loan, and some purchases tied to a flood map revision.
If you’re also shopping for home coverage, our guide to home insurance cost in Texas explains the other half of the bill.
Our Take: Price the House, Not the Map
The old shortcut of “high-risk zone means you need it, low-risk zone means you don’t” no longer tells you much about cost. FEMA now prices the building, and TDI’s figures show that a large share of claims come from outside high-risk areas.
Get a real NFIP quote for your own home, then compare it against a private option with someone who can explain the differences. That conversation takes less time than most people expect.
“The best independent insurance agents don’t just find you a policy. They find you the right insurance policy and then make sure it stays right as your life changes.” — Ron Hettler, CIC (Certified Insurance Counselor), Hettler Insurance Agency
How Hettler Insurance Agency Helps Texas Homeowners With Flood Insurance
Hettler Insurance Agency has served Lubbock and clients across Texas since 1992 and is licensed statewide. Ron Hettler, CIC (Certified Insurance Counselor), agency founder and president with 45+ years of insurance industry experience, and Meghan Harris, CIC, who co-leads the agency with Ron, help Texas homeowners understand what drives their flood premium and whether NFIP or private flood coverage fits their home. The agency carries a 4.5-star Google rating, an A+ BBB rating, and recognition from Three Best Rated® and Expertise.com.
Hettler Insurance Agency is one of the few family-owned agencies in Texas where both principals carry the high level certification of CIC (Certified Insurance Counselor). Fewer than 2% of licensed insurance professionals in the U.S. have earned the CIC designation.

As an independent agency working with 30+ top-rated carriers, Hettler Insurance Agency can compare NFIP and private flood options side by side, instead of fitting you into one company’s terms. Learn more about our flood insurance coverage and why an independent agent matters. We do not charge extra fees for ID cards or certificates of insurance. Ron calls it a fundamental customer service.
For a flood quote, have your address, any elevation certificate and your current declarations page ready. Then call (806) 798-7800, visit 4720 S Loop 289, Lubbock, TX 79414, or start your quote at Hettler Insurance Agency. Get Better. Get Hettler.
This article provides general information and is not a substitute for advice from a licensed insurance professional. Flood insurance premiums, fees, discounts, coverage limits and waiting periods depend on your property, the policy and current FEMA or insurer rules. Review your own policy and consult a licensed insurance professional before you buy or change flood coverage.
Sources
- FEMA: Cost of Flood Insurance for Single-Family Homes Under the NFIP’s Pricing Approach
- FEMA: Risk Rating 2.0 Texas State Profile (April 2025)
- FEMA: Risk Rating 2.0 Fact Sheet (April 2025)
- FloodSmart: Premium Costs
- FloodSmart: Elevation Certificates
- FloodSmart for Agents: Risk Rating 2.0, What Goes Into a Rate
- FEMA: Community Rating System
- FEMA: NFIP Flood Insurance Manual (April 2024)
- Texas Department of Insurance: Flood Insurance
- City of Lubbock: Floodplain
- FEMA Flood Map Service Center
Frequently Asked Questions ?
Q1 ?: How much does flood insurance cost in Texas?
Q2 ?: What is Risk Rating 2.0 and how did it change Texas flood premiums?
Q3 ?: Do I need an elevation certificate to buy flood insurance?
Q4 ?: Can Lubbock homeowners get a flood insurance discount?
Q5 ?: How long does it take for a new flood insurance policy to start?
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [a gold-standard credential in the independent insurance industry that less than 2% earn]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots 100+ years going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com