TL;DR summary:
- The best coverage for a Texas homeowner isn’t the lowest home insurance premium. It’s the insurance policy that fits once you compare quotes side by side. Set your dwelling limit to rebuild cost, not market value. Turn any percentage wind/hail deductible into a dollar amount, and check whether your roof settles at replacement cost or actual cash value. Buy flood coverage separately before you need it, because NFIP policies typically carry a 30-day waiting period. Document your home before storm season, and never sign a release or endorse a settlement check too quickly. An independent agency like Hettler Insurance Agency can shop 30+ top-rated carriers for you at no extra fee.
The fastest way to find the best coverage for Texas homeowners insurance is to get apples-to-apples quotes that match your home’s actual rebuild cost, then compare deductible structure (flat vs. percentage for wind/hail), flood source (NFIP vs. private), and carrier quality — not just premium. Texas homeowners face hail and flood risks that standard policies often handle poorly, which is exactly why working with a local independent agent like Hettler Insurance Agency, and checking carrier ratings through AM Best or the NAIC complaint database, matters before you sign anything. “The best independent insurance agents don’t just find you a policy. They find you the right insurance policy and then make sure it stays right as your life changes.” — Ron Hettler, CIC (certified insurance counselor), Hettler Insurance Agency
Start here — your immediate next steps:
- Pull your current declarations page, note your roof age and material, and list any recent upgrades (impact windows, roof anchors, storm shutters).
- Decide your preferred dwelling limit (use rebuild cost, not market value) and your deductible comfort level.
- Confirm whether you need separate flood coverage and whether NFIP or a private flood policy fits your timeline.
- Gather prior claims history (three to five years) and photos of your roof, siding, and drainage.
- Contact Hettler Insurance Agency to compare quotes across 30+ carriers with one call, at no extra fee.
Table of Contents
- Key Takeaways
- How do you compare homeowners quotes side by side?
- How do you gather the right information before requesting quotes?
- How do you document your home before a hail or flood claim?
- Why does working with an independent Texas agent matter?
- What most Texas homeowners get wrong about coverage
- Hettler Insurance Agency is ready to shop Texas carriers for you
- Useful sources and further reading
- Frequently Asked Questions
Key Takeaways
Finding the best coverage for your Texas home requires matching limits to rebuild cost, confirming deductible structure for wind/hail, securing separate flood coverage before you need it, and working with an independent agent who can compare carriers and endorsements on your behalf.
| Point | Details |
|---|---|
| Match dwelling to rebuild cost | Set your dwelling limit to rebuild cost, not market value, to avoid being underinsured after a loss. |
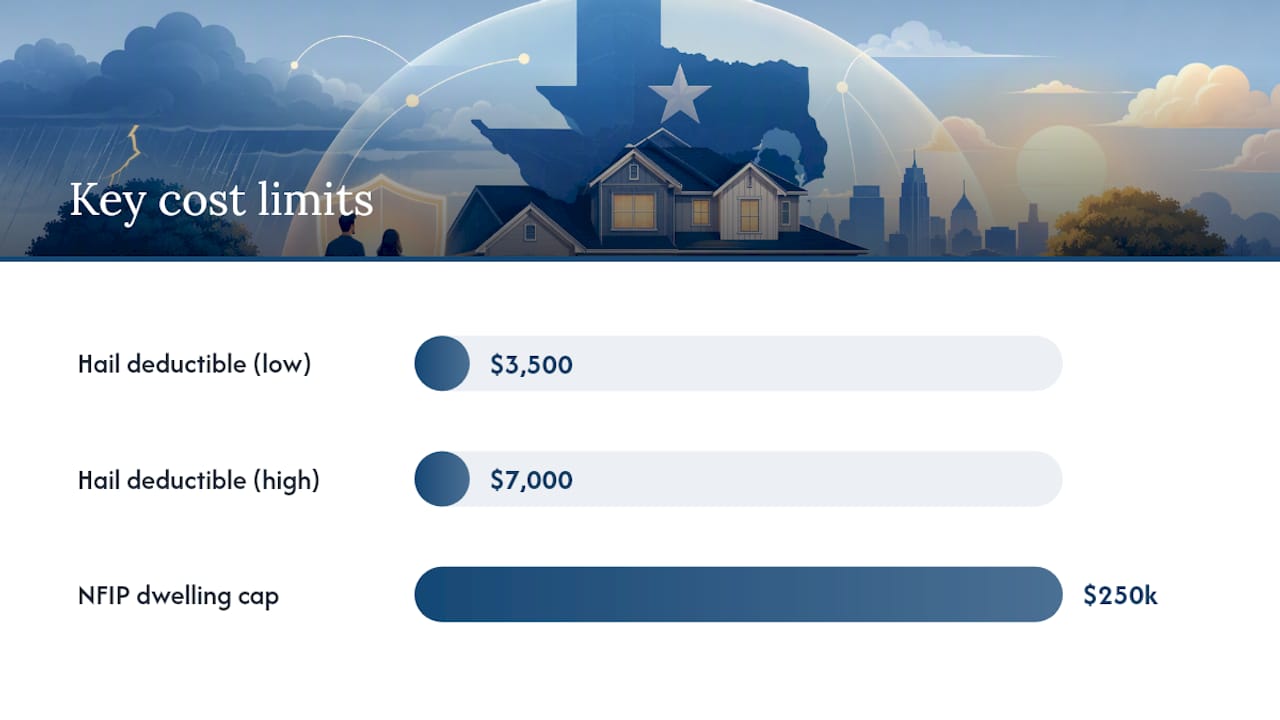
| Confirm wind/hail deductible type | A percentage deductible is calculated from your dwelling value. For example only: a 1%–2% deductible on a $350,000 home means $3,500–$7,000 out of pocket per hail event. |
| Flood coverage is separate | Standard homeowners policies exclude flood. NFIP policies typically carry a 30-day waiting period and a $250,000 dwelling cap; private flood can fill gaps for higher-value homes. |
| Compare full cost of risk | Evaluate premium plus deductible exposure plus coverage gap exposure — not premium alone. |
| Hettler Insurance Agency shops 30+ carriers | Hettler Insurance Agency compares carriers and endorsements for Texas homeowners at no extra fee. |
How do you compare homeowners quotes side by side?
Price alone is an unreliable indicator of best value. Comparing multiple personalized quotes with matching coverage limits and deductibles is the only way to know which policy actually protects you better. The Texas Department of Insurance Home Insurance Guide is a helpful, plain-language starting point.
Build a comparison grid with these rows for each quote you receive:
- Covered perils — named perils vs. open perils (all-risk)
- Dwelling limit — confirm it matches your rebuild cost estimate
- Other structures / personal property limits
- Deductible type and amount — flat dollar vs. percentage for wind/hail
- Replacement cost vs. ACV — for dwelling and personal property separately
- Exclusions and endorsements included — ordinance & law, sewer backup, mold cap
- Flood coverage source — NFIP or private, and the waiting period
- Annual premium and available discounts — bundling, impact-resistant roof, storm shutters
- AM Best financial strength rating and NAIC complaint ratio for the carrier
Start every comparison with identical coverage details and test best-case, expected, and worst-case cost scenarios. A policy with a percentage wind/hail deductible means a significant out-of-pocket cost before the carrier pays on a hail claim. That number belongs in your comparison, not just the annual premium.
Use the table below as your side-by-side checklist. Line up every quote you receive against each row before you compare price.
| Coverage Element | What to Look For | Red Flag |
|---|---|---|
| Covered perils | Open perils (all-risk) on the dwelling | Named perils only, or a long list of exclusions |
| Dwelling limit | Matches your rebuild cost estimate | Based on market value or appraisal district value |
| Other structures & personal property | Limits that fit your detached garage, fence, and belongings | Low sub-limits on jewelry, firearms, or electronics |
| Wind/hail deductible | A deductible amount you could pay tomorrow without strain | A percentage deductible you haven’t converted to dollars |
| Roof settlement | Replacement cost value (RCV) | Actual cash value (ACV), or a roof-age payment schedule |
| Personal property settlement | Replacement cost on contents | ACV on contents (depreciation is deducted) |
| Key endorsements | Ordinance & law, water/sewer backup, and extended replacement cost | Missing endorsements or a low mold cap |
| Flood coverage | A separate NFIP or private flood policy in place | No flood policy, or one bought within the 30-day waiting period |
| Premium & discounts | Bundling, impact-resistant roof, and mitigation discounts applied | A low premium that hides a coverage gap |
| Carrier strength | Strong AM Best rating and a low NAIC complaint ratio | No financial rating listed, or a high complaint ratio |
Exclusions and endorsements vary widely from carrier to carrier; a low premium can hide coverage gaps that create large out-of-pocket exposure when a claim hits.
Pro Tip: Ask each agent or carrier to provide a written quote breakdown, not just a total premium. Request the actual endorsement language for any rider you care about — especially wind/hail deductible structure and roof coverage terms — before you bind the policy.
How do you gather the right information before requesting quotes?
Accurate quotes require accurate inputs. Agents who receive incomplete information will make assumptions, and those assumptions may not match your actual risk.
- Pull your current declarations page — it shows your existing limits, deductibles, and endorsements.
- Get a rebuild cost estimate for your home. Your county appraisal district value is not the same number.
- Note your roof age, material (3-tab shingle, metal, tile), and whether you have documentation of recent repairs.
- Photograph the exterior, roof, and any recent upgrades, and save dated copies off-site.
- List mitigation upgrades: impact-resistant windows, storm shutters, roof anchors, backflow valves.
- Compile your claims history for the past three to five years.
- Know your mortgage lender’s minimum coverage requirements.
Questions to ask every agent before you bind:
- Is the wind/hail deductible a flat dollar or a percentage of dwelling value?
- Does the roof settle at replacement cost or ACV, and does roof age affect that?
- Which endorsements are included vs. optional and at what cost?
- What is the flood waiting period, and is this an NFIP or private policy?
- What bundling discounts apply if I add auto or other policies?
Request the quote in writing with a line-item breakdown. Learning to read the policy language itself — coverage limits, sub-limits, exclusions, and endorsements — is the fastest way to catch gaps before they cost you.
How do you document your home before a hail or flood claim?
Strong claims start before the storm, not after it. A well-documented home moves through the claims process faster and with fewer disputes.
Documentation checklist:
- Dated photos of the roof, gutters, siding, windows, HVAC unit, and landscape drainage
- Receipts for all recent repairs and upgrades, including roofing contractor invoices
- Serial numbers and purchase receipts for major appliances and electronics
- A room-by-room home inventory (video walkthroughs work well)
- Contractor estimates that establish pre-loss condition for any ongoing maintenance
Mitigation steps that also support claims:
- Clean gutters and downspouts before storm season
- Trim trees and large branches near the roofline
- Install backflow valves to reduce sewer backup risk
- Keep warranties and maintenance records for roofing work
Do not sign a post-loss repair waiver or endorse a settlement check that releases your full claim rights until you understand exactly what is being settled. Document the damage thoroughly, get independent contractor estimates, and consult your agent before accepting a final payment. Signing too quickly is one of the most common and costly mistakes Texas homeowners make after a storm.
Pro Tip: Store your home inventory and key documents in cloud storage or a fireproof location off-site. After a major storm, you may not have access to your home for days.
Why does working with an independent Texas agent matter?
An independent agent shops multiple carriers on your behalf, which a single-company (captive) agent cannot do. For Texas homeowners with hail and flood exposure, that carrier access is the difference between a policy that fits and one that leaves gaps.
Independent agents also advise on endorsements, confirm that dwelling limits match rebuild cost, and advocate for you during the claims process — not for the carrier. When your roof claim is disputed or your flood adjuster is slow, your agent is the person who knows which levers to pull.
Hettler Insurance Agency has served Texas homeowners from Lubbock since 1992, representing 30+ top-rated carriers. Founder and president Ron Hettler, CIC (Certified Insurance Counselor), and his daughter Meghan Harris, who co-leads the agency with Ron, both hold the Certified Insurance Counselor (CIC) credential, the gold standard in the industry. Fewer than 2% of licensed insurance professionals in the U.S. hold the CIC designation. The agency carries an A+ Better Business Bureau rating, a 4.5-star Google customer rating, and has been recognized by both Three Best Rated® and Expertise.com as a leading insurance agency in Lubbock. As a family-owned, independent agency, we shop and compare carriers at no extra fee to you.
Comparing insurance quotes in Texas is more complex than running a quick online search — carrier appetite, deductible structures, and endorsement availability vary significantly by ZIP code and home characteristics. That local knowledge is what an independent agent brings.
Pro Tip: Use an independent agent for any policy with hail, flood, or custom-home complexity. Online quote tools are useful for simple risks, but they rarely surface the endorsement-level detail that determines whether a Texas homeowners policy actually performs after a storm.
What most Texas homeowners get wrong about coverage
The conventional wisdom is to shop for the lowest premium. After years of watching Texas homeowners navigate hail and flood claims, the real problem is clearer: most people compare the wrong number.
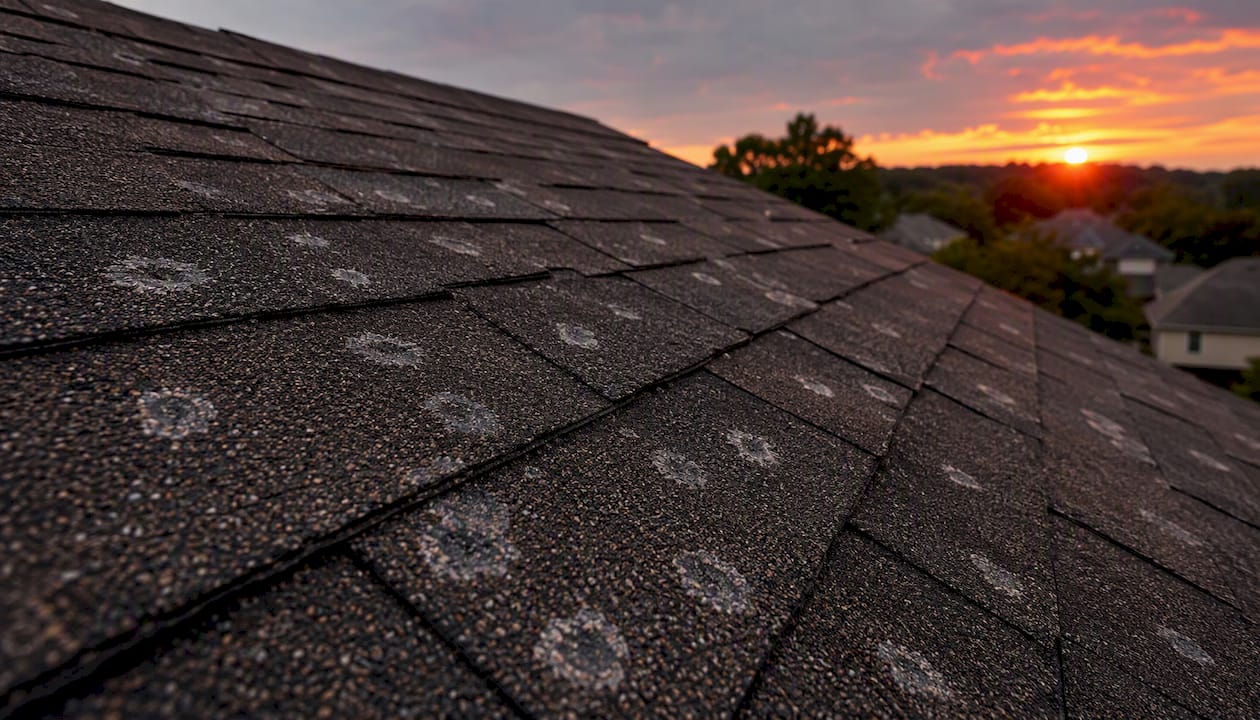
A small annual premium savings means little if your wind/hail deductible is 2% instead of a flat $1,000. For example purposes only: on a $400,000 home, that difference is $7,000 out of pocket on the first hail claim, which can quickly erase any premium savings.
The second mistake is treating flood as optional. Texas is not just a coastal flood state. Inland flooding from heavy rain events affects homes nowhere near a designated flood zone, including low-lying streets and playa lake areas across West Texas. Learn more about flood insurance or visit FEMA’s FloodSmart.gov. NFIP’s 30-day waiting period means the time to buy is now, not when a storm is named.
Annual coverage reviews catch both problems. Reviewing all active policies annually, checking rebuild cost, and shopping rates is the discipline that keeps coverage current. The homeowners who fare best after Texas storms are the ones who reviewed their policy in February, not the ones who called their agent in April after the hail hit.
Hettler Insurance Agency is ready to shop Texas carriers for you
Texas homeowners who want real carrier choice — not a single company’s best offer — get it through an independent agency. Hettler Insurance Agency shops 30+ top-rated carriers to find the right combination of dwelling limits, deductible structure, flood options, and endorsements for your specific home and ZIP code. No pressure, no extra fee, and no guessing about whether your policy actually covers West Texas hail.

Before you call, have your declarations page, roof age, recent upgrade list, and preferred limits ready. That preparation turns a 20-minute conversation into a productive quote comparison rather than a data-gathering session.
Request your quotes online or call Hettler Insurance Agency to get started. You can also review bundling options for home and auto to see whether combining policies reduces your total cost. If you want to think through your limits before the call, How Much Home Insurance is Enough? is a useful starting point.
Useful sources and further reading
- Texas Department of Insurance — Home Insurance Guide: TDI’s plain-language guide to Texas homeowners coverage, policy forms, deductibles, and windstorm coverage.
- FEMA FloodSmart — National Flood Insurance Program: How NFIP flood insurance works, including waiting periods and coverage limits.
- Hettler Insurance Agency — How Much Home Insurance is Enough?: How to think about dwelling limits and rebuild cost.
- Hettler Insurance Agency — Flood Insurance: NFIP and private flood options for Texas homeowners.
- Hettler Insurance Agency — How to Compare Insurance Quotes in Texas: A step-by-step quote comparison guide.
This article provides general insurance information for educational purposes. Coverage terms, limits, and availability vary by carrier, policy, and location. Confirm current rules and policy details with a licensed insurance professional before making coverage decisions.
Frequently Asked Questions ?
Q1 ?: How do I compare Texas homeowners insurance quotes side by side?
Q2 ?: Should my dwelling limit match my home’s market value?
Q3 ?: What is the difference between a flat and a percentage wind/hail deductible?
Q4 ?: Does Texas homeowners insurance cover flood damage?
Q5 ?: How should I document my home before a hail or flood claim?
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [a gold-standard credential in the independent insurance industry that less than 2% earn]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots 100+ years going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com