
TL;DR summary:
- Insurance riders are legal amendments that customize existing policies to better suit individual risks and needs. They work by attaching to the primary policy, overriding exclusions, and closing coverage gaps, often at modest additional costs. Most riders should be selected at policy purchase since late additions require underwriting and may be denied or costlier.
An insurance rider is an amendment to an existing insurance policy that modifies or supplements coverage to better match your individual risks and requirements. Known formally as an endorsement in many policy contracts, a rider is a separate legal document attached to your base policy. Riders span all major insurance lines including home, life, auto, disability, and health insurance, functioning consistently as policy customizations across every product type. Understanding what insurance riders are and how they work is the first step toward building coverage that actually fits your life.
Most people buy a standard policy and assume it covers everything they own or every risk they face. It does not. A base policy is a starting framework, not a complete solution. Riders exist to close the gaps between what a standard policy covers and what you actually need protected. Whether you are a homeowner in Lubbock with a collection of high-value jewelry, a 35-year-old with a young family relying on your life insurance, or a driver who wants roadside assistance built into your auto policy, riders give you the ability to customize coverage without buying an entirely separate policy.
Table of Contents
- Key takeaways
- How do insurance riders work?
- Common types of insurance riders and their benefits
- What does an insurance rider cost?
- Key considerations when choosing insurance riders
- Why I think most people underuse riders and pay for it later
- How Hettler Insurance Agency helps you find the right riders
- Frequently Asked Questions
Key takeaways
Insurance riders are the most cost-effective tool for closing coverage gaps in any base policy, and selecting them at the time of purchase is the single most important decision you can make.
| Point | Details |
|---|---|
| Riders are legal amendments | Each rider carries full contract weight and can override base policy exclusions within its scope. |
| Cost increase is modest | Premium increases typically range 5-15%, far less than the cost of a standalone policy for the same risk. |
| Timing is critical | Most life insurance riders must be selected at policy purchase; later additions require new underwriting. |
| Some riders cost nothing | Accelerated death benefit riders are often included at no extra charge on life insurance policies as of 2026. |
| Gap analysis drives decisions | Compare the annual rider cost to the financial exposure of going without it before adding or skipping any rider. |
How do insurance riders work?
A rider attaches legally to your primary policy and modifies its terms from the moment it takes effect. Riders carry full legal weight as contract documents and can override base policy exclusions within their defined scope. That means if your base homeowners policy excludes coverage for a specific item or event, a properly written rider can reverse that exclusion and create enforceable coverage.
Most riders are added at the time of policy purchase. Some insurers allow mid-term additions, but those typically require underwriting review, which means the insurer evaluates your risk profile again before approving the change. For life insurance specifically, adding a rider later often requires new underwriting that can increase costs or result in denial if your health or age has changed.
Here are the most common real-world use cases where riders solve a specific coverage problem:
- Jewelry and valuables: Standard homeowners policies often cap jewelry coverage at $1,000. If you own an engagement ring worth $8,000, a scheduled personal property rider closes that gap directly.
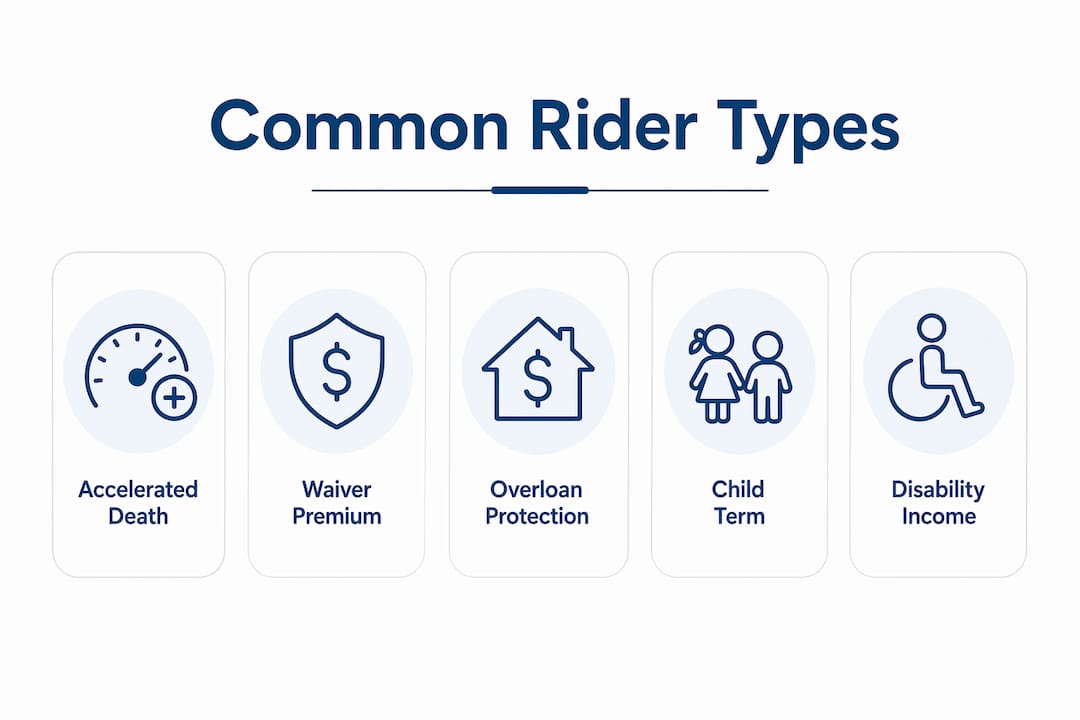
- Accelerated death benefit: A life insurance rider that allows the policyholder to access a portion of the death benefit while still living if diagnosed with a terminal illness.
- Waiver of premium: Suspends your life insurance premium payments if you become totally disabled, keeping the policy active without out-of-pocket cost.
- Roadside assistance: An auto insurance rider that covers towing, flat tire service, and lockout assistance, typically at a fraction of what a standalone roadside plan costs.
Pro Tip: Ask your insurer for a written list of all available riders before you finalize any policy. Many riders are never mentioned unless you ask, and some of the most valuable ones, like the accelerated death benefit on life policies, may already be included at no extra charge.
Common types of insurance riders and their benefits
Riders are not one-size-fits-all. The right rider depends entirely on your policy type, your assets, and your personal risk exposure. The table below outlines the most common rider categories across major insurance lines.
| Rider type | Policy line | What it covers | Typical cost impact |
|---|---|---|---|
| Accelerated death benefit | Life | Access to death benefit during terminal illness | Often included at no extra cost |
| Waiver of premium | Life | Suspends premiums during total disability | Small premium increase |
| Long-term care rider | Life | Covers nursing home or in-home care costs | Moderate premium increase |
| Term conversion rider | Life | Converts term policy to permanent without new underwriting | Varies by insurer |
| Scheduled personal property | Homeowners | Covers high-value items above standard limits | 5-15% premium increase |
| Sewer backup coverage | Homeowners | Covers water damage from sewer or drain backup | Low to moderate cost |
| Rental reimbursement | Auto | Pays for a rental car while your vehicle is being repaired | Minimal cost |
| Roadside assistance | Auto | Towing, fuel delivery, lockout service | Minimal cost |
.
Certain life insurance riders, like the accelerated death benefit, are included automatically at no additional cost as of 2026. This means you may already have meaningful added protection without realizing it. Review your current policy declarations page to confirm which riders are already active.
The benefits of adding riders go beyond just filling gaps. Riders give you flexibility to adjust coverage as your life changes, enhanced protection for specific assets or risks that a base policy ignores, and the peace of mind that comes from knowing your policy reflects your actual situation. For Texas homeowners dealing with hail, flooding, or high-value personal property, riders are not optional extras. They are the difference between a payout and a denial.
What does an insurance rider cost?
Premium increases from riders typically range from 5 to 15 percent per rider added. That range sounds wide, but the actual cost depends on three factors: the type of rider, the insurer’s pricing model, and your personal profile including age, health, claims history, and the coverage amount requested.
To put that in practical terms: if your homeowners policy costs $1,800 per year and you add a scheduled personal property rider for a $10,000 jewelry collection, you might pay an additional $90 to $270 annually. Compare that to insuring the same jewelry under a standalone valuables policy, which could cost significantly more and require separate management. Riders win on cost efficiency in almost every comparison.
The table below illustrates how rider costs stack up against the financial risk of going without them.
| Scenario | Without rider | With rider | Annual rider cost (est.) |
|---|---|---|---|
| $8,000 engagement ring stolen | Recover only $1,000 (standard limit) | Recover full $8,000 | $80-$200 |
| Terminal illness, need early benefit access | No access to death benefit | Access up to 50-90% of benefit | $0 (often included) |
| Disabled, cannot pay life premiums | Policy lapses | Policy stays active | $50-$150 |
| Rental car needed during auto repair | Pay out of pocket ($40-$60/day) | Covered up to policy limit | $20-$50/year |
.
Gap analysis is the correct framework for evaluating any rider: compare the annual premium increase to the financial exposure you carry without the rider. If the math favors the rider, add it.
Pro Tip: When comparing policies across carriers, ask each insurer to quote the same base policy with and without your desired riders. Independent agents like those at Hettler Insurance Agency can run those comparisons across 30-plus carriers simultaneously, which saves you hours and often reveals significant price differences for identical coverage.
Key considerations when choosing insurance riders
Selecting the right riders requires more than scanning a list and checking boxes. Timing, policy language, and your personal circumstances all affect which riders make sense and whether you can even get them.
- Select riders at policy purchase. Most life insurance riders must be chosen during the application process. Waiting until after the policy is bound often means new underwriting, higher costs, or outright denial based on age or health changes. Do not assume you can add riders later without consequence.
- Read the coverage limits carefully. A rider that sounds comprehensive may have its own sub-limits. A personal property rider for jewelry might cover up to $15,000 per item but exclude mysterious disappearance. Know exactly what the rider covers and what it excludes before you pay for it.
- Compare rider definitions across carriers. The same rider name can mean different things at different insurers. A “long-term care rider” at one company might require a 90-day elimination period before benefits begin, while another starts at 30 days. Definitions matter as much as the rider name itself.
- Understand the legal weight of what you are signing. A rider is a separate legal document appended to your policy. Riders and endorsements are legally equivalent, and both formally amend the original policy contract with the same legal authority. If a rider conflicts with your base policy, the rider typically governs within its scope.
- Match riders to your life stage. A 28-year-old with no dependents has different rider priorities than a 45-year-old with a mortgage, two kids, and a spouse who does not work. The waiver of premium rider matters more when others depend on your income. The term conversion rider matters more when you are young and healthy and want to lock in future insurability.
- Do not ignore auto policy add-ons. Riders are not just a life and homeowners concept. If you use your personal vehicle for rideshare driving, your standard auto policy may not cover those trips at all. A rideshare endorsement closes that gap directly.
The most common mistake people make is assuming riders can be added at any time with no consequences. That assumption leads to underinsurance at exactly the moment when coverage matters most.
Why I think most people underuse riders and pay for it later
Most policyholders I have spoken with over the years treat their insurance policy like a utility bill. They set it up once, pay it monthly, and never look at it again until they need to file a claim. That is exactly when they discover the gaps. And by then, it is too late to add the rider that would have covered the loss.
The uncomfortable truth is that basic policies are starting points, not finished products. Insurers design base policies to cover the most common risks at the lowest price point. Anything outside that common profile, a valuable collection, a disability risk, a terminal illness scenario, falls into the gap. Riders are how you fill those gaps before they cost you.
What I have found actually works is treating the rider selection process like a risk audit. You list every asset or scenario that your base policy does not explicitly cover, then price out the rider for each one. Most of the time, the math is obvious. A $150 annual rider that protects a $12,000 watch collection is not a close call. The decision becomes harder only when the risk is speculative, like a long-term care rider at age 35. In those cases, your life stage, family situation, and risk tolerance should drive the call, not a general rule.
The one thing I would push back on is the idea that riders are only for wealthy policyholders with expensive assets. A waiver of premium rider costs very little and protects any family that depends on a life insurance policy staying active. That is not a luxury add-on. That is basic financial protection.
— Ron Hettler
How Hettler Insurance Agency helps you find the right riders
Hettler Insurance Agency has been helping Texans build smarter coverage since 1992, and riders are a core part of every policy review the team conducts. As an independent agency representing over 30 top-rated carriers, Hettler Insurance Agency compares rider availability, definitions, and pricing across insurers to find the combination that fits your specific situation, not just the cheapest base premium.

Whether you need a scheduled personal property rider for your homeowners policy, a waiver of premium on your life insurance, or guidance on auto policy customization, the team at Hettler Insurance Agency walks you through every option without pressure. If you are building coverage from scratch or reviewing an existing policy for gaps, start with the minimum coverage framework to understand your baseline, then call Hettler Insurance Agency to add the riders that close your specific gaps. Ron and Meghan Hettler, both Certified Insurance Counselors, bring the expertise to get it right the first time.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What is an insurance rider in simple terms?
Q2 ?: Are insurance riders worth the extra cost?
Q3 ?: Can I add a rider to my policy at any time?
Q4 ?: What is the most common life insurance rider?
Q5 ?: Do homeowners insurance policies need riders?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com