TL;DR summary:
- A smart home and auto bundling workflow comes down to four moves: gather your current declarations pages and your home’s replacement cost, request bundled and separate quotes from at least three carriers using identical coverage, compare the combined totals (not just the discount percentage), and keep your old policies active until the new bundle is bound and your mortgage lender has been notified. An independent agent can run that comparison across multiple carriers at once and help you avoid the coverage gaps that a cheaper-looking bundle can hide.
Start today: contact at least three insurers, including your current carrier, and request both bundled and separate quotes using identical coverage limits. That single action is the foundation of every smart home and auto bundling workflow.
Before you make any calls, run through this quick checklist:
- Gather your policy details. Pull your current home and auto declarations pages, including coverage limits, deductibles, and any endorsements you carry.
- Request side-by-side quotes. Ask each insurer to show you the combined bundled premium and the two separate premiums so you can do the math yourself.
- Do not cancel your existing policy until the new one is active. Even a short gap in coverage can create a lapse that raises your future rates.
With your documents ready, many households can complete the process within a week or two, depending on the carriers and your lender. Gather your VINs, mortgage account number, and current policy numbers before you start.
Pro Tip: Ask each insurer whether the multi-policy discount stacks with other discounts you already qualify for, such as multi-vehicle, claims-free, or safety-feature credits. Stacking can meaningfully increase total savings.
Table of Contents
- Key Takeaways
- What does bundling home and auto insurance actually mean?
- What are the real benefits of bundling home and auto?
- When can bundling backfire?
- How to bundle home and auto: the complete workflow
- How should you shop and compare bundled quotes?
- What coverage checks should you run before finalizing a bundle?
- How long does the bundling process take?
- What mistakes and red flags should you watch for?
- Why an independent agent makes bundling easier
- Hettler Insurance Agency shops your bundle across 30+ carriers
- Sources
- Frequently Asked Questions
Key Takeaways
A properly executed home and auto bundling workflow requires identical coverage inputs across all quotes, lender notification before the old policy cancels, and a line-by-line coverage check before you accept any bundle offer.
| Point | Details |
|---|---|
| Get at least 3 quotes | Include your current carrier and request both bundled and separate totals for a real comparison. |
| Verify replacement cost first | Set your dwelling limit to full rebuild cost, not market value, before comparing any premiums. |
| Confirm discount stacking | Ask each insurer whether the multi-policy discount combines with multi-vehicle, claims-free, or safety credits. |
| Notify your mortgage lender | Alert your lender before the old homeowners policy cancels to avoid escrow errors or a coverage gap. |
| Hettler Insurance Agency shops 30+ carriers | One call to Hettler Insurance Agency produces side-by-side bundle quotes across multiple carriers with coverage already aligned. |
What does bundling home and auto insurance actually mean?
Bundling, also called a multi-policy discount arrangement, means purchasing two or more personal lines policies from the same insurer or affiliated carrier group. The most common pairing is homeowners and auto, but some carriers extend the discount to renters, umbrella, motorcycle, or boat policies added to the same account.
Two bundling models exist, and knowing the difference matters when you shop:
- Single-carrier bundling. Both policies are underwritten by the same company. This is the cleanest arrangement: often one bill, one renewal date, and one company to call.
- Affiliated-carrier bundling. A parent company owns separate underwriting entities for home and auto. The discount still applies, but you may deal with two separate policy numbers and occasionally two billing cycles.
The multi-policy discount is typically applied as a percentage reduction on one or both premiums. Some carriers reduce only the auto premium; others split the discount across both policies. Always ask which policy line receives the reduction so you can verify it on your declarations page after purchase.
What are the real benefits of bundling home and auto?
The financial case for bundling is well-documented, but the size of the discount varies widely. The Texas Department of Insurance Home Insurance Guide encourages homeowners to compare companies and ask about available discounts before buying. For example only, according to online sources, NerdWallet reports that certain insurers advertise bundling discounts of up to 30% or 40%, though actual savings vary by state, household profile, and carrier.
For Texas homeowners, our earlier guide explains how you may be able to bundle home and auto insurance and save up to 26% in Texas, depending on your home’s replacement cost, your driving record, and which carrier you use.
Beyond the dollar savings, bundling delivers real administrative convenience:
- One bill, one renewal date. Fewer deadlines to track means fewer chances to accidentally let a policy lapse.
- One company to call. When a West Texas hailstorm damages both your roof and your car, you start both claims with the same company, even if separate adjusters handle the home and auto sides.
- Aligned policy terms. Matching renewal dates make annual shopping easier because you review both policies at the same time.
- Simpler annual reviews. With both policies in one place, it is easier to spot gaps, update coverage after life changes, and keep liability limits aligned.
When can bundling backfire?
Bundling is not automatically the right move. Several scenarios can make a bundle more expensive or less protective than keeping policies separate.
- High-risk drivers on the auto policy. If one household driver has recent accidents or violations, the auto premium at a given carrier may be uncompetitive even after the bundle discount. A different auto carrier might beat the bundled rate by enough to offset losing the home discount.
- Very low home replacement cost. If your home’s rebuild value is modest, the dollar savings from a home discount are small. The auto discount alone may not justify switching both policies.
- Credit profile mismatches. In Texas and most states, insurers may use credit-based insurance scores. If one policyholder’s credit pulls the combined rate up at a particular carrier, separate carriers may produce a lower combined total.
- Coverage mismatches hidden by price. The most dangerous bundling trap is accepting a lower premium that comes with reduced dwelling limits, higher deductibles, or missing endorsements. A cheaper bundle that drops your replacement-cost coverage or removes water-backup protection is not a savings.
Pro Tip: Run the math on separate policies every year at renewal, not just when you first bundle. Carriers adjust rates annually, and the bundle discount that made sense in year one may no longer produce the lowest combined total by year three.
Losing the habit of annual shopping is a real cost. Bundling usually saves money and simplifies management, but never assume a bundle is always the cheapest combination available.
How to bundle home and auto: the complete workflow
Follow these steps in order. Skipping steps, particularly the coverage-verification and lender-notification steps, is where most bundling mistakes happen.
Step 1: Collect your documents
Before requesting a single quote, gather:
- Current home declarations page (dwelling limit, deductible, endorsements)
- Current auto declarations page (liability limits, comprehensive/collision deductibles, listed drivers)
- Your home’s estimated replacement cost (not market value, not mortgage balance)
- VINs for all vehicles
- Mortgage account number and lender contact information
- Any lienholder information for financed vehicles
Step 2: Request quotes from at least three insurers
Contact your current carrier first, then at least two others. For each insurer, request both a bundled quote and separate quotes for home and auto. Use identical coverage limits, deductibles, and endorsements across all quotes so comparisons are genuinely apples-to-apples. A simple side-by-side format works well: list the separate home premium, separate auto premium, combined separate total, bundled home premium, bundled auto premium, and bundled total in one view.
Step 3: Compare bundled vs. separate totals
The comparison math is straightforward:
- Separate total: Current home premium + current auto premium
- Bundled total: New bundled home premium + new bundled auto premium
- Net savings: Separate total minus bundled total
Also confirm whether the bundle discount stacks with other discounts you qualify for, such as multi-vehicle, claims-free, or anti-theft credits. Ask each insurer explicitly. For more ideas, see our guide to real examples of insurance discounts you can claim now.
Step 4: Verify coverage before accepting
Before you accept any quote, confirm:
- Dwelling limit covers full replacement cost (not market value)
- Liability limits on both policies meet your needs
- Deductibles are set where you want them
- All endorsements you currently carry are included or replaced
Step 5: Accept the new policy and set the effective date
Once you select a bundle, bind the new policy and confirm the effective date in writing. Do not cancel your existing policies yet.
Step 6: Notify your mortgage lender and lienholders
Your mortgage lender requires proof of homeowners coverage and must be listed on the new policy as the mortgagee. Notify them of the carrier change before your old policy ends. For financed vehicles, notify the lienholder of the new auto carrier so it is listed as loss payee.
Step 7: Cancel old policies only after confirmation
Once you have written confirmation that the new bundle is active and your lender has been notified, cancel the old policies. Request written cancellation confirmation and ask how any pro-rated refund will be issued.
Step 8: Verify the bundle discount on your declarations page
Pull both new declarations pages and confirm the multi-policy discount is listed. If it is missing, call immediately. Carriers occasionally fail to link policies at binding.
How should you shop and compare bundled quotes?
Your shopping route affects both the quality of your comparison and the time it takes. Three main options exist.
Independent agents represent multiple carriers and can run bundled quotes across several insurers in a single conversation. They handle the apples-to-apples setup for you, help verify replacement cost, and can help coordinate lender notifications. The tradeoff is that they represent a subset of the market, not every carrier.
Direct online carriers let you quote quickly, but you are limited to that carrier’s own products. You will need to run separate quotes at multiple sites and do your own comparison math.
Comparison websites collect quotes from several carriers but do not sell the bundle themselves, and they vary in how accurately they reflect final bundled pricing. Always verify the quoted premium directly with the carrier or your agent before binding.
For a reliable comparison, check these line items on every quote:
- Dwelling replacement cost (confirm it matches your estimate, not the home’s sale price)
- Personal liability limit on homeowners (review it alongside your auto liability)
- Auto bodily injury and property damage liability limits
- Comprehensive and collision deductibles
- Any endorsements: water backup, scheduled personal property, roadside assistance
Pro Tip: Ask each insurer whether they use an affiliated carrier for one of the two policies. If the home is underwritten by a subsidiary you have not researched, check that company’s complaint record with the Texas Department of Insurance separately.
Always calculate the combined total, not just the bundle discount percentage.
What coverage checks should you run before finalizing a bundle?
Price is the wrong starting point. Coverage quality determines whether the bundle actually protects you.
- Replacement cost vs. actual cash value. Homeowners policies pay either replacement cost (what it costs to rebuild today) or actual cash value (replacement cost minus depreciation). Always confirm you have replacement-cost coverage. Our guide to replacement cost coverage explains how to set a defensible dwelling limit based on rebuild cost.
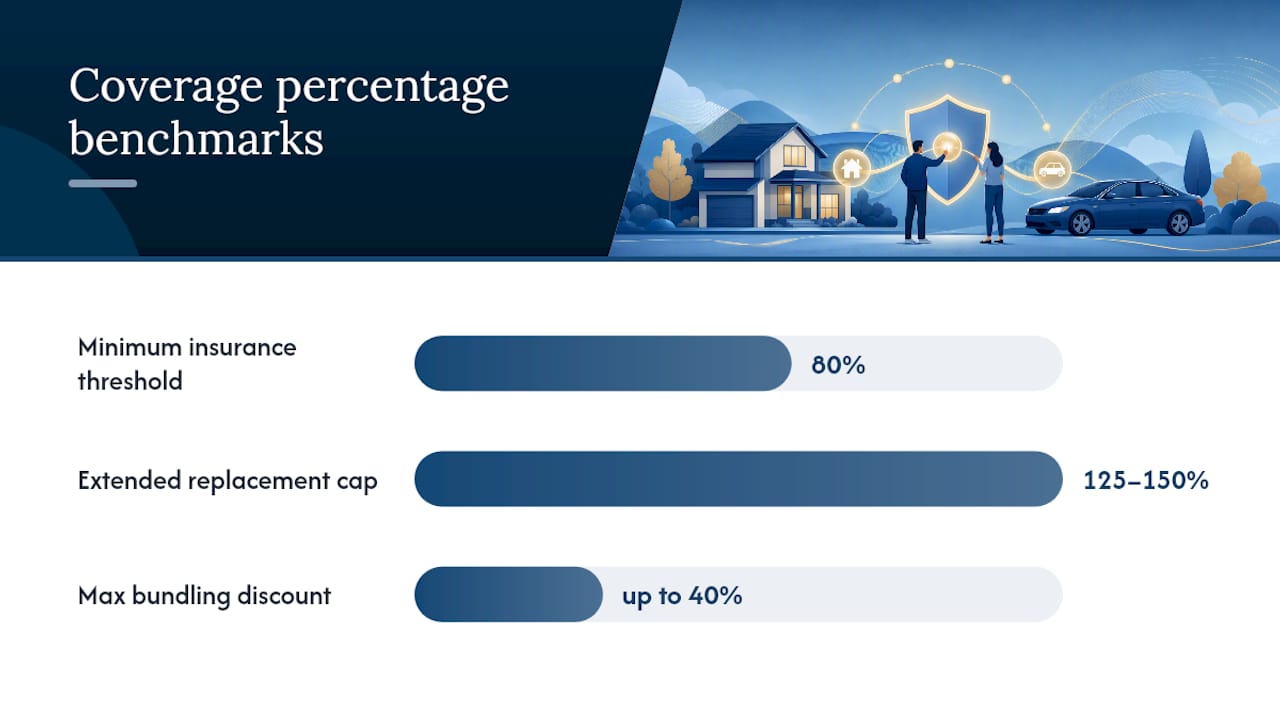
- The 80% rule. Many homeowners policies require you to insure your home to at least 80% of its replacement cost to receive full replacement-cost payment on a partial claim. Insuring below that threshold can mean the insurer pays only a proportional share of a loss, not the full repair cost. See how much home insurance is enough for a detailed breakdown.
- Guaranteed or extended replacement cost. Some carriers offer guaranteed replacement cost (pays whatever rebuild costs, no cap) or extended replacement cost (pays a set percentage above the dwelling limit). These options matter in high-inflation or post-disaster markets.
- Liability alignment. Your auto liability limits and homeowners personal liability limit should be reviewed together. If either is low, an umbrella policy adds a cost-effective layer of protection above both. Higher auto liability limits are often worth the modest premium increase.
- Claims-handling signals. Check each carrier’s complaint record with the Texas Department of Insurance and review J.D. Power homeowners and auto satisfaction scores. Ask your agent how local claims are handled: is there a local adjuster, or does everything route through a national call center?
Statistic callout: For example only, according to NerdWallet, some insurers advertise bundling discounts up to 40%, but the actual discount varies significantly by carrier, state, and household profile. Comparing coverage quality alongside discount size is the only way to know whether a higher-advertised discount translates to better value.
Pro Tip: Document your comparison. Save a PDF of every quote you receive, including the coverage details page, not just the premium summary. If a dispute arises after binding, you have a record of what was quoted.
How long does the bundling process take?
The timeline varies depending on your shopping method, the carriers involved, and your lender, but many households can complete the full workflow within a week or two.
| Stage | Common Timeframe (varies) |
|---|---|
| Gather documents and policy details | A few hours |
| Receive online quotes | Often the same day |
| Receive agent-assisted quotes | Often within a few business days |
| Review, compare, and decide | Your timeline |
| Bind new policy and set effective date | Once you decide |
| Notify mortgage lender and lienholders | Depends on the lender |
| Cancel old policies after confirmation | After the new policy is active and the lender is notified |
One consideration that surprises many homeowners: if your homeowners insurance is escrowed through your mortgage, your lender pays the premium from your escrow account. When you switch carriers mid-year, any pro-rated refund from the old carrier may be sent to you or to your escrow account, and the new premium is paid from escrow. Ask your lender how they handle the switch to avoid an escrow shortfall or double payment.
Key insight: The discount percentage alone does not tell you whether a bundle is a good deal. Compare total premiums and coverage side by side before you switch.
What mistakes and red flags should you watch for?
Most bundling errors fall into a small number of categories. Catching them early saves money and prevents coverage gaps.
Common mistakes:
- Comparing quotes with different coverage amounts (lower dwelling limit on the bundled quote makes it look cheaper than it is)
- Forgetting to notify the mortgage lender before the old policy cancels
- Assuming endorsements carry over automatically (they do not; confirm each one)
- Canceling the old policy before the new one is confirmed active
- Accepting a bundled quote without verifying the discount is actually applied at binding
Red flags that warrant additional questions:
- The insurer cannot clearly identify which entity underwrites the home policy
- The bundled quote uses actual cash value instead of replacement cost on the dwelling
- The insurer has a poor complaint record with the Texas Department of Insurance
- The agent cannot explain how the bundle discount interacts with other discounts you carry
- The quoted dwelling limit is significantly lower than your replacement cost estimate
- No local claims adjuster is available; all claims route through a national call center
If you encounter more than one of these red flags with a single carrier, request a full explanation before binding. A bundle that saves a little each year but leaves you underinsured on your home is not a good trade.
Why an independent agent makes bundling easier
The practical case for using an independent agent comes down to comparison efficiency and execution. When you shop on your own, you run one quote at a time, manually align coverage details across carriers, and handle lender notifications yourself. An independent agent runs multiple carrier quotes using the same coverage inputs, so the comparison is genuinely apples-to-apples from the start. “The best independent insurance agents don’t just find you a policy. They find you the right insurance policy and then make sure it stays right as your life changes.” — Ron Hettler, CIC (Certified Insurance Counselor), Hettler Insurance Agency
What gets missed in the DIY approach is the carrier-specific detail work: some carriers offer guaranteed replacement cost only as an endorsement, others include it by default; some apply the bundle discount to the auto policy, others split it. An agent who works with those carriers daily knows which questions to ask and where the gaps tend to appear. An agent can also help coordinate the mortgage lender notification, which is one of the most commonly skipped steps in the workflow.
A long-term agent relationship also makes the annual review easier. A stable relationship with an agent who knows your coverage history is worth something at claim time. Learn more about why to use an independent insurance agent.
Hettler Insurance Agency shops your bundle across 30+ carriers
Hettler Insurance Agency is a family-owned independent agency in Lubbock, Texas, representing over 30 top-rated carriers. For homeowners who want a bundle comparison done right, that means one conversation produces quotes from multiple insurers, all set to the same coverage limits, so the comparison math is clean before you ever see a number.
When you contact Hettler Insurance Agency, bring your current declarations pages, your home’s estimated replacement cost, and your VINs. The team helps verify your dwelling replacement cost, confirms the bundle discount is applied correctly at binding, and helps coordinate your mortgage lender notification. Ron Hettler, CIC (Certified Insurance Counselor), agency founder and president with 45+ years of insurance industry experience, and Meghan Harris, CIC, who co-leads the agency with Ron, have helped Texas families since the agency opened in 1992. The agency carries a 4.5-star Google rating and an A+ BBB rating. To get your side-by-side comparison started, visit Hettler Insurance Agency or call the Lubbock office directly at (806) 798-7800.
Hettler Insurance Agency is one of the few family-owned agencies in Texas where both principals carry the high level certification of CIC (Certified Insurance Counselor). Fewer than 2% of licensed insurance professionals in the U.S. have earned the CIC designation.
Sources
These sources cover the key areas of the bundling decision: savings data, coverage standards, and state-level guidance.
- Home Insurance Guide — Texas Department of Insurance
- The Best Home and Auto Insurance Bundles for 2026 — NerdWallet
This article provides general information and is not a substitute for advice from a licensed insurance professional. Discounts, coverage, and eligibility vary by carrier and policy.
Frequently Asked Questions ?
Q1 ?: What are the steps in a home and auto bundling workflow?
Q2 ?: Is bundling home and auto insurance always cheaper?
Q3 ?: Should I cancel my old policy before my new bundle starts?
Q4 ?: What coverage should I check before accepting a bundle?
Q5 ?: Why use an independent agent to bundle home and auto?
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [a gold-standard credential in the independent insurance industry that less than 2% earn]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots 100+ years going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com