TL;DR summary:
- Choosing a licensed and independent insurance agent in Texas ensures you receive multiple quotes and proper advocacy during claims. Verifying credentials through the Texas Department of Insurance and asking key questions about carrier options and local knowledge helps find a trustworthy professional. Long-term value depends on transparent communication, regional expertise, and ongoing support after policy binding.
Choosing the right insurance agent is the single most important step a Texas homeowner can take before signing any policy. An insurance agent is a licensed professional who represents carriers, explains coverage options, and advocates for you when a claim goes wrong. Texas law requires agents to hold a valid state license, and regulatory bodies like the Texas Department of Insurance (TDI) and the National Association of Insurance Commissioners (NAIC) exist specifically to protect you from bad actors. This guide walks you through every step of the agent selection process, from verifying credentials to asking the questions that reveal whether an agent truly works for you. “The best independent insurance agents don’t just find you a policy. They find you the right insurance policy and then make sure it stays right as your life changes.” — Ron Hettler, CIC (certified insurance counselor), Hettler Insurance Agency
Table of Contents
- Key Takeaways
- How to use this choosing the right insurance agent guide to verify credentials first
- What is the difference between captive and independent agents?
- What questions should you ask an insurance agent before hiring?
- How do you evaluate an agent’s local knowledge and customer service?
- What I have learned after watching homeowners pick the wrong agent
- Hettler Insurance Agency: local Texas expertise when it matters most
- Frequently Asked Questions
Key Takeaways
Choosing the right insurance agent requires verifying credentials through the TDI and NAIC, comparing independent versus captive agent types, asking direct questions about compensation and claims advocacy, and confirming local expertise before signing any policy.
| Point | Details |
|---|---|
| Verify licensing first | Call the TDI Help Line at 800-252-3439 before sharing personal information with any agent. |
| Choose independent over captive | Independent agents quote multiple carriers, giving you real price and coverage comparisons. |
| Ask about claims advocacy | Confirm the agent personally guides you through claims, not just hands you off to the carrier. |
| Demand compensation transparency | Agents who disclose how they are paid upfront have fewer conflicts of interest. |
| Confirm local risk knowledge | Your agent must understand Texas-specific perils like hail, flooding, and windstorms to cover you properly. |
.
How to use this choosing the right insurance agent guide to verify credentials first
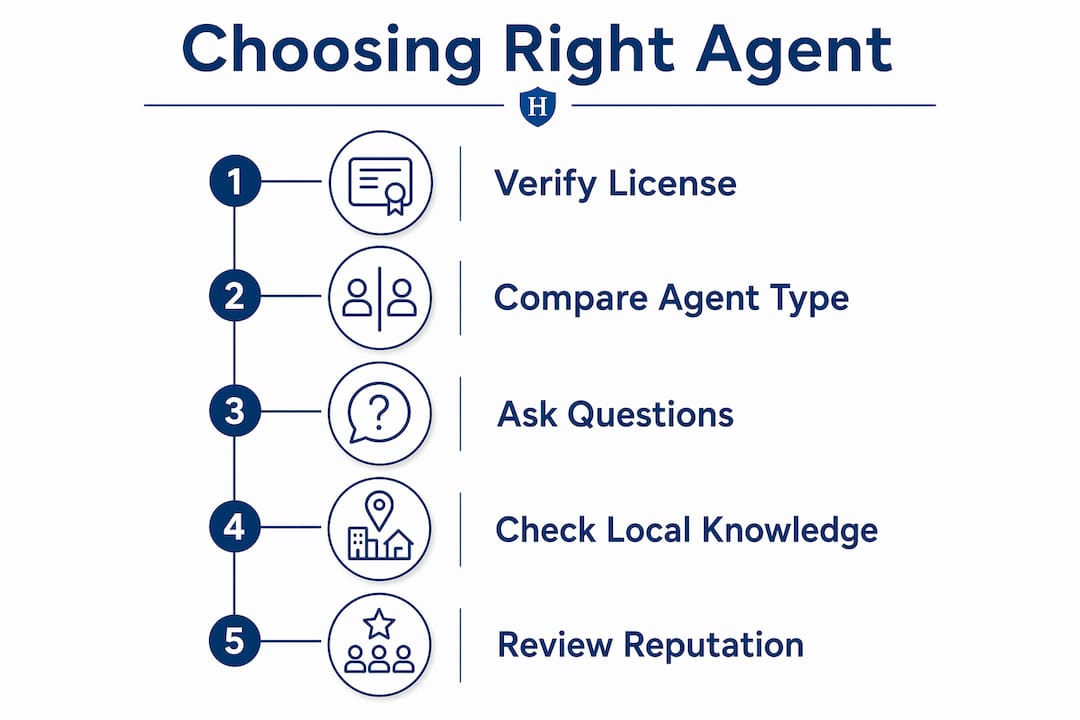
The first step in any insurance agent selection guide is license verification. The TDI Help Line at 800-252-3439 provides license status, complaint history, and disciplinary actions for any agent operating in Texas. Call before you share personal information or sign anything.
License verification is necessary, but it is not sufficient on its own. Texas license status confirms that an agent is authorized to sell insurance. It does not confirm that your specific policy was issued or that your payment was processed correctly. You must verify both separately after your policy is bound.
For agents who operate across state lines, the NAIC Producer Database and NIPR tools confirm active licenses, lines of authority, and expiration dates nationally. This matters if you own property in multiple Texas counties or plan to move.
Watch for these warning signs of an unlicensed or problematic agent:
- They cannot provide a license number when asked directly.
- They pressure you to sign documents before you have reviewed the policy.
- They refuse to give you a written quote or policy summary.
- They ask for cash payments or wire transfers instead of checks payable to the carrier.
- Their name does not appear in the TDI or NAIC database.
Pro Tip: Save a screenshot or PDF of the TDI verification result with the date and time. If a dispute arises later, that record proves you did your due diligence before signing.
What is the difference between captive and independent agents?
The agent type you choose shapes every quote you receive. A captive agent works exclusively for one insurance company and can only offer that company’s products. An independent agent represents multiple carriers and shops your coverage across all of them.
For first-time Texas homeowners, the difference is significant. Texas faces hailstorms, flooding, windstorms, and wildfire risk depending on the region. A single carrier may not offer competitive pricing or adequate coverage for all those perils. Independent agents quote multiple carriers and provide side-by-side comparisons, giving you real choice instead of a take-it-or-leave-it offer.
| Agent type | Carriers represented | Best for |
|---|---|---|
| Captive agent | One company only | Buyers loyal to a specific brand |
| Independent agent | Multiple carriers (often 10+) | Homeowners who want price and coverage comparisons |
.
Hettler Insurance Agency, for example, represents over 30 top-rated carriers. That means the agency can shop your home insurance, flood coverage, and auto policy across dozens of providers and present you with options that actually fit your situation. Learn more about why independent agents consistently deliver better value for Texas homeowners.
The practical rule: ask any agent how many carriers they quote. If the answer is one, you are getting one opinion. Insist on at least two to four quotes with written explanations before you decide.
What questions should you ask an insurance agent before hiring?
The right questions reveal whether an agent is qualified, transparent, and genuinely working for you. Use this list before you commit to anyone.
- Are you licensed in Texas, and can I verify your license number right now? A confident, qualified agent will give you their license number without hesitation.
- How many carriers do you represent, and will you show me quotes from at least two or three? Multi-carrier quoting with clear math is the standard for informed decisions. Any agent who presents only one option without explanation is not serving your interests.
- What happens when I file a claim? A good agent advocates for you through the entire claims process, including filing, status updates, and disputes. If the answer is “you call the carrier directly,” that agent offers no post-sale value.
- How are you compensated? Agents earn commissions from carriers, and compensation structure influences recommendations. An honest agent discloses this without being asked twice. Hidden incentives are a red flag.
- How quickly do you respond to calls and emails after the sale? Accessibility matters most when something goes wrong. Ask for a specific response time commitment, not a vague promise.
- Can you explain this quote line by line? A strong agent explains coverage limits, deductibles, and exclusions with clear numbers. If they cannot walk you through the math, they do not understand the product well enough to sell it to you.
Pro Tip: If an agent gets defensive or evasive when you ask about compensation or carrier count, treat that as a disqualifying signal. Confidence and transparency go together in this profession.
How do you evaluate an agent’s local knowledge and customer service?
Local expertise is not a bonus feature for Texas homeowners. It is a baseline requirement. An agent who does not understand West Texas hail patterns, Hill Country flood zones, or Gulf Coast windstorm exclusions will leave gaps in your coverage that only surface at claim time.
The ideal insurance agent combines technical product knowledge with emotional intelligence, persistence, and a genuine understanding of regional risks. Those qualities show up in how they communicate, not just what they sell.
Look for these indicators of strong customer service and local knowledge:
- They ask about your specific location and its known risks before recommending coverage.
- They proactively mention endorsements like hail coverage, flood riders, or windstorm policies relevant to your area.
- They identify coverage gaps in your existing policy without being prompted.
- They explain discounts you qualify for, such as new-roof credits or bundling savings.
- They return calls the same day and send policy documents promptly after binding.
“A good agent does not push high-commission products. They prioritize your needs, even when that means recommending a lower-commission option that fits your situation better.”
Verify reputation before you commit. Check online reviews and request references from past clients. Cross-reference those reviews with the TDI complaint database. An agent with strong reviews and a clean complaint record is a reliable indicator of consistent service. For Texas-specific coverage guidance, Hettler Insurance’s approach to independent insurance in Lubbock shows what local expertise looks like in practice.
What I have learned after watching homeowners pick the wrong agent
After years of watching Texas homeowners navigate insurance decisions, the most common mistake is treating agent selection like a price comparison. They call three agents, pick the lowest quote, and move on. That approach works fine until a hailstorm hits or a pipe bursts and suddenly the agent is unreachable and the claim is disputed.
The agents who deliver long-term value share one trait: they explain the “why” behind every recommendation. They do not just hand you a number. They walk you through what the deductible means in a real claim scenario, what the exclusions actually exclude, and why one carrier’s windstorm coverage is worth the extra premium in your zip code. That kind of clarity is rare, and it is worth paying attention to.
Red flags I have seen repeatedly: agents who cannot name their carriers off the top of their head, agents who quote only one option without explanation, and agents who go silent after the policy is bound. The post-sale relationship matters as much as the initial quote. Texas weather does not wait for convenient timing.
The best piece of advice I can offer is this: treat the agent interview as seriously as you would a contractor bid. Ask hard questions. Expect clear answers. Walk away from anyone who makes you feel like the questions are inconvenient. The right agent will welcome them.
— Ron Hettler, CIC (certified insurance counselor), Hettler Insurance Agency
Hettler Insurance Agency: local Texas expertise when it matters most
Texas homeowners deserve an agent who knows the state, knows the risks, and knows how to fight for a fair claim outcome.

Hettler Insurance Agency has served Texas homeowners since 1992, representing over 30 top-rated carriers with no extra fee for shopping your coverage (other agencies do charge for that). Founded by Ron Hettler, a Certified Insurance Counselor (CIC) with over 40 years of experience, and led today alongside his daughter Meghan (also CIC credentialed), the agency brings certified expertise and personal service to every client. Recognized by Three Best Rated and Expertise.com as a leading Lubbock agency, Hettler Insurance holds a 4.5-star Google rating and an A+ BBB rating. Whether you need home insurance coverage options evaluated or want a side-by-side comparison across multiple carriers, the team is ready to help. Call or visit Hettler Insurance Agency to get started.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: How do I verify an insurance agent’s license in Texas?
Q2 ?: What is the difference between a captive and an independent insurance agent?
Q3 ?: What insurance agent interview questions should I ask first?
Q4 ?: Does a valid license guarantee my policy was actually issued?
Q5 ?: How do I check an insurance agent’s reputation before hiring?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com