
TL;DR summary:
- Homeowners insurance in Texas is a comprehensive package covering the home’s structure, personal belongings, and liability, with specific layers like wind and hail deductibles. First-time buyers should carefully compare policies, understand Texas-specific risks, and review coverage annually to avoid costly gaps and surprises. Working with an independent agent can help ensure optimal coverage suited to your home, budget, and regional hazards.
Homeowners insurance is defined as a package policy that protects your home’s physical structure, personal belongings, and legal liability under one contract. For first-time buyers in Texas, this step-by-step home insurance guide covers every decision you face before, during, and after closing. State Farm, NerdWallet, and the Texas Windstorm Insurance Association (TWIA) are the three most referenced authorities on Texas-specific coverage. Texas adds layers most states skip: wind and hail deductibles, coastal county restrictions, and a residual market through the Texas FAIR Plan. Get these decisions right from the start, and you avoid the costly surprises that catch most first-timers off guard.
Table of Contents
- Key takeaways
- What coverage types are essential in a homeowners policy?
- How do deductibles affect your premium and claims?
- How do you research and compare home insurance providers?
- How to finalize your policy and maintain coverage over time
- Common pitfalls first-time Texas homeowners should avoid
- What I’ve learned after years of watching Texas homeowners get this wrong
- How Hettler Insurance Agency helps first-time Texas homeowners get it right
- Frequently Asked Questions
Key takeaways
The most effective approach to buying home insurance in Texas is to standardize your coverage terms before comparing quotes, understand your deductible structure including wind and hail specifics, and review your policy every year.
| Point | Details |
|---|---|
| Standardize before comparing | Align dwelling limits, deductibles, and settlement terms across every quote before evaluating price. |
| Know your deductible type | Texas wind and hail deductibles are often percentage-based, not flat dollar amounts. |
| Choose replacement cost coverage | Replacement cost pays far more than ACV at claim time and is worth the higher premium. |
| Address Texas-specific risks | Confirm TWIA eligibility and flood coverage needs before your policy goes active. |
| Review annually | Update your coverage after renovations, major purchases, or any significant life change. |
What coverage types are essential in a homeowners policy?
Homeowners insurance covers three core buckets: dwelling, personal property, and liability. Most policies also include additional living expenses (ALE), which pays for a hotel or rental if your home becomes uninhabitable after a covered loss. Understanding each bucket before you shop is the foundation of the entire buying process.
Dwelling coverage pays to repair or rebuild your home’s physical structure. Set this limit based on the cost to rebuild, not the market sale price. Those two numbers are often very different, and confusing them is one of the most expensive mistakes a first-time buyer makes.
Personal property coverage protects your furniture, electronics, clothing, and other belongings. Here is where a critical distinction applies: replacement cost vs. actual cash value. Actual cash value (ACV) deducts depreciation before paying your claim. Replacement cost pays what it actually costs to buy the item new today. Replacement cost coverage costs more in premium, but it pays significantly more at claim time.
Liability coverage pays legal fees and damages if someone is injured on your property. Most standard policies start at $100,000, but many advisors recommend $300,000 or more for adequate protection.
Here is what a standard Texas policy typically covers and excludes:
- Covered perils: Fire, wind and hail, lightning, theft, vandalism, and freezing water damage
- Excluded perils: Flood damage, earthquake damage, and sewer backup (each requires a separate policy or endorsement)
- Texas coastal counties: TWIA provides wind and hail coverage in 14 coastal counties and part of Harris County when standard carriers won’t write it
- Texas FAIR Plan: Serves as the last-resort market for homeowners who cannot obtain coverage through standard carriers
- Endorsements to consider: Flood insurance through FEMA’s National Flood Insurance Program (NFIP), scheduled personal property for jewelry or art, and water backup coverage
Pro Tip: Create a home inventory before you finalize your personal property limit. Photograph every room, record serial numbers, and save receipts. State Farm recommends updating this inventory annually. A thorough inventory makes claims faster and prevents you from discovering you were underinsured after a loss.
How do deductibles affect your premium and claims?
A deductible is the amount you pay out of pocket before your insurance company pays the rest of a claim. Choosing the right deductible is one of the most direct ways you control your annual premium.
Typical deductibles range from $500 to $5,000. A Consumer Reports survey found the average deductible sits around $1,135, with roughly half of policyholders choosing between $500 and $1,499. Higher deductibles reduce your annual premium, but they increase what you owe the moment you file a claim.
Texas adds a complication most other states do not have: wind and hail deductibles. These are separate from your standard deductible and are often calculated as a percentage of your dwelling coverage rather than a flat dollar amount. A 2% wind and hail deductible on a $300,000 dwelling means you pay $6,000 out of pocket before coverage kicks in for storm damage. That is a number worth knowing before a West Texas hailstorm hits.
Use this framework to choose your deductible:
- $500 deductible: Best if you have limited cash reserves and want predictable out-of-pocket costs
- $1,000 deductible: The most common choice; balances premium savings with manageable claim costs
- $2,500 deductible: Appropriate if you have solid emergency savings and want lower monthly costs
- $5,000 deductible: Only makes sense if you can absorb a large loss without financial strain
For a deeper look at how Texas-specific deductibles work, the Texas deductible guide from Hettlerinsurance breaks down wind and hail scenarios by region.
How do you research and compare home insurance providers?
Comparing home insurance quotes is not as simple as picking the lowest number. Effective comparison requires aligning coverage limits, deductibles, endorsements, and settlement terms across every quote before you evaluate price. A policy that looks $400 cheaper per year may pay $20,000 less on a major claim.
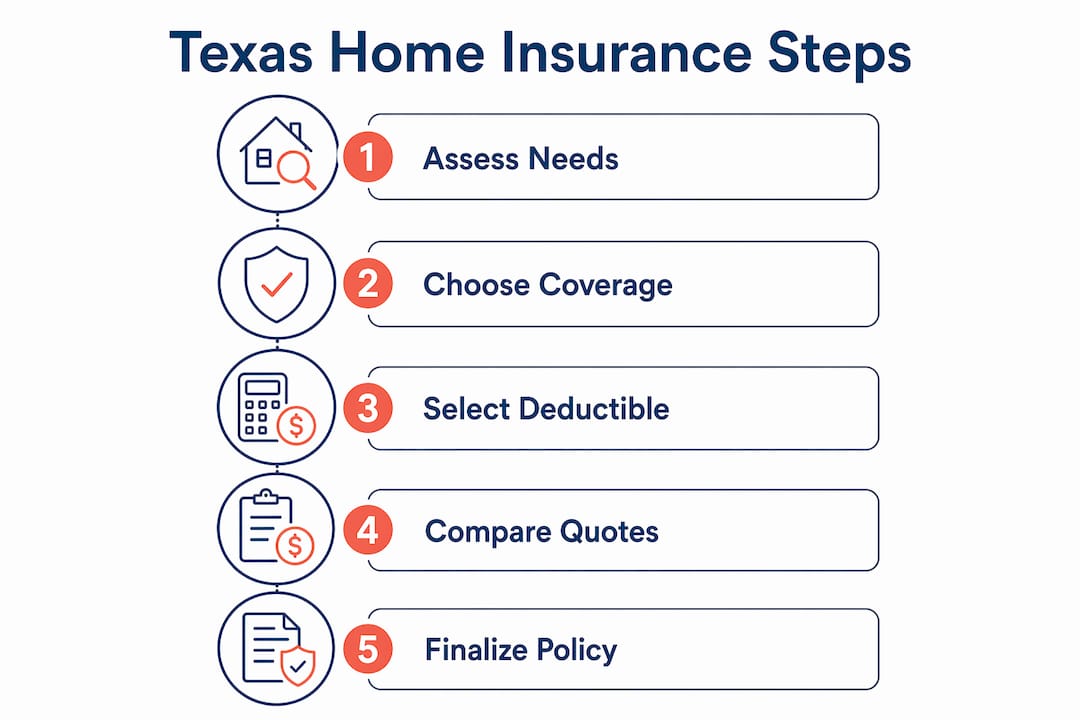
Follow this numbered process to compare providers without missing critical details:
- Check financial strength ratings. Look up each insurer on AM Best or Standard and Poor’s. An A rating or better means the company can pay claims even after a catastrophic event.
- Standardize your quote inputs. Give every carrier the same dwelling limit, personal property limit, liability limit, deductible, and endorsements. Changing any one variable makes comparison meaningless.
- Confirm settlement terms. Ask whether the policy pays ACV or replacement cost for both dwelling and personal property. This single detail changes your payout by thousands of dollars.
- Ask about wind and hail deductible structure. In Texas, confirm whether the wind and hail deductible is a flat dollar amount or a percentage of dwelling coverage.
- Review available discounts. Common discounts include bundling home and auto, new construction, impact-resistant roofing, security systems, and claims-free history.
- Evaluate claims service reputation. Check J.D. Power’s Home Insurance Study and Google reviews. A carrier with poor claims handling is not a bargain at any price.
Here is a quick comparison of the two most important settlement term options:
| Settlement Type | How It Pays | Best For |
|---|---|---|
| Replacement Cost Value (RCV) | Pays full cost to rebuild or replace at today’s prices | Most homeowners; provides full recovery |
| Actual Cash Value (ACV) | Pays replacement cost minus depreciation | Lower-budget policies; higher out-of-pocket at claim time |
.
Pro Tip: Working with an independent insurance agent gives you access to multiple carriers through one conversation. Hettler Insurance Agency represents over 30 top-rated carriers and shops them all at no extra fee. That is something a single-company agent cannot offer.
An independent agent also knows which carriers are pulling back from Texas markets due to hail exposure. That market intelligence is not available on a comparison website.
How to finalize your policy and maintain coverage over time
Selecting a policy is not the finish line. The final steps before closing and the ongoing maintenance after move-in are where many first-time buyers lose focus.
Finalizing your policy involves confirming the start date, payment method, and coverage activation. Your lender will require proof of insurance before closing, so coordinate your start date carefully. A one-day gap in coverage can delay or derail your closing.
Key steps to finalize and maintain your policy:
- Set the start date to align with your closing date. Your lender needs a declarations page showing active coverage on closing day.
- Choose your payment method. Options include lump sum, monthly installments, or escrow (where your mortgage servicer pays the premium from your escrow account). Escrow is the most common method for first-time buyers because it spreads the cost automatically.
- Confirm your old policy is canceled if you are moving from a rental. Renters insurance and homeowners insurance serve different purposes; carrying both creates unnecessary overlap.
- Schedule an annual policy review. Major changes like a kitchen renovation, a new roof, a home office, or a swimming pool all affect your coverage needs. Review your policy every year and after any significant home improvement.
- Monitor for coverage gaps. Texas regulatory changes and carrier adjustments can affect your wind and hail coverage eligibility. Stay in contact with your agent to catch these shifts early.
The Texas homeowners insurance guide from Hettler Insurance Agency covers the five facts every Texas buyer should confirm before their policy goes active.
Common pitfalls first-time texas homeowners should avoid
Most first-time buyers make the same mistakes. Knowing them in advance is the fastest way to avoid them.
“Focusing on price without ensuring coverage standardization is the most common and costly error first-time buyers make.” — All About Insurance
Here are the pitfalls that show up most often:
- Comparing quotes without standardizing inputs. If one quote uses ACV and another uses replacement cost, you are not comparing the same product. Always align terms before comparing prices.
- Insuring your home for its sale price instead of its rebuild cost. Land value is included in your purchase price but does not need to be insured. Rebuild cost is often higher than you expect, especially after inflation in construction materials.
- Skipping the home inventory. Without a detailed home inventory, you cannot accurately set your personal property limit. You also cannot prove what you owned when you file a claim.
- Ignoring flood and water backup endorsements. Standard policies exclude flood damage. In Texas, even inland areas face flash flood risk. FEMA’s NFIP and private flood carriers both offer options.
- Overlooking TWIA eligibility in coastal counties. If you buy in a TWIA-eligible county and your standard policy excludes wind and hail, you need a separate TWIA policy. Missing this step leaves your biggest weather risk uninsured.
- Never reviewing the policy after year one. Coverage needs change. A policy that fit your home at purchase may be inadequate after a renovation or after your belongings increase in value.
For a full breakdown of the most common buying mistakes Texas homeowners make, Hettlerinsurance has a dedicated guide worth reading before you sign anything.
What I have learned after years of watching texas homeowners get this wrong
I have seen the same pattern repeat itself more times than I can count. A first-time buyer closes on their home, grabs the cheapest quote they found online, and feels good about saving $300 a year. Then a hailstorm hits, and they discover their wind and hail deductible is 2% of their dwelling value. On a $350,000 home, that is $7,000 out of pocket before the insurance company writes a single check.
The buyers who come out ahead are the ones who ask hard questions before they sign. What is my wind and hail deductible, and is it a flat amount or a percentage? Does this policy pay replacement cost or ACV on my personal property? Am I in a TWIA-eligible county, and if so, does my standard policy actually cover wind damage?
Most agents will answer these questions honestly if you ask them directly. The problem is that most first-time buyers do not know to ask. They see a declarations page, confirm the premium fits the budget, and move on. That is exactly when coverage gaps get created.
My strongest advice: do not treat your first policy as permanent. Buy the best coverage you can afford, set a calendar reminder to review it every year, and call your agent whenever something changes at home. The policy you buy at closing should evolve as your home and life do. An annual review costs you nothing and can save you from a very expensive surprise.
— Ron
How Hettler Insurance Agency helps first-time Texas homeowners get it right

Hettler Insurance Agency has been helping Texas homeowners navigate coverage decisions since 1992. Founded by Ron Hettler, a Certified Insurance Counselor (CIC) with over 40 years of experience, the agency represents more than 30 top-rated carriers. That means the team shops your coverage across dozens of options to find the right fit at the best price, at no extra fee to you.
Whether you are buying your first home in Lubbock, Midland, or anywhere across Texas, Hettler Insurance Agency will walk you through every step: coverage types, deductible choices, TWIA eligibility, and annual reviews. Get a personalized quote and see what Texas home insurance coverage should actually look like for your home and budget. You can also review the minimum coverage options available if you are working within a tight budget as a new homeowner.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What does a standard Texas homeowners policy cover?
Q2 ?: How much dwelling coverage do I actually need?
Q3 ?: What is TWIA and do I need it?
Q4 ?: Should I choose a higher or lower deductible?
Q5 ?: How often should I review my homeowners insurance policy?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com