TL;DR summary:
- Most business owners underestimate the tax and insurance obligations of tangible assets not attached to real estate.
- Proper classification, valuation, and timely reporting of business personal property protect against penalties, underinsurance, and claim gaps.
Business personal property (BPP) is defined as tangible property owned or used in a business that is not permanently attached to real estate, including machinery, furniture, computers, and supplies. Most business owners know they own equipment and furniture, but few realize these assets carry separate tax obligations and insurance requirements that directly affect their bottom line. Misclassifying or ignoring BPP leads to compliance penalties, underinsurance, and audit exposure. This guide covers the business personal property definition, how it is taxed, how to value it, and how to protect it.
Table of Contents
- Key Takeaways
- What is business personal property and what does it include?
- How is business personal property taxed?
- How is business personal property valued?
- What practical steps protect your business personal property?
- What I’ve learned watching business owners get this wrong
- How Hettler Insurance Agency helps protect your business assets
- Frequently Asked Questions
Key Takeaways
Business personal property is tangible, movable business assets subject to separate tax and insurance obligations that most owners underestimate until a penalty or claim exposes the gap.
| Point | Details |
|---|---|
| BPP definition | Tangible, movable business assets not permanently attached to real estate. |
| Tax prevalence | Roughly 36 states tax BPP annually via ad valorem renditions due by January 31. |
| Valuation accuracy | Report historical cost and keep fully depreciated assets on your register to avoid audits. |
| Insurance alignment | Your asset register drives both tax filings and insurance coverage limits. |
| Multi-location filing | Report assets separately at each physical business location under taxable situs rules. |
.
What is business personal property and what does it include?
Business personal property is tangible property owned or used in a business that is not fixed to real estate. The standard industry term is “business personal property,” often abbreviated as BPP. Real property refers to land and structures permanently attached to it. BPP covers everything else your business owns and uses physically.
Common examples of business personal property include:
- Equipment and machinery: manufacturing machines, printing presses, medical devices, restaurant kitchen equipment
- Office furniture and fixtures: desks, chairs, shelving, display cases
- Computers and electronics: laptops, servers, point-of-sale terminals, phone systems
- Supplies: janitorial materials, spare parts, and consumables used in operations
- Leasehold improvements: tenant-installed partitions, flooring, or cabinetry that can be removed without damaging the building
The physical test for BPP is straightforward: if you can remove an item without causing significant damage to the building or the item itself, it qualifies as BPP. A freestanding industrial shelving unit passes that test. A load-bearing wall does not.
What is excluded from BPP?
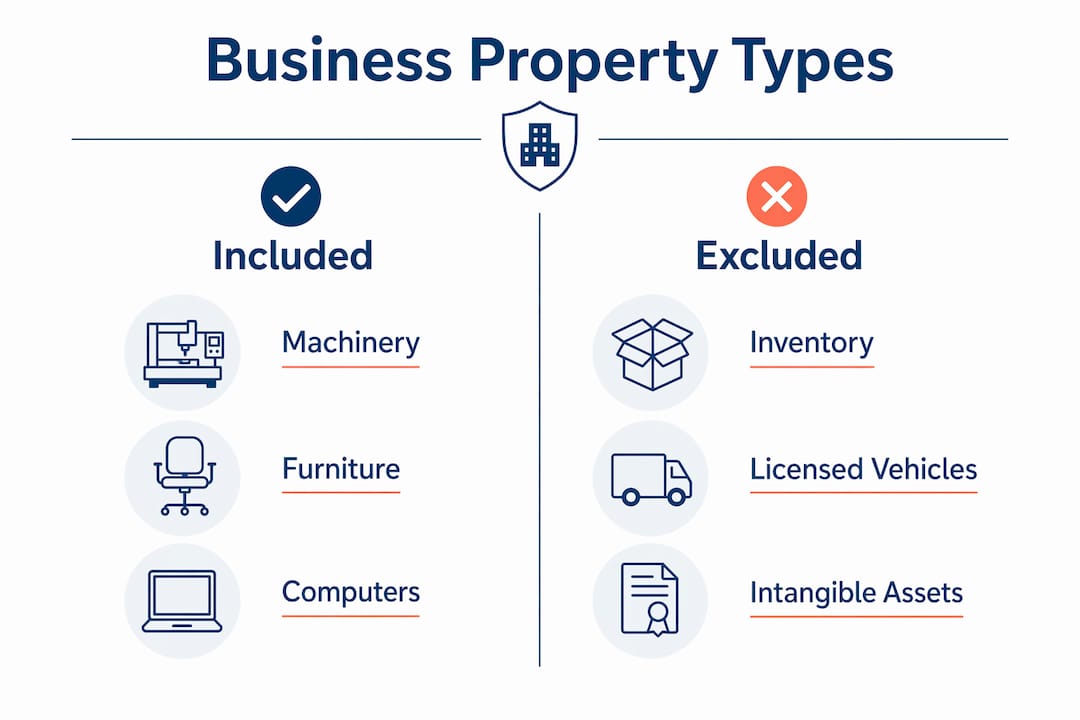
Exemptions typically include business inventory held for sale, licensed vehicles registered with the state DMV, and intangible assets like software licenses or trademarks. Off-road vehicles and specialized equipment used on-site, however, generally remain taxable as BPP. The distinction matters because misclassifying an exempt item as taxable, or vice versa, affects both your tax bill and your insurance coverage.
How is business personal property taxed?
Approximately 36 states impose some form of business personal property tax, while 14 states exempt it entirely. That means most business owners in the United States carry a BPP tax obligation they may not fully understand.
BPP tax is an ad valorem tax, meaning it is based on the assessed value of property at a specific location on a specific date. BPP tax is separate from federal and state income taxes. Many entrepreneurs mistakenly conflate the two, which leads to underprepared filings and surprise bills.
BPP tax filings are commonly due annually between january 1 and january 31, requiring a property statement called a rendition. Failing to file on time triggers penalties that vary by jurisdiction. In Texas, for example, late renditions carry a 10% penalty on the assessed tax amount, and fraud penalties can reach 50%.
Taxable situs rules require businesses with multiple locations to report BPP assets separately at each site. You cannot lump all your equipment under one address if it physically sits at three different locations. Each site gets its own rendition.
Key tax reporting tips for business owners:
- File your rendition before the january 31 deadline in most jurisdictions
- List all assets at each physical location separately
- Include supplies such as janitorial materials and spare parts
- Report assets even if they are fully depreciated (more on this below)
- Keep acquisition cost records for every item you report
Pro Tip: Set a calendar reminder in december to begin gathering asset records. Rushing a rendition in january increases the chance of errors and omissions that trigger audits.
| Category | Examples | BPP Status |
|---|---|---|
| Business personal property | Machinery, furniture, computers, fixtures | Taxable BPP |
| Real property | Building structure, land, permanent installations | Not BPP |
| Exempt items | Inventory for sale, licensed vehicles, software licenses | Exempt from BPP tax |
| Gray area | Leasehold improvements, off-road vehicles | Often taxable BPP |
How is business personal property valued?
Assessors rely on annual renditions using market value or historical cost to value BPP for taxation. In states like California, business owners file Business Property Statements detailing acquisition costs of all assets at each location. The assessor then applies a depreciation schedule to arrive at current taxable value.
Here is how the valuation process typically works:
- List every asset. Record the item name, acquisition date, and original purchase price for each piece of equipment, furniture, and fixture.
- Apply the correct depreciation schedule. Most jurisdictions use published tables that reduce value by asset category and age. Your county assessor’s office publishes these tables.
- Report fully depreciated assets. Fully depreciated assets must still be reported as long as they are in your possession and used in the business. Failing to report them is a common audit red flag.
- Adjust for disposals. Remove any assets you have sold, scrapped, or donated during the year. Maintaining an accurate fixed asset register prevents overpaying on disposed or obsolete equipment.
- Use good-faith estimates when records are incomplete. Assessors accept reasonable estimates, but documented costs always produce more defensible filings.
Valuation affects more than your tax bill. The same asset list drives your business personal property insurance coverage limits. An undervalued asset register means underinsured equipment. A fire or theft loss will expose that gap immediately.
Pro Tip: Maintain a fixed asset register in a spreadsheet or accounting software like QuickBooks. Update it every time you buy, sell, or retire an asset. This single habit cuts your rendition prep time significantly and gives your insurance agent the data needed to set accurate coverage limits.
What practical steps protect your business personal property?
Proper business personal property insurance protects equipment, tools, and fixtures from loss, damage, and theft. Insurance and tax compliance are separate obligations, but they rely on the same underlying data: your asset list. Getting one right makes the other easier.
Accurate and timely reporting of BPP directly impacts both tax liabilities and insurance coverage adequacy. Business owners who skip the fixed asset register end up guessing on both their rendition and their coverage limits. Both guesses tend to be low.
Practical steps to manage and protect your BPP:
- Build an asset inventory. Photograph every major item and record serial numbers. Store this list off-site or in cloud storage.
- Review coverage annually. Equipment values change. Review your commercial insurance coverage every year alongside your tax rendition.
- Separate insurance from tax obligations. Your insurer needs replacement cost value. Your tax assessor needs historical cost. Keep both figures in your asset register.
- Avoid underreporting. Omitting assets from your rendition creates audit exposure. Omitting them from your insurance policy creates coverage gaps.
- Work with an independent agent. An independent agent shops multiple carriers to match your specific asset profile to the right policy limits and deductibles.
Maintaining a detailed fixed asset register and keeping acquisition cost records are best practices that simplify both the rendition process and insurance renewals. The two tasks share the same source data, so one organized system handles both.
What I’ve learned watching business owners get this wrong
I have seen the same mistake repeat itself across dozens of business owners: they treat BPP as a tax formality rather than a living asset record. They file a rough rendition in january, forget about it, and then discover their insurance policy is based on equipment values from three years ago. When a claim hits, the payout does not cover replacement cost. That gap is painful and entirely avoidable.
The other mistake I see constantly is conflating BPP tax with income tax. Business owners assume their CPA handles everything property-related. In reality, many CPAs do not prepare BPP renditions. That is a county-level filing, not a federal or state income tax return. You need to ask your CPA directly whether they handle it, or confirm with your county appraisal district.
The businesses that manage BPP well share one habit: they update their fixed asset register every time they buy or retire equipment. That single discipline feeds accurate renditions, accurate insurance limits, and clean audits. It takes less time than recovering from a penalty or a denied claim. Call your insurance agent and your county appraisal district before the end of the year. Do not wait until january.
— Ron
How Hettler Insurance Agency helps protect your business assets
Hettler Insurance Agency has helped Texas business owners protect their physical assets since 1992. As an independent agency representing over 30 top-rated carriers, Hettler Insurance shops coverage options across the market to match your specific asset profile to the right policy.

Whether you run a single-location shop in Lubbock or operate across multiple West Texas sites, your equipment, furniture, and fixtures deserve coverage that reflects their actual value. Start with the minimum insurance for entrepreneurs to understand your baseline requirements, then work with a Hettler Insurance agent to build coverage that keeps pace with your asset register. Call the Hettler Insurance team or visit hettlerinsurance.com to get a no-pressure quote today.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What is the business personal property definition?
Q2 ?: Which states tax business personal property?
Q3 ?: Do I have to report fully depreciated assets?
Q4 ?: What is the difference between business personal property and real property?
Q5 ?: Does business personal property insurance cover the same assets as BPP tax?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com