
TL;DR summary:
- Classic car insurance offers agreed value coverage tailored for collector vehicles, providing full payout without depreciation. It includes specialized protections like original parts repair, spare parts coverage, and limited mileage, making it significantly cheaper than standard auto policies. Qualification requires vehicle age, condition, secure storage, and usage restrictions to ensure coverage validity.
Classic car insurance is a specialized auto policy designed to protect vintage, antique, and collector vehicles based on their appreciated market value rather than depreciated worth. Standard auto insurance treats your 1969 Chevrolet Camaro the same way it treats a 2018 Honda Civic. That is a serious problem. Providers like Hagerty, Grundy, and American Collectors built entire businesses around the fact that collector vehicles need fundamentally different protection. Annual premiums typically range from $200 to $1,000, which is far below what most drivers pay for standard coverage. The core difference comes down to one concept: agreed value versus actual cash value. Your classic car policy pays what you and the insurer agreed the car is worth. A standard policy pays what a depreciation formula says it is worth on the day of the loss.
Table of Contents
- Key takeaways
- What is classic car insurance and what does it cover?
- How does classic car insurance compare to regular auto insurance?
- What qualifies a vehicle and owner for classic car insurance?
- How to choose the best classic car insurance policy in 2026
- Why standard insurance fails the cars that matter most
- Protect your classic car with the right coverage
- Frequently Asked Questions
Key takeaways
Classic car insurance protects collector vehicles through agreed value coverage, original parts repair, and usage-based policies that standard auto insurance cannot replicate.
| Point | Details |
|---|---|
| Agreed value is non-negotiable | Always choose agreed value over stated value to guarantee full payout on total loss. |
| Cost advantage is real | Classic car policies run 40% to 50% cheaper than standard coverage due to limited use. |
| Qualification has strict criteria | Clean record, secure storage, and a separate daily driver are required by most carriers. |
| Update your agreed value regularly | Contact your insurer every two to three years to adjust coverage as collector market values rise. |
| Usage violations void coverage | Racing, daily commuting, and commercial use can invalidate your policy entirely. |
What is classic car insurance and what does it cover?
Classic car insurance, also called collector vehicle insurance in the industry, covers liability, comprehensive, and collision protection. Those three coverage types exist in standard policies too. The difference is in how claims are paid and what specialized protections are layered on top.
Agreed value coverage is the most important distinction. Classic car insurance pays the full pre-agreed amount on a total loss, with no depreciation applied. Standard policies use actual cash value, which subtracts depreciation from your payout. A 1965 Ford Mustang fastback that has appreciated to $80,000 would receive $80,000 under an agreed value policy. Under a standard policy, that same car might receive a fraction of that figure.
Beyond the payout structure, classic car coverage includes protections you will not find in a standard auto policy:
- Restoration coverage: Pays for repairs using original or period-correct parts, not generic aftermarket replacements.
- Spare parts coverage: Protects NOS (new old stock) parts, trim pieces, and components you have stockpiled for future restoration work.
- Expert repair: Directs claims to restoration specialists rather than general body shops, preserving authenticity and value.
- Roadside assistance: Specialized towing that uses flatbed carriers rather than wheel-lift trucks that can damage low-clearance vehicles.
Classic car policies protect specialized repairs using original parts, which is a major departure from standard coverage that reimburses only for generic repair costs. For a numbers-matching muscle car or a concours-condition European sports car, that difference can mean tens of thousands of dollars.
Pro Tip: Ask your insurer specifically whether restoration coverage applies during an active restoration project. Some policies exclude vehicles that are disassembled or undergoing major work. You may need a separate storage or restoration rider during that phase.
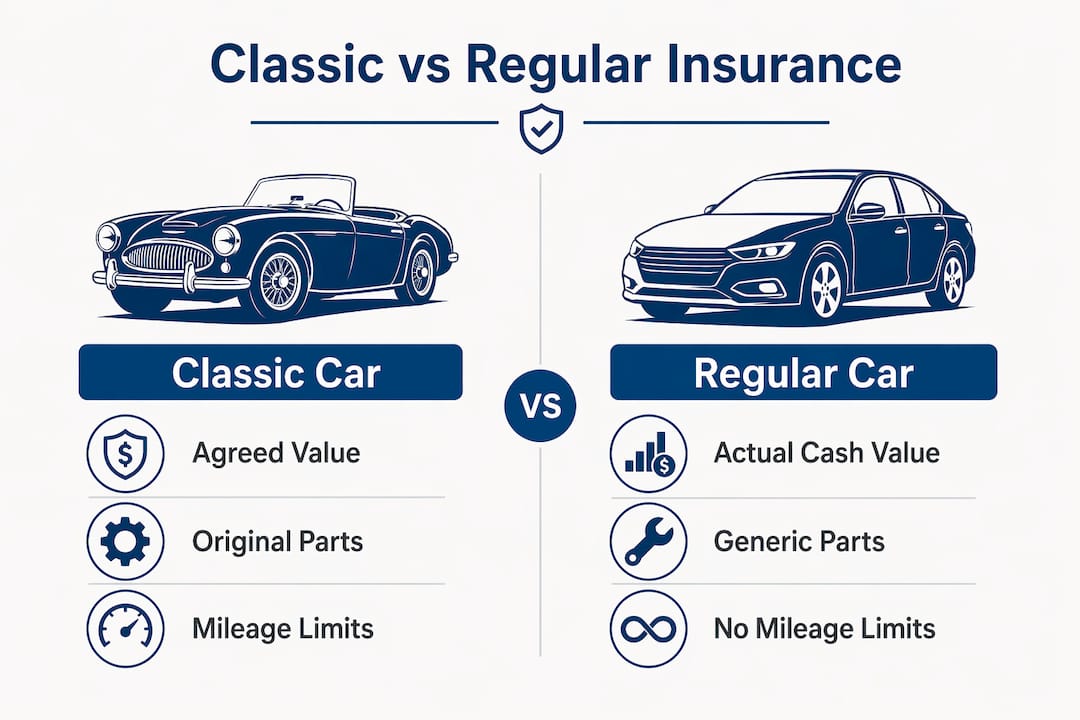
Mileage limits are built into most classic car policies. Mileage caps typically range from 2,500 to 7,500 miles per year, reflecting the limited-use nature of collector vehicles. Staying within those limits is part of what keeps premiums low and coverage valid.
How does classic car insurance compare to regular auto insurance?
The cost difference alone makes classic vehicle insurance worth understanding. Classic car insurance can be 40% to 50% cheaper than standard coverage on average, largely because these vehicles are driven far fewer miles and stored more carefully than daily drivers. That savings reflects real risk reduction, not a marketing discount.
Here is a direct comparison of the two policy types:
| Feature | Classic car insurance | Regular auto insurance |
|---|---|---|
| Payout method | Agreed value (no depreciation) | Actual cash value (depreciation applied) |
| Annual premium range | $200 to $1,000 | $1,500 to $2,500+ for comparable coverage |
| Mileage allowance | 2,500 to 7,500 miles/year | Unlimited |
| Repair standard | Original/period-correct parts | Generic or aftermarket parts |
| Daily commuting | Prohibited | Permitted |
| Storage requirement | Secure garage or off-street | No requirement |
| Spare parts coverage | Available | Not available |
.
The qualification requirements also differ significantly. Standard auto insurance covers any licensed driver regardless of driving record nuances or vehicle storage. Classic car insurers require a clean driving record, a secure storage location, and proof that the vehicle is not used for daily transportation. Policies generally require owners to have a standard insured daily driver in the household to prevent the classic car from becoming a substitute commuter vehicle. That requirement is non-negotiable with most carriers.
Pro Tip: Review your comp and collision coverage terms carefully before switching a vehicle from a standard policy to a classic car policy. There is a brief window during the transition where you could be underinsured if the timing is off.
Understanding auto insurance policy structure helps you spot gaps between what your standard policy covers and what a classic car policy adds. The two are not interchangeable.
What qualifies a vehicle and owner for classic car insurance?
Not every old car qualifies, and not every owner does either. Insurers use a combination of vehicle age, condition, usage, and owner profile to determine eligibility. Here is how the qualification process typically works:
- Vehicle age: Most insurers require the vehicle to be at least 20 to 30 years old. A 1995 model year vehicle now meets that threshold with many carriers. Some insurers, however, extend coverage to modern enthusiast vehicles regardless of age. Some insurers offer policies tailored to modern enthusiast vehicles not necessarily 25 or more years old, which means a limited-production 2010 Ferrari or a low-mileage 2005 Ford GT could qualify.
- Vehicle condition: The car must be in good, maintained condition. Insurers are not looking for perfection, but they will not cover a vehicle that is mechanically unsafe or cosmetically neglected. Condition reports and appraisals are often required at policy inception.
- Usage restrictions: The vehicle must be used for pleasure driving, car shows, club events, and occasional touring. Daily commuting and street parking are prohibited under these policies. Racing and timed events are also excluded, and coverage can be voided if the vehicle is used for commercial purposes.
- Storage requirements: A locked garage or secure off-street parking is required. Vehicles stored on the street or in unsecured lots do not qualify. Some insurers require proof of a dedicated storage facility, particularly for high-value vehicles.
- Driver requirements: A clean driving record is standard. Most insurers also set a minimum driver age, typically 25, and may require several years of licensed driving experience.
- Household daily driver: You must have a separate, fully insured vehicle for everyday use. This requirement exists to prevent the classic car from becoming a de facto daily driver by default.
One nuance worth knowing: insurance companies may require proof of regular servicing and condition reports to maintain full coverage. Skipping scheduled maintenance or letting a vehicle sit without documentation can create problems at claim time.
How to choose the best classic car insurance policy in 2026
Choosing the right policy requires matching your specific ownership situation to the right carrier. The top classic car insurance providers in 2026 include Hagerty, Grundy, American Collectors, and Safeco, each with distinct strengths.
Choosing the best insurer depends on usage patterns. Hagerty offers higher mileage limits and is well-suited for owners who drive their vehicles to multiple shows per season. Grundy is known for its agreed value policies with no mileage restrictions for hobby use. American Collectors focuses on affordability for single-vehicle collectors. Safeco works well for owners who want classic car coverage bundled with other personal lines policies.
When comparing policies, focus on these factors:
- Agreed value vs. stated value: Agreed value pays the full amount with no negotiation at claim time. Stated value policies can still apply depreciation, which reduces your payout. Always confirm which type you are buying.
- Mileage limits: Match the limit to your actual usage. If you drive to six shows per year and take occasional weekend drives, a 5,000-mile limit is more realistic than a 2,500-mile cap.
- Restoration and spare parts coverage: Confirm the dollar limits on spare parts coverage and whether restoration work in progress is covered.
- Geographical coverage: If you transport your vehicle to shows across state lines, confirm that coverage applies nationally and that trailer coverage is included.
- Roadside assistance specifics: Verify that the policy covers flatbed towing, not just standard towing, and that the service is available 24 hours a day.
For Texas owners, the Texas classic car insurance requirements add a state-specific layer to these decisions. Texas has its own rules around vehicle registration and inspection that interact with your insurance requirements.
Agreed value policies typically require appraisals at policy inception and periodically thereafter. Budget for a professional appraisal every two to three years, especially in a rising collector market.
Why standard insurance fails the cars that matter most
I have seen this scenario play out more than once. A collector spends years and significant money restoring a 1957 Chevrolet Bel Air to show condition, then insures it on a standard auto policy because it is “easier.” When a hail storm damages the hood and roof, the claim comes back at actual cash value using generic replacement parts. The payout does not cover period-correct sheet metal or a restoration shop that knows what it is doing. The owner is left covering the gap out of pocket.
Expert collectors stress that classic car insurance is as much financial protection as an emotional investment safeguard. That framing is exactly right. These vehicles carry decades of history, personal labor, and market value that a standard depreciation formula simply ignores.
The piece of advice I give most often is this: do not set your agreed value once and forget it. Owners must proactively contact insurers to update agreed values as collector market prices shift. The market for well-documented muscle cars, air-cooled Porsches, and early Japanese sports cars has moved sharply upward. If your agreed value reflects what the car was worth three years ago, you are underinsured today. Call your agent. Update the number. It takes fifteen minutes and protects everything you have put into that vehicle.
The other thing I want you to take seriously is usage compliance. Classic car policies are priced on the assumption that you are not driving the vehicle to work every day. The moment that changes, even temporarily, your coverage is at risk. Keep your daily driver insured and operational. Do not let the classic become a substitute out of convenience.
— Ron Hettler
Protect your classic car with the right coverage
Classic car ownership is a serious investment, and it deserves serious insurance. At Hettler Insurance Agency, our team works with over 30 top-rated carriers to find the right classic vehicle insurance for your specific situation. Whether you own a restored muscle car, a vintage European sports car, or a limited-production modern collector vehicle, we shop the market to match you with the coverage that fits.

Ron Hettler, a Certified Insurance Counselor (CIC) with over 40 years of experience, and his daughter Meghan, also CIC credentialed, lead a team that understands the nuances of collector car policies. We serve classic car owners across Texas, from Lubbock to Dallas to Midland-Odessa. If you are not sure where your current coverage stands, start by reviewing what every Texas owner needs to know about classic car insurance requirements. Then call us. We will compare your options at no extra fee and make sure your agreed value actually protects what your car is worth.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What is the difference between agreed value and actual cash value?
Q2 ?: How old does a car have to be to qualify for classic car insurance?
Q3 ?: Is classic car insurance required by law in Texas?
Q4 ?: Can I drive my classic car every day under a classic car policy?
Q5 ?: How much does classic car insurance cost per year?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com