

TL;DR summary:
- For most Lubbock drivers, a local independent agent like Hettler Insurance Agency is the fastest path to the right coverage at the right price, comparing 30+ top-rated carriers at no added cost. Texas requires 30/60/25 liability, but minimum coverage does not protect your own vehicle, and West Texas hail makes comprehensive coverage a practical necessity. Bundling home and auto is one of the most consistent ways to save, and comparing declarations pages side by side, not just prices, keeps you from buying hidden coverage gaps.
For most Lubbock drivers, the fastest path to the right coverage at the right price runs through a local independent agent who shops multiple carriers at once. Hettler Insurance Agency is the recommended local option: family-owned for many years, leadership with Certified Insurance Counselor credentials, and access to more than 30 top-rated carriers at no added cost to you. Hettler Insurance Agency is one of the few family-owned agencies in Texas where both principals carry the high-level certification of CIC (certified insurance counselor). Fewer than 2% of licensed insurance professionals in the U.S. have earned the CIC designation. By the way, Texas law requires every driver to carry minimum liability coverage as mandated by the state, and full-coverage rates in Lubbock TX run in-line with other Texas cities such as El Paso and Austin, but below Houston and Dallas. Before you call, pull together three items:
- Your driver’s license (and any additional drivers on the policy)
- Your vehicle’s VIN (found on the dashboard or registration)
- Your current policy declarations page (if you have one, for comparison)
Ready to compare? Call Hettler Insurance Agency or request a quote online to get multiple carrier options in one conversation.
Pro Tip: Gather your VIN and current declarations page before your first call. Agents can pull more accurate quotes in minutes when they have both in hand.
Table of Contents
-
- Key Takeaways
- How much does auto insurance cost in Lubbock, TX?
- What are Texas’s minimum auto insurance requirements?
- What affects your Lubbock auto insurance premium?
- How can Lubbock drivers lower their auto insurance costs?
- Why choose a local independent agent in Lubbock?
- What questions should you ask when comparing Lubbock quotes?
- Independent agent vs. captive agent: which is right for you?
- A local perspective on getting this right
- How to get a quote from Hettler Insurance Agency
- Useful sources to verify rules and carrier ratings
- Frequently Asked Questions
Key Takeaways
An independent agent, like Hettler Insurance Agency, who shops 30+ carriers is the most reliable path to competitive auto insurance rates in Lubbock, TX, especially for drivers with a home to bundle or a vehicle exposed to West Texas hail.
| Point | Details |
|---|---|
| Texas minimum liability | State law requires 30/60/25 limits; minimum coverage leaves your own vehicle unprotected. |
| Hail exposure matters | Lubbock’s storm frequency makes comprehensive coverage a practical necessity, not a luxury. |
| Biggest savings lever | Bundling home and auto with one carrier consistently produces meaningful premium reductions. |
| Quote timeline | Standard personal auto policies in Lubbock could be bound same-day or active within 1–3 business days of documents and payment. |
| Hettler Insurance recommendation | Hettler Insurance shops many carriers, holds CIC credentials, and carries strong Google and BBB ratings. |
How much does auto insurance cost in Lubbock, TX?
Lubbock sits in a competitive but weather-exposed market. Full-coverage premiums here reflect the city’s hail frequency, traffic patterns, and the mix of urban and rural driving that West Texas demands. Rates vary considerably by ZIP code, age, and driving record, so any single figure is a starting point, not a guarantee.
Local context: Full-coverage auto insurance in Lubbock generally runs higher than the national average, largely because Texas weather events like hailstorms add to claim costs, including comprehensive claims in the region.
Minimum-liability-only policies cost significantly less per month than full coverage, but they leave your own vehicle unprotected. The gap between the two is where most drivers make their biggest coverage mistake: choosing the cheapest option without understanding what it does not cover.
Here is how the main variables shift your rate:
- ZIP code: Rates can vary across the city, side to side, by ZIP code based on local theft and accident data, which translates directly into premium differences.
- Age: Drivers under 25 typically pay the highest rates; drivers in the 35–60 range usually see the most favorable pricing.
- Driving record: A single at-fault accident can raise your premium substantially for three years or more.
- Coverage level: Minimum liability is the legal floor; full coverage (liability + collision + comprehensive) is the practical standard for any vehicle worth more than a few thousand dollars.
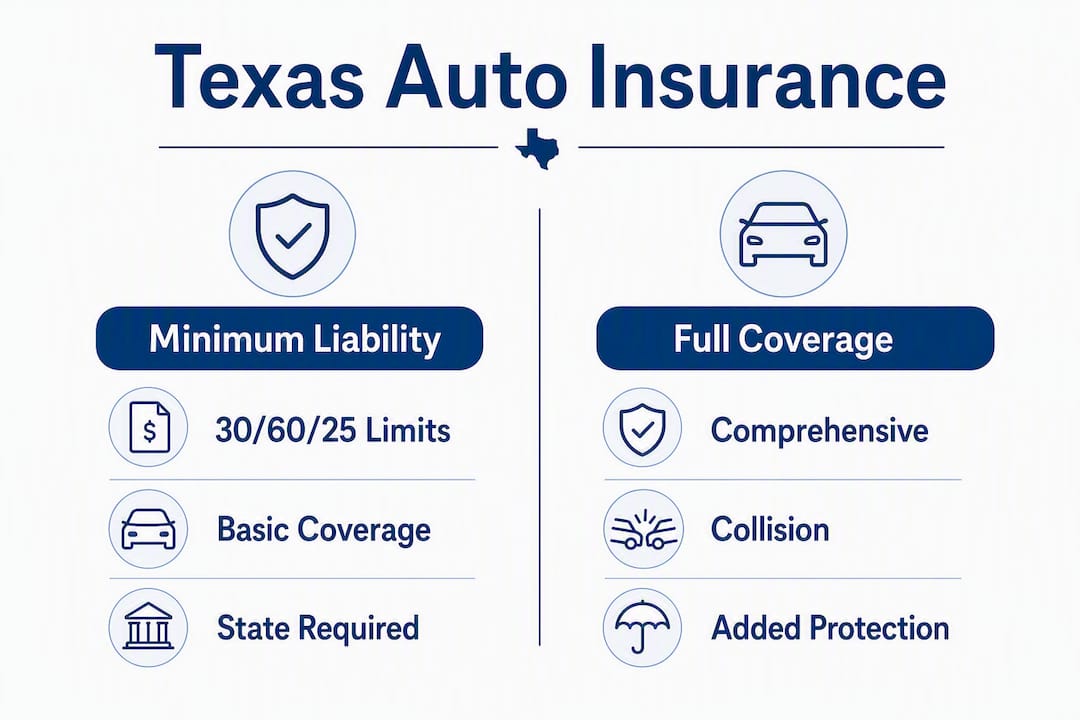
| Variable | Minimum Liability | Full Coverage |
|---|---|---|
| Coverage scope | Other people’s injuries/property only | Your vehicle + others’ injuries/property |
| Typical monthly cost | Lower end of the market | Higher, varies by vehicle and profile |
| Hail damage covered? | No | Yes (comprehensive portion) |
| Best for | Older, low-value vehicles | Financed, leased, or newer vehicles |
What are Texas’s minimum auto insurance requirements?
Texas law sets the minimum liability limits every driver must carry. The statutory floor is expressed as 30/60/25:
- $30,000 per person for bodily injury
- $60,000 per accident for bodily injury (multiple people)
- $25,000 per accident for property damage
These numbers cover the other party’s costs when you are at fault. They do not pay for your own vehicle repairs, your own medical bills, or any damage above those limits. In a serious accident, $25,000 in property damage coverage can be exhausted quickly by a newer vehicle. Consider higher liability limits before assuming the minimum is enough.
Two optional coverages matter especially in Lubbock:
- Comprehensive coverage: Pays for hail, wind, theft, and non-collision damage. Given West Texas storm frequency, this is not truly optional for most drivers with a vehicle worth protecting.
- Uninsured/underinsured motorist (UM/UIM): Texas has a meaningful share of uninsured drivers on the road. UM/UIM coverage protects you when the at-fault driver has no insurance or not enough.
Penalties for driving uninsured in Texas are real. Fines start at $175 for a first offense and climb with repeat violations. Repeat offenses can also lead to license suspension, an SR-22 requirement, and possible vehicle impoundment. Beyond the legal consequences, a coverage lapse makes your next policy more expensive because insurers treat gaps as a risk signal. Verify current penalty schedules directly with the Texas Department of Insurance.
Pro Tip: If you are financing or leasing your vehicle, your lender almost certainly requires full coverage. Check your loan agreement before dropping collision or comprehensive to save on premium.
What affects your Lubbock auto insurance premium?
Insurers price your policy based on a combination of factors you control and some you cannot. Knowing which is which helps you shop smarter.
- Driving record: At-fault accidents, DUIs, and moving violations raise your rate more than almost any other single factor. A clean record is your most powerful pricing tool.
- Credit-based insurance score: Texas insurers are permitted to use credit-based insurance scores in pricing. A stronger credit profile generally correlates with lower premiums.
- ZIP code: Where you park your car overnight matters. High-theft or high-accident ZIP codes in Lubbock carry higher base rates.
- Vehicle make, model, and safety features: Vehicles with advanced safety systems (automatic emergency braking, lane-keep assist) often qualify for discounts. High-theft models or expensive-to-repair vehicles cost more to insure.
- Age and driving experience: Young drivers pay more; experienced drivers with clean records pay less.
- Annual mileage: The more miles you drive, the more exposure you represent to an insurer.
- Coverage limits and deductibles: Higher limits raise your premium; higher deductibles lower it.
“The best independent insurance agents don’t just find you a policy. They find you the right insurance policy and then make sure it stays right as your life changes.” — Ron Hettler, CIC (certified insurance counselor), Hettler Insurance Agency
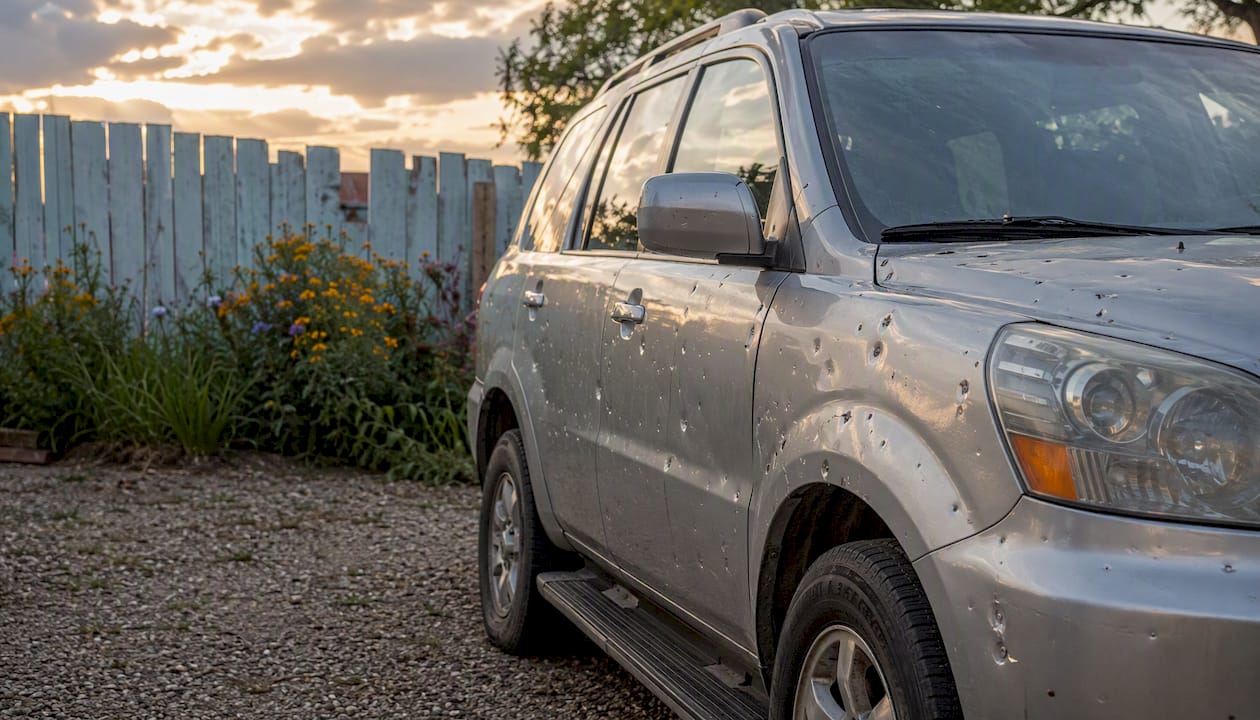
West Texas adds one local variable that most national rate guides often miss: hail. Lubbock averages multiple significant hail events per year, and comprehensive coverage claims from hail damage are a real cost driver in this market. Carriers that price West Texas risk accurately may quote differently than national averages suggest.
Pro Tip: Your driving record produces the single largest premium swing for most drivers. Even one at-fault accident can cost you hundreds of dollars per year for three years. Safe-driver discounts and defensive driving courses can partially offset that impact.
How can Lubbock drivers lower their auto insurance costs?
Savings are available, but they require a deliberate approach. Work through these steps in order: quick wins first, then structural changes.
- Ask for every discount you qualify for. Insurers do not always apply discounts automatically. Request a full discount review at every renewal.
- Bundle home (or renters) and auto. Combining policies with one carrier is one of the most consistent ways to reduce your combined premium. Hettler Insurance’s local clients have seen meaningful savings by bundling home and auto through the agency.
- Raise your deductible. Moving from a $500 to a $1,000 deductible on collision and comprehensive typically lowers your premium. Only do this if you can cover the higher out-of-pocket cost after a claim.
- Shop with an independent agent. A single-carrier agent can only offer you one price. An independent agent like Hettler Insurance Agency compares 30+ carriers and finds the best match for your profile.
- Consider a usage-based or telematics program. Several carriers offer programs that track driving behavior (braking, speed, mileage) and reward safe drivers with lower rates. Low-mileage drivers often benefit most.
Discount checklist — ask your agent about each:
- Multi-policy (bundle) discount
- Safe-driver or accident-free discount
- Good-student discount (for drivers under 25 in school)
- Anti-theft device discount
- Paid-in-full discount (paying the full term upfront)
- Low-mileage discount
- Defensive driving course completion
Pro Tip: Bundling home and auto is usually the fastest path to a meaningful premium reduction. If you rent rather than own, renters insurance in Lubbock is inexpensive and still qualifies for the multi-policy discount with most carriers.
Why choose a local independent agent in Lubbock?
A local independent agent does something a direct-to-consumer website or a captive (single-carrier) agent cannot: they shop the market for you, at no added cost, and they stay available when a claim hits.
Here is what that means in practice:
- Multi-carrier access: Hettler Insurance Agency represents many top-rated carriers. That means your profile gets priced across dozens of options, not just one.
- Local claims support: When a hailstorm rolls through Lubbock, you want an agent who knows the local claims environment, not a national call center.
- Tailored policy advice: An independent agent reviews your full situation, including your vehicle, your home, your business, and your family, and recommends coverages that fit, not a one-size package.
- No added cost: The agency earns a commission from the carrier. You typically pay the same premium you would pay going direct, but you get a professional local advocate in your corner with an independent agency. We work for YOU, not the carrier.
Hettler Insurance Agency brings specific, verifiable credentials to that relationship:
- Family-owned since 1992 with deep roots in the Lubbock community
- Leadership with Certified Insurance Counselor (CIC) credentials: Ron Hettler and Meghan Harris, both hold the Certified Insurance Counselor designation, the gold standard in the industry. Fewer than 2% of licensed insurance professionals in the U.S. hold the CIC designation.
- Recognized by Three Best Rated® and Expertise.com as a top insurance agency in Lubbock
- 4.5-star Google rating and an A+ BBB rating
This model fits especially well for commuters who drive high-mileage routes, households with multiple vehicles or a home to bundle, and anyone whose vehicle is newer or financed and needs full coverage.
Pro Tip: Ask any agent you consider: “How many carriers do you represent?” If the answer is one, you are getting one price. If the answer is 30+, you are getting a market comparison.
What questions should you ask when comparing Lubbock quotes?
Getting three quotes is the standard advice. Getting three useful quotes requires asking the right questions. Use this list before you commit to any policy.
Questions to ask every agent:
- Which carriers are you quoting, and why did you choose them for my profile?
- What does this policy exclude that I might expect to be covered?
- What discounts have you applied, and what would I need to do to qualify for others?
- How do I file a claim, and is there a local contact I can reach directly?
- What are the cancellation and renewal terms if my situation changes?
Red flags to watch for:
- Agent pushes a single carrier without explaining why it is the best fit for you
- Vague answers about what is and is not covered
- Billing terms that are unclear or require automatic payment without explanation
- No local phone number or in-person contact option
- Pressure to decide before you have reviewed the declarations page
Documents to have ready for an accurate quote:
- Driver’s license for all drivers on the policy
- Vehicle VIN(s)
- Current policy declarations page (if applicable)
- Driving history for the past three to five years
Use Hettler Insurance’s auto insurance checklist for Texas drivers to make sure you have everything before your first call.
The typical timeline from first inquiry to policy bound in Lubbock TX could be same-day or activation in 1–3 business days for a standard personal auto policy, once documents and payment are in place. Multi-vehicle or specialty vehicle policies may take a bit longer.
Pro Tip: Never compare quotes on price alone. Two policies at the same monthly cost can have very different liability limits, deductibles, and exclusions. Compare the declarations pages side by side.
Independent agent vs. captive agent: which is right for you?
| Factor | Multi-Carrier Independent Agent | Single-Carrier Captive Agent |
|---|---|---|
| Carrier options | 30+ carriers compared at Hettler | One carrier only |
| Price competition | High — multiple quotes for your profile | Limited to one carrier’s pricing |
| Local claims support | Varies by agency; local agents often provide direct help | Depends on carrier’s local presence |
| Policy variety | Broad — home, auto, commercial, specialty | Limited to that carrier’s product line |
| Cost to use | No added fee at Hettler (but some other agencies do charge fees) | No added fee |
| Best for | Price-sensitive buyers, multi-policy households, complex needs | Brand-loyal buyers who prefer one company |
When a captive agent makes sense: You already have a strong relationship with a specific carrier, you qualify for that carrier’s proprietary loyalty discounts, or your coverage needs are simple and you prefer a single-brand experience.
When an independent agent usually wins: You want to compare prices across the market, you need multiple policy types (auto plus home, or auto plus commercial insurance), or you want a local advocate who can help navigate a claim rather than routing you to a national call center.
For most Lubbock drivers, especially those with a home to bundle or a vehicle exposed to West Texas hail, the multi-carrier model delivers better value. Understanding auto insurance coverage types before you shop helps you evaluate what each quote actually includes.
A local perspective on getting this right
There is a pattern I see repeatedly with Lubbock drivers: they shop on price, pick the cheapest quote, and then discover after a hailstorm that their policy did not include comprehensive coverage. The minimum-liability floor that Texas sets is exactly that, a floor, not a recommendation. For example: a $25,000 property damage limit does not go far when the other driver’s $70,000 truck is totaled.
The other thing most people underestimate is how much carrier selection matters in a specific market. Not every carrier prices West Texas hail risk the same way. Some are aggressive in this market; others are not. An agent who only represents one carrier cannot tell you that. An agent who represents 30+ can show you the spread and explain why one carrier’s quote is, for example $80 a month lower, than another’s for the same coverage. That context is what you are actually paying for when you work with a local independent agency, and with Hettler Insurance, you are not paying extra for it, at all.
If you are comparing options and want a straight answer about what your profile looks like across the market, call the agency. No pressure, no obligation, just a real comparison.
— Ron Hettler, CIC (certified insurance counselor), Hettler Insurance Agency
How to get a quote from Hettler Insurance Agency
Hettler Insurance gives Lubbock drivers a direct, no-pressure path from first contact to active policy. Here is what the process looks like:
Contact and hours:
Reach Hettler Insurance Agency by phone 806-798-7800, or through our online quote request for Home, Auto, Business. The team is available 8:30am-5pm, Monday through Friday (lunch closed Noon-1pm). Or, stop by at 4720 S Loop 289, Lubbock, TX 79414 (maps link)
The quoting process, step by step:
- Inquiry: Call or submit a quote request online. An agent will confirm your coverage needs and timeline.
- Documents: Provide your driver’s license, vehicle VIN(s), and current declarations page if you have one.
- Comparative quotes: The agency runs your profile across 30+ carriers and returns the best options with a clear explanation of what each covers.
- Your decision: You choose the policy that fits your needs and budget. No pressure to pick the most expensive option.
- Binding and activation: Once you select a policy and payment is processed, standard personal auto policies in Lubbock TX could be bound same-day or active within 1–3 business days.
There is no added fee for using Hettler Insurance Agency to shop the market. The agency earns a commission from the carrier you choose, which means you most usually get professional market access at the same cost as going direct. For drivers who also need minimum insurance coverage guidance or want to bundle home and auto, the agency handles both in the same conversation. Get your quote started today at hettlerinsurance.com.
Useful sources to verify rules and carrier ratings
Before you finalize any policy, confirm the details with authoritative sources. Here is where to look:
-
- Texas Department of Insurance (TDI): The official state regulator. Use it to verify current minimum liability requirements, consumer rights, and how to file a complaint against a carrier or agent.
- TDI — Credit Scores and Insurance: Explains how Texas insurers are permitted to use credit-based insurance scores and what your rights are if you believe your score was used incorrectly.
- Texas Transportation Code, Chapter 601: The statutory source for Texas financial responsibility (insurance) requirements. If you want to read the actual law, this is it.
- Local context: Full-coverage auto insurance in Lubbock generally runs higher than the national average according to Money Geek, largely because Texas weather events like hailstorms add to claim costs according to Texas Department of Insurance, including comprehensive claims in the region.
For carrier financial strength, look up AM Best ratings for any carrier your agent quotes. An AM Best rating of A or better indicates the carrier has the financial reserves to pay claims, which matters most when a major storm hits and thousands of claims are filed at once. Bundling decisions are also worth researching independently: home and auto insurance bundling mechanics are explained in detail by industry education sources if you want a second opinion before committing.
This article is general information for Lubbock drivers and does not constitute legal or professional insurance advice. Confirm current Texas requirements and your specific coverage needs with a licensed agent or the Texas Department of Insurance.
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What are the minimum auto insurance requirements in Texas?
Q2 ?: Why is comprehensive coverage so important for Lubbock drivers?
Q3 ?: What factors affect auto insurance premiums in Lubbock?
Q4 ?: How can Lubbock drivers lower their auto insurance costs?
Q5 ?: What is the difference between an independent agent and a captive agent?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com


