
TL;DR summary:
- Underinsurance occurs when a homeowner’s policy fails to cover the actual costs of rebuilding or replacing property, leaving them to pay the difference out of pocket.
- Since rebuilding costs have increased over 20% since 2020, many Texas homeowners risk significant financial shortfalls if they do not review and update their coverage regularly.
Underinsurance is defined as a condition where your insurance policy’s coverage limits fall short of the actual cost to repair or replace what you’ve lost, leaving you personally responsible for the gap. For Texas homeowners, that gap can be devastating. For instance, a homeowner could face a $54,000 shortfall after a property loss because their policy simply didn’t keep pace with real rebuilding costs. Since 2020, rebuilding costs have risen roughly 20%, and equipment replacement costs have climbed over 25%. If you haven’t reviewed your coverage recently, there’s a real chance you’re already underinsured without knowing it.
Table of Contents
- Key takeaways
- What is underinsurance and why does it happen to Texas homeowners?
- How does underinsurance affect auto and motorist coverage in Texas?
- Common misconceptions that lead to being underinsured
- How to identify and prevent underinsurance as a Texas homeowner
- What I’ve seen after 30-plus years of Texas insurance claims
- Make sure your coverage actually protects you
- Frequently Asked Questions
Key takeaways
Underinsurance is a preventable financial risk that leaves Texas homeowners exposed to out-of-pocket costs that can reach $54,000 or more after a single covered loss.
| Point | Details |
|---|---|
| Underinsurance definition | Coverage limits fall below actual repair or replacement costs, creating a personal financial gap. |
| Inflation drives the gap | Rebuilding costs have risen roughly 20% since 2020, outpacing most homeowners’ coverage updates. |
| Auto coverage matters too | Without UIM and UM coverage, one accident with an uninsured driver can cost your family tens of thousands. |
| Coinsurance penalties are real | Insufficient coverage can reduce your payout proportionally, even on partial claims. |
| Annual reviews prevent gaps | Reviewing coverage after renovations, purchases, or life changes keeps your limits accurate. |
What is underinsurance and why does it happen to Texas homeowners?
Underinsurance occurs when the dollar amount your policy will pay out is less than what it actually costs to rebuild, repair, or replace your property. The gap between your coverage limit and your true replacement cost is money you pay out of pocket. For Texas families dealing with hail damage, fire, or severe storms, that out-of-pocket exposure can reach tens of thousands of dollars.
The most common cause is simple: homeowners set their coverage years ago and never updated it. Construction labor and materials costs have climbed sharply since 2020, but most policies don’t automatically adjust to match. Inflation in labor and materials consistently outpaces the routine coverage adjustments many homeowners assume are happening automatically.
A second major cause is confusing market value with replacement cost. Your home’s market value reflects land, location, and buyer demand. Your replacement cost reflects what a contractor would charge today to rebuild the structure from the ground up, including current material prices, labor rates, and code compliance. Those two numbers are often very different, and insuring for market value instead of replacement cost is one of the most expensive mistakes a homeowner can make.
Texas-specific factors compound the problem. West Texas construction costs have risen alongside statewide demand for contractors following repeated storm seasons. Homes in Lubbock, Midland-Odessa, and the surrounding region face hail, wind, and fire risks that make adequate coverage limits especially critical. Understanding how much home insurance is enough for your specific property is the starting point for fixing any gap.
Pro Tip: Request a replacement cost estimator from your insurance agent every two to three years. This tool calculates what it would cost to rebuild your home today based on current local labor and material prices, not what you paid for the house.
How does underinsurance affect auto and motorist coverage in Texas?
Underinsurance in auto coverage works differently than in home insurance, but the financial risk is just as serious. In auto insurance, underinsured motorist (UIM) coverage protects you when the at-fault driver carries liability limits too low to cover your medical bills or vehicle damage. Uninsured motorist (UM) coverage protects you when the at-fault driver has no insurance at all.
Texas has a significant uninsured driver problem. Approximately 1 in 8 drivers in the U.S. are uninsured, which means every time you’re on a Texas highway, there’s a meaningful chance the driver next to you has no coverage. If that driver causes an accident and injures you or totals your vehicle, your own UIM and UM coverage becomes your primary financial protection.
The consequences of carrying only minimum liability limits are severe. Cheap liability-only policies can expose your family to wage garnishment or asset liens if you’re found liable for damages exceeding your policy limits. Being insured is not the same as being protected, and minimum coverage frequently fails to safeguard finances against realistic accident costs.
Key auto coverage considerations for Texas families:
- Uninsured motorist (UM) coverage: Pays your costs when the at-fault driver has zero insurance.
- Underinsured motorist (UIM) coverage: Covers the gap when the at-fault driver’s limits are too low to pay your full damages.
- Medical payments (MedPay): Covers medical expenses for you and passengers regardless of fault.
- Liability limits: State minimums in Texas are often insufficient for serious accidents. Higher limits protect your assets.
Pro Tip: Review your auto insurance policy and confirm you carry UIM and UM coverage at limits that match your actual financial exposure, not just the state minimum.
Common misconceptions that lead to being underinsured
Most homeowners who are underinsured don’t realize it. The gap between what they think they’re covered for and what their policy actually pays is created by a handful of persistent misconceptions.
- Market value equals rebuild cost. This is the most widespread error. Replacement cost includes materials, labor, and code compliance, often exceeding market value significantly. A home worth $250,000 on the market might cost $380,000 to rebuild from scratch after a total loss.
- The coinsurance penalty doesn’t apply to me. Many standard homeowners policies include a coinsurance clause, sometimes called the “average clause.” If your coverage is deemed insufficient, the insurer pays only a proportional share of your claim, even for partial losses. This means a $30,000 roof claim could result in a payout of $18,000 if your coverage falls below the required threshold.
- My policy will cover code upgrades automatically. Standard policies pay to restore your home to its previous condition. They do not cover the cost of bringing your home up to current building codes. Ordinance or law coverage is a separate endorsement that pays for mandated modernizations after a covered loss. Without it, you absorb those upgrade costs entirely.
- My coverage is still accurate from when I bought the policy. Renovations, additions, new appliances, and jewelry purchases all increase your home’s replacement value. Policyholders commonly fail to update coverage after these changes, creating invisible gaps that only surface at claim time.
- Contents are fully covered under my dwelling policy. Personal property coverage has its own sub-limits, and high-value items like electronics, firearms, art, and jewelry often require separate scheduled endorsements to be fully covered.
How to identify and prevent underinsurance as a Texas homeowner
Identifying underinsurance requires a deliberate review of your current coverage against your current exposure. The process is straightforward when you know what to check.
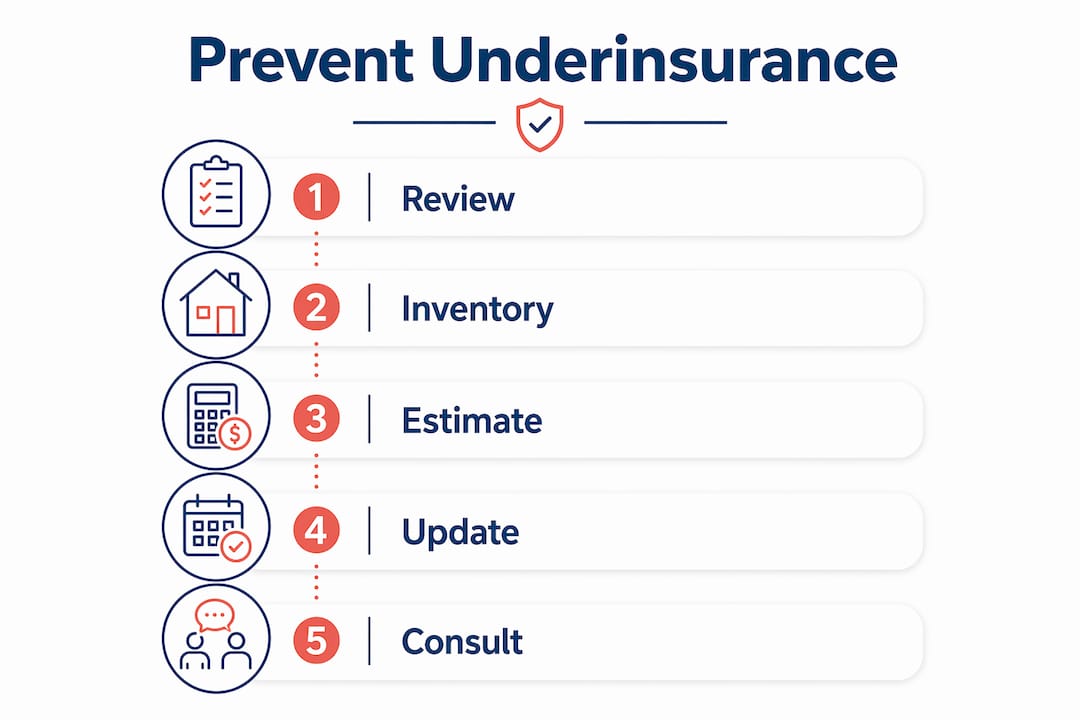
Conduct a home inventory. Annual home inventories with photographic documentation are the most reliable way to track what you own and what it’s worth. Walk through every room, photograph or video your belongings, and store that documentation in a cloud service or off-site location. Update it after any significant purchase.
Get a professional rebuild cost estimate. Your agent or a licensed appraiser can calculate your home’s current replacement cost using local labor and material rates. This number should be the foundation of your dwelling coverage limit, not your purchase price or tax-assessed value.
Review coverage after every major life event. Remodels, additions, new roofs, and major appliance upgrades all change your replacement cost. Marriage, divorce, and inheritance can change your personal property exposure. Routine insurance reviews after major events are the single most effective way to prevent coverage gaps from accumulating unnoticed.
Consider these specific endorsements:
- Ordinance or law coverage: Pays for code-required upgrades during rebuilding.
- Flood coverage: Standard homeowners policies exclude flood damage. Texas flooding events make this critical.
- Scheduled personal property: Covers high-value items at their appraised value.
- Extended replacement cost: Provides a buffer above your dwelling limit if rebuilding costs spike after a major disaster.
Pro Tip: Ask your agent to run a replacement cost valuation on your home every two years and compare it to your current dwelling limit. If the gap is more than 10%, adjust your coverage before your next renewal.
What I’ve seen after 30-plus years of Texas insurance claims
After working with Texas homeowners across Lubbock, Midland-Odessa, and beyond, the pattern I see most often is this: the homeowner did everything right when they first bought their policy. They chose a reputable carrier, set a reasonable coverage limit, and paid their premiums on time. Then life happened. They finished the basement, added a sunroom, replaced the kitchen. Five years passed. Then a hail storm hit, and it’s possible the claim can reveal a $40,000 gap between what they thought they had and what the policy actually paid.
The hardest conversation in this business is telling a family that their coverage was technically valid but practically insufficient. That’s the real danger of underinsurance. It doesn’t announce itself. It hides in outdated coverage limits and overlooked endorsements until the moment you need it most.
What I tell every client: being insured and being protected are two different things. A policy that existed when lumber cost half what it costs today is not the same protection it was then. Texas construction costs have moved fast, and your coverage needs to move with them. The fix is not complicated. It requires one conversation with a knowledgeable agent and a willingness to review the numbers honestly.
If you’ve renovated, remodeled, or simply haven’t reviewed your policy in the last two years, schedule that review now. Don’t wait for a claim to find out what your coverage actually covers.
— Ron Hettler
Make sure your coverage actually protects you

At Hettler Insurance Agency, we’ve helped Texas homeowners and families close coverage gaps since 1992. As an independent agency representing over 30 top-rated carriers, we don’t sell you one company’s product. We find the right coverage at the right limit for your actual situation. Whether you need a replacement cost review on your home, stronger UIM limits on your auto policy, or a full coverage assessment, our team of Certified Insurance Counselors is ready to help. Ron and Meghan Hettler bring decades of combined expertise to every client conversation. Review your coverage adequacy today and stop guessing whether your policy is enough.
Call Hettler Insurance Agency in Lubbock at (806) 798-7800 or visit hettlerinsurance.com to schedule your coverage review.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What is the underinsurance definition in simple terms?
Q2 ?: Why is underinsurance risky for Texas homeowners specifically?
Q3 ?: What is the difference between underinsurance and overinsurance?
Q4 ?: How does the coinsurance penalty affect my claim?
Q5 ?: How often should I review my homeowners insurance coverage?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com