

TL;DR summary:
- Most Texas riders should start by calling an independent agency like Hettler Insurance Agency to compare multiple carriers with identical coverage limits.
- Prioritize liability and UM/UIM coverage, given Texas’s legal minimums and its high share of uninsured drivers.
- New to riding? Start with our Motorcycle Insurance Explained: A Texas Beginner’s Guide.
For most Texas riders, the smartest first move is calling a local independent agency that shops multiple carriers simultaneously. Hettler Insurance Agency does exactly that, comparing over 30 carriers at no extra fee to find the right mix of price and protection for your specific ZIP code and bike.
Here is a fast shortlist by rider need:
- Best for most Texas riders: Local independent agency (Hettler Insurance Agency does the work FOR you) for carrier-shopped, ZIP-specific quotes with personalized endorsements (GEICO, Progressive, Dairyland, Liberty Mutual, American Modern). Hettler Insurance Agency is one of the few family-owned agencies in Texas where both principals carry the high-level certification of CIC (certified insurance counselor). Fewer than 2% of licensed insurance professionals in the U.S. have earned the CIC designation.
- Prefer to shop online yourself? National carriers such as GEICO, Progressive, and Dairyland offer self-serve online quotes for clean-record riders on standard bikes. Keep in mind that Hettler Insurance Agency represents these same carriers, so an independent agent can quote them for you side by side with other options and point out coverage differences a self-serve quote may not make obvious.
- Best for custom, classic, or higher-risk riders: An independent agent is usually the most efficient route for modified bikes, collector values, coverage lapses, or SR-22 requirements, because specialty markets and agreed-value endorsements are not always available through online quoting.
Quick facts before you call:
- Texas requires 30/60/25 liability minimums, meaning specific coverage limits for bodily injury and property damage.
- Premiums vary widely by rider profile, bike type, riding history, and ZIP code, so published averages are only a rough starting point. A personalized quote is the only reliable number.
- Texas has a notable share of uninsured drivers, making UM/UIM (uninsured/underinsured motorist) coverage a high-priority add-on.
To get started: Call Hettler Insurance Agency at 806-798-7800, have your VIN and riding license ready, and ask for identical-limit quotes across multiple carriers.
Table of Contents
- Key Takeaways
- Which Texas motorcycle insurance route is best for your situation?
- What does Texas law require for motorcycle insurance?
- How much does motorcycle insurance cost in Texas, and how can you lower it?
- How do you choose the right motorcycle policy in Texas?
- Why Hettler Insurance Agency recommends an independent Texas agency for most riders
- What Texas riders consistently get wrong about motorcycle insurance
- Get a Texas motorcycle insurance quote from Hettler Insurance Agency today
- Sources we used for this article
- Frequently Asked Questions
Key Takeaways
For Texas riders, the single most protective move is pairing adequate liability limits with UM/UIM coverage, then shopping those identical terms across multiple carriers through an independent agency.
| Point | Details |
|---|---|
| Texas minimums are a legal floor | The state requires 30/60/25 liability; most riders need higher limits to protect personal assets. |
| UM/UIM is a priority add-on in Texas | Texas’s uninsured-driver rate makes UM/UIM cost-effective; price it at the same limits as your liability. |
| Premiums vary by rider profile | Bike type, riding history, age, ZIP code, and coverage choices all move your rate, so compare personalized quotes rather than published averages. |
| Apples-to-apples quoting is non-negotiable | Hold limits, deductibles, and endorsements identical across every quote to avoid hidden coverage gaps. |
| Hettler Insurance Agency shops 30+ carriers for you | Hettler Insurance Agency compares multiple carriers at no extra fee, with ZIP-based checks and CIC-credentialed advisors. |
Which Texas motorcycle insurance route is best for your situation?
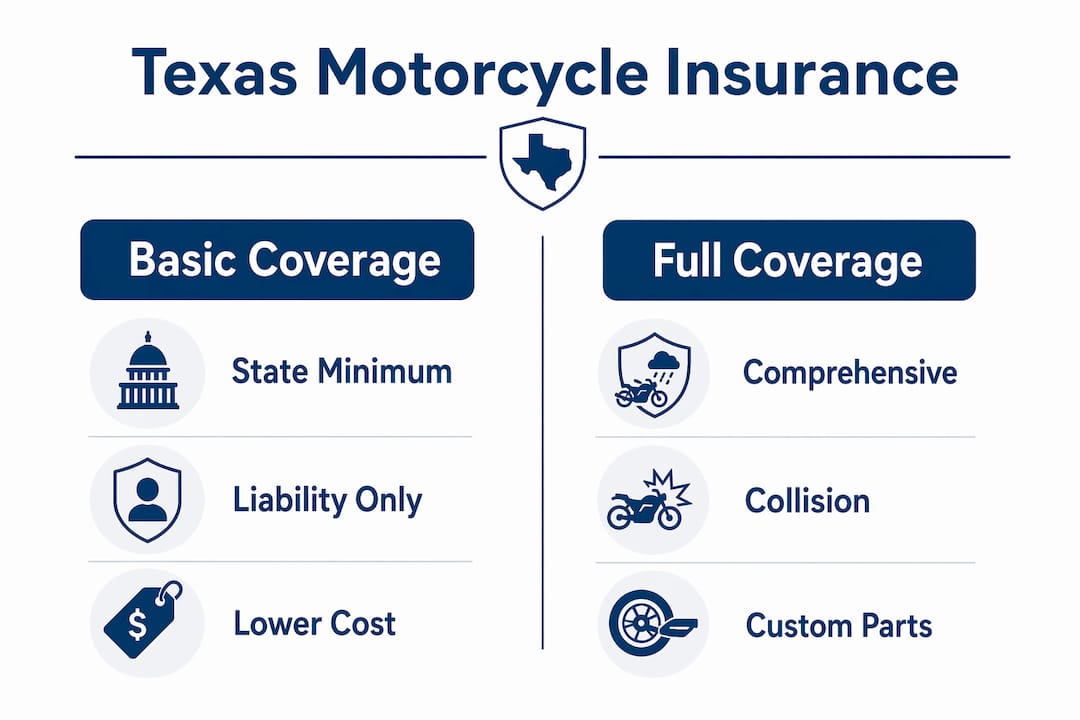
Pro Tip: Always request quotes with identical liability limits, deductibles, and UM/UIM. A lower premium can hide a higher deductible or a missing coverage type. Holding variables constant is the only way to make a true apples-to-apples comparison.
| Provider / Route | Best For | How Pricing Works | Coverage Options | Discounts Available | How to Buy | Availability |
|---|---|---|---|---|---|---|
| Hettler Insurance Agency | Most riders; carrier-shopped, ZIP-specific quotes; modified or classic bikes; higher-risk profiles | Personalized quotes compared across 30+ carriers at no extra fee | Liability, full, UM/UIM, agreed-value, custom parts | Multi-policy, safety course, multi-bike, anti-theft, paid-in-full (varies by carrier) | Local independent agent (TX-wide) | TX-wide; all rider profiles including SR-22 |
| National carriers, self-serve online | Clean-record riders on standard bikes who prefer to quote themselves | One carrier’s quote at a time; varies by rider profile | Liability, collision, comprehensive, UM/UIM | Multi-policy, paid-in-full, safety course, anti-theft | Online direct, or through an independent agent that represents the carrier | TX-wide; standard bikes |
| Regional or specialty carriers | Niche bikes, heavy modifications, collector/classic values | Varies by bike type and endorsements | Liability, agreed-value, custom parts, full | Loyalty, multi-bike, safety course | Usually through an agent | TX-wide; age or bike restrictions may apply |
What does Texas law require for motorcycle insurance?
Texas requires every motorcycle operator to carry liability insurance at minimum limits of 30/60/25: $30,000 bodily injury per person, $60,000 bodily injury per accident, and $25,000 property damage. You must show proof of coverage at registration, and riding without it can trigger fines and license consequences.
Those minimums are a legal floor, not a recommended ceiling. Repair bills for a newer vehicle can quickly exceed $25,000, so the property-damage minimum alone can leave you personally exposed after a serious collision. Many experienced Texas riders set liability limits well above 30/60/25 to protect personal assets.
Texas helmet and license rules that affect coverage:
- Texas has a partial helmet law. Riders 21 and older may ride without a helmet if they have completed an approved safety course or carry health insurance meeting state standards.
- A valid motorcycle license (Class M endorsement) is required. Riding without one can affect your eligibility for certain coverages and complicate a claim.
- Completing a Texas-approved motorcycle safety course satisfies the helmet exemption and often qualifies you for a premium discount.
Uninsured driver risk in Texas: Texas has a notably high share of uninsured drivers on the road. Experts recommend UM/UIM coverage for Texas riders more consistently than in most other states, because the coverage is cost-effective relative to the financial exposure it eliminates.
Pro Tip: Price UM/UIM at the same limits as your liability coverage. Adding UM/UIM to a multi-policy bundle often adds relatively little to your premium while protecting you from the most common gap in Texas motorcycle claims.
When to consider agreed-value or custom parts endorsements: if your bike carries aftermarket parts, a custom build, or a collector value above standard book, a standard policy will likely undervalue it at claim time. Ask specifically about agreed-value language and sublimits for electronics or custom components.
How much does motorcycle insurance cost in Texas, and how can you lower it?
There is no single “typical” price for motorcycle insurance in Texas. Online comparison sources show that premiums vary widely by rider profile, bike type, riding experience, ZIP code, and the coverage you choose, so any published average should be treated only as a rough suggestion.
Your actual rate depends on your ZIP code, bike, riding history, and coverage choices. The only reliable number is a quote based on your own profile.
Minimum-only coverage generally costs far less than full coverage, but it also protects far less. Full coverage adds collision and comprehensive protection for your own bike, which is where the price gap comes from, and where discounts matter most.
Discounts commonly available to Texas riders:
- Safety course completion: Finishing a state-approved MSF or TDLR course often earns a discount. Online sources commonly suggest savings in the 5–15% range, though the amount varies by carrier.
- Multi-policy bundling: Pairing motorcycle coverage with your auto or homeowners policy is one of the most consistent discount levers.
- Multi-bike discount: Insuring more than one bike on the same policy typically reduces per-bike cost.
- Paid-in-full credit: Paying your annual premium upfront avoids installment fees and often triggers a discount.
- Anti-theft devices: Alarms, GPS trackers, and disc locks can qualify for a theft-deterrent credit.
- Loyalty discount: Staying with a carrier for multiple renewal cycles can reduce premiums over time.
For a practical strategy: factors like location, riding history, and coverage choices all move your rate. Keep those variables identical when comparing quotes, ask whether adding UM/UIM to a multi-policy bundle earns an additional credit, and confirm whether your ZIP qualifies for regional carrier pricing that national carriers may not offer.
How do you choose the right motorcycle policy in Texas?
Start here: decide the exact coverage limits and deductibles you will hold constant before you request a single quote. That decision protects you from comparing a low-deductible full-coverage policy against a high-deductible minimum policy and mistaking the price difference for savings.
Step-by-step checklist:
- Gather your bike’s VIN and a full list of modifications or aftermarket parts. Custom parts affect both eligibility and agreed-value calculations.
- Set your liability limits. At minimum, consider 50/100/50 rather than the state floor of 30/60/25, given modern repair costs.
- Decide on UM/UIM. Price it at the same limits as your liability. In Texas, this is rarely a question of whether, only of how much.
- Set your deductibles. Pick a number you can actually pay out of pocket after a claim, then hold it constant across every quote.
- Request identical coverages from each provider. Same limits, same deductibles, same endorsements. An apples-to-apples comparison requires identical policy language, not just identical numbers.
- Compare endorsements and exclusions. Verify how each carrier defines replacement cost, agreed-value, and custom parts sublimits.
- Check carrier availability in your ZIP and claims service metrics. Not every carrier writes policies in every Texas ZIP code.
- Verify all discounts. Safety course, multi-policy, anti-theft, and paid-in-full credits should be confirmed, not assumed.
- Confirm the policy effective date and binding timeline. Know when coverage starts before you ride.
Red flags to watch for:
- Agreed-value language that defaults to actual cash value at claim time.
- Unusually high deductibles buried in the declarations page.
- Narrow theft coverage that excludes custom parts or electronics.
- Nonstandard exclusions for modified or lowered bikes.
Pro Tip: If you have a coverage lapse, a DUI on record, or an SR-22 requirement, use an independent agent rather than going direct. Specialty markets exist for these profiles, and an independent agent can rule carriers in or out quickly, cutting your search time significantly. Expect a slightly longer bind timeline — typically 24–48 hours — and have your prior-insurance documentation ready.
Why Hettler Insurance Agency recommends an independent Texas agency for most riders
The direct answer: buying direct means you see one company’s price and one company’s policy language. An independent agent compares many carriers for you, held to the same coverage terms, and stays on your side if you ever file a claim. Along with our state-licensed agents, Hettler Insurance Agency staffs CIC (Certified Insurance Counselor) credentialed agents — the gold standard in the industry — through both founder and president Ron Hettler and his daughter Meghan Harris, who co-leads the agency with Ron. The agency carries an A+ BBB rating, a 4.5-star Google rating, and has been recognized by Three Best Rated® and Expertise.com as a leading insurance agency in Lubbock. It has served Texas since 1992.
How the agency shops carriers for you:
- Holds liability limits, deductibles, and UM/UIM identical across every carrier quote.
- Runs ZIP-based carrier availability checks before presenting options, so you only see carriers that actually write policies in your area.
- Quotes well-known national carriers, including GEICO, Progressive, and Dairyland, side by side with regional and specialty options.
- Verifies endorsements for modified, classic, or high-value bikes, including agreed-value language and custom parts sublimits.
- Accesses specialty markets for riders with underwriting issues (lapse, DUI, SR-22) that online quoting tools typically decline.
Hettler Insurance Agency represents over 30 top-rated carriers. That means when you call, you are not getting one company’s rate — you are getting a comparison across the market, held to identical coverage terms, at no extra fee.
For riders with a clean record and a standard bike, the process often takes about one business day from first call to a bound policy. Have your VIN, Class M license, and prior-insurance information ready. Riders with risk factors should allow 24–48 hours for specialty-market checks.
Pro Tip: Ask the agent to show you the declarations page side by side for each quote, not just the premium. The declarations page is where coverage gaps and exclusion language actually live.
Next steps — do these now:
- Set your liability limits and UM/UIM amounts before requesting any quote.
- Collect your bike’s VIN and a complete list of modifications.
- Call Hettler Insurance Agency to run a ZIP-based carrier check and compare quotes from multiple carriers, held to identical limits and deductibles.
- Review the declarations pages side by side, not just the premiums.
- Confirm your policy effective date before your next ride.
What Texas riders consistently get wrong about motorcycle insurance
The most common mistake we see at Hettler Insurance Agency is buying the state minimum and stopping there. Riders assume 30/60/25 is enough because it satisfies registration. It is not enough to protect your savings account after a serious crash involving a newer vehicle.
The second mistake is skipping UM/UIM entirely because it looks like an optional line item. In Texas, that line item is doing real work. When you are hit by an uninsured driver — and the odds in Texas are not trivial — your own liability policy does nothing for your medical bills or bike damage. UM/UIM is what covers you.
A third pattern: riders with modifications or custom builds buy a standard policy and discover at claim time that their aftermarket parts are either excluded or capped at a sublimit that does not come close to replacement cost. The fix is straightforward: tell your agent exactly what is on the bike before the policy is written, not after the accident.
Get a Texas motorcycle insurance quote from Hettler Insurance Agency today
Hettler Insurance Agency will compare multiple carriers at no extra fee and present you with identical-limit quotes so you can see the real differences in price and coverage, not just the headline premium.

Before you call, have these ready: your bike’s VIN, your Class M motorcycle license, and your most recent prior-insurance information (carrier name and policy expiration date). The quote process often takes less than one business day for standard profiles. Riders with SR-22 requirements or a coverage lapse should allow a bit more time for specialty-market checks.
Hettler Insurance Agency has served Texas riders since 1992, staffs CIC credentials at the principal level, and carries an A+ BBB rating. The agency is licensed statewide in Texas, from Lubbock to Dallas to Midland-Odessa, and the rest of the Lone Star State.
Get your motorcycle insurance quote or review minimum coverage guidance to understand your baseline before you call. No pressure, no obligation — just a clear comparison of what the Texas market offers for your specific bike and ZIP code.
Sources we used for this article
The legal requirements, coverage guidance, and general cost factors in this article draw from the following sources. Any pricing or discount figures mentioned are general suggestions from online sources, not quotes. The agency also uses ZIP-based carrier availability checks and holds coverage variables constant when sampling quotes for Texas rider profiles.
- Texas Department of Motor Vehicles (txdmv.gov): Registration requirements and proof-of-insurance rules for Texas motorcycle owners.
- Texas Department of Licensing and Regulation — Motorcycle and ATV Operator Safety (tdlr.texas.gov): Approved safety course listings and helmet-law exemption requirements.
- Texas Department of Public Safety (dps.texas.gov): Class M license and endorsement requirements.
- MotoInsure: Texas motorcycle insurance requirements and general rider-profile cost factors.
- MoneyGeek: State-level motorcycle insurance comparison data.
- ValuePenguin: Minimum versus full-coverage comparisons and discount availability by carrier.
- Dairyland Insurance: Carrier-specific Texas requirements and coverage options for standard and higher-risk riders.
This article is general information, not legal or professional insurance advice. Confirm current Texas requirements and your specific coverage needs with a licensed agent or the Texas Department of Insurance before purchasing a policy.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What motorcycle insurance does Texas law require?
Q2 ?: Why is UM/UIM coverage important for Texas motorcycle riders?
Q3 ?: How much does motorcycle insurance cost in Texas?
Q4 ?: What discounts can lower motorcycle insurance in Texas?
Q5 ?: How do I compare motorcycle insurance quotes accurately?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com


