
TL;DR summary:
- Higher deductibles lower insurance premiums by reducing expected insurer payout but increase your out-of-pocket costs during claims. The structure, amount, and application of deductibles vary across policies, influencing both financial exposure and coverage strategy. Choosing the right deductible depends on your savings, risk tolerance, and ability to handle immediate expenses after a loss.
A deductible is the fixed amount you pay out of pocket before your insurance coverage begins on any claim. This cost-sharing mechanism sits at the center of every policy you own, whether it covers your home, your car, or your health. The role of deductible in insurance goes far beyond a simple dollar figure. It shapes your premium, controls how often you file claims, and directly affects your financial exposure when something goes wrong. Under the Affordable Care Act, 2026 out-of-pocket maximums are capped at $9,200 for individuals and $10,600 for Marketplace plans, with deductibles counting toward those limits. Understanding how deductibles work puts you in control of your coverage decisions.
“The best independent agents do not just find you a policy. They find you the right policy and then make sure it stays right as your life changes.” — Ron Hettler, CIC, Hettler Insurance Agency
Table of Contents
- Key Takeaways
- How do deductibles affect your insurance premium costs?
- What types of deductibles exist across different insurance policies?
- Why do insurance companies use deductibles?
- How should you choose the right deductible amount?
- What I have learned after years of watching clients choose deductibles
- Hettler Insurance Agency can help you find the right deductible
- Frequently Asked Questions
Key Takeaways
The deductible you choose directly controls both your premium cost and your financial exposure at the moment of a claim, making it one of the most consequential decisions in any insurance policy.
| Point | Details |
|---|---|
| Deductible definition | The fixed amount you pay before insurance coverage begins on any claim. |
| Premium impact | Higher deductibles lower premiums; actuaries use the excess ratio to calculate the difference. |
| Structure varies by policy | Health deductibles reset annually; auto deductibles apply per claim; home deductibles may be percentage-based. |
| Insurer rationale | Deductibles filter small claims, reduce administrative costs, and keep premiums affordable for all policyholders. |
| Selection strategy | Match your deductible to your emergency fund, not just your desired monthly premium. |
.
How do deductibles affect your insurance premium costs?
The relationship between your deductible and your premium is inverse. Raise your deductible, and your premium drops. Lower it, and your premium climbs. This is not a coincidence. It reflects a core actuarial principle.
Insurance actuaries use a calculation called the excess ratio to price premiums. The excess ratio measures how much of the insurer’s expected payout falls above your deductible threshold. When you agree to absorb more of the first loss, the insurer’s expected liability shrinks, and so does your premium. The math is precise and consistent across policy types.
The savings can be significant in auto insurance. Increasing your deductible from $50 to $1,000 can reduce physical damage premiums by over 50%, depending on your driver profile and vehicle value. That is a meaningful reduction in annual cost. The catch is that you must be prepared to cover that $1,000 yourself if you file a claim.
The savings are not uniform across coverage types. Collision coverage typically produces larger premium reductions when you raise the deductible than comprehensive coverage does. Collision claims are more frequent, so insurers price that risk more aggressively. Comprehensive claims, covering events like hail or theft, occur less often, so the premium difference from changing the deductible is smaller.
- Higher deductible = lower premium. The insurer takes on less expected loss.
- Lower deductible = higher premium. The insurer absorbs more of every claim.
- Collision savings outpace comprehensive savings when you raise your deductible.
- Your driver profile matters. Age, driving record, and vehicle value all affect how much you save.
Pro Tip: Before raising your deductible to cut your premium, calculate how many months of premium savings it takes to cover the deductible increase. If it takes three years of savings to break even, the trade-off may not be worth the added financial risk.
What types of deductibles exist across different insurance policies?
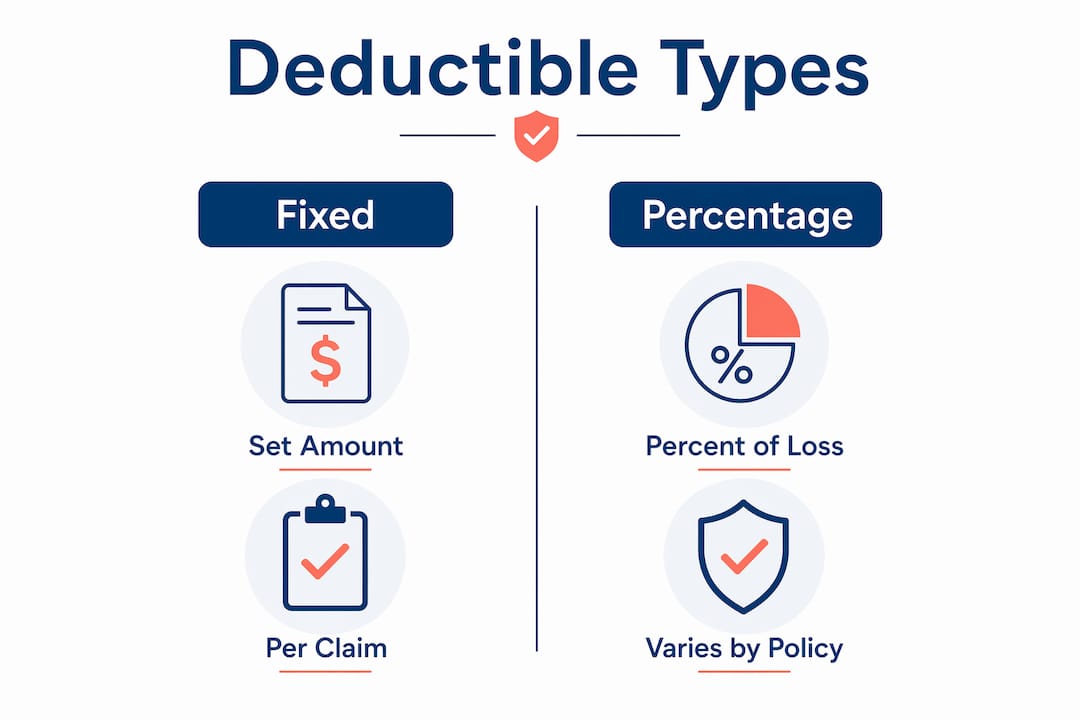
Not all deductibles work the same way. The structure, timing, and dollar amounts vary significantly by policy type. Knowing the differences helps you plan your finances accurately.
Fixed vs. percentage-based deductibles
A fixed deductible is a set dollar amount, such as $1,000 per claim. A percentage-based deductible is calculated as a percentage of your home’s insured value. In Texas, many homeowners policies apply a percentage deductible specifically for wind and hail damage. On a $300,000 home with a 2% wind/hail deductible, you would owe $6,000 before coverage begins. That is a very different exposure than a flat $1,000.
Per-incident vs. annual deductibles
Health insurance uses an annual deductible. You pay toward it throughout the year, and it resets each policy year, commonly on January 1. Once you meet your annual deductible, your insurer covers the remaining eligible costs until the policy year ends. Auto insurance works differently. Collision and comprehensive deductibles apply per claim, not per year. File two collision claims in one year, and you pay the deductible twice. Liability coverage on auto policies generally carries no deductible at all.
Here is how deductible structures compare across major policy types:
| Policy type | Deductible structure | Typical range |
|---|---|---|
| Health insurance | Annual, resets each policy year | $500–$9,200 (ACA cap) |
| Auto (collision) | Per claim | $250–$2,500 |
| Auto (comprehensive) | Per claim | $100–$1,500 |
| Homeowners | Per claim or percentage-based | $1,000–$5,000+ |
| Commercial policies | Per claim or aggregate | $500–$100,000 |
.
Standard insurance deductibles range from $250 to $2,500 for consumers and from $500 to $100,000 for commercial policies. Commercial deductibles are higher because businesses retain more risk and have greater financial capacity to absorb losses. A small business owner facing a $25,000 deductible on a commercial property policy needs to plan for that exposure the same way a homeowner plans for a $2,500 deductible.
Pro Tip: If your health insurance deductible resets in January, schedule non-emergency procedures in the fall after you have already met your annual deductible. Timing medical care around the reset date can save you hundreds of dollars.
Why do insurance companies use deductibles?
Deductibles serve the insurer’s interests as much as yours. The primary purpose is risk filtering. When you carry a deductible, you absorb small losses yourself. That means you are far less likely to file a claim for a minor fender bender or a small roof repair. Fewer small claims mean lower administrative costs for the insurer.
Deductibles filter out small, frequent claims, which reduces insurer administrative costs and keeps premiums affordable for all policyholders. This is not just good for the insurer. Every policyholder benefits when the claims pool stays manageable.
Deductibles align your financial interests with the insurer’s. When you pay the first portion of every loss, you have a direct incentive to avoid careless behavior and minor claims. That shared stake in risk management is what makes the insurance system work for everyone, not just the insurer.
The incentive effect is real. Homeowners with higher deductibles tend to file fewer claims. Fewer claims mean a cleaner claims history, which often translates to lower premiums over time. The deductible does not just reduce your premium today. It shapes your claims behavior in ways that protect your insurability for years.
Commercial policies take this logic further. A business with a $50,000 deductible on its property policy is essentially self-insuring the first layer of every loss. That arrangement makes sense for a company with strong cash reserves. It dramatically reduces premiums and reserves insurance coverage for catastrophic events only.
How should you choose the right deductible amount?
Choosing a deductible is a financial decision, not just an insurance decision. The right amount depends on your savings, your income stability, and your honest assessment of risk.
- Assess your emergency fund first. Your deductible is the amount you must pay immediately after a covered loss. If your emergency fund holds $1,500, a $2,500 deductible leaves you short. Set your deductible at or below what you can pay without borrowing.
- Calculate your break-even point. Divide the premium savings from a higher deductible by the dollar increase in your deductible. That tells you how many claim-free years you need to come out ahead. If the break-even is two years, a higher deductible is likely worth it. If it is seven years, reconsider.
- Factor in your claims history. If you have filed multiple claims in recent years, a lower deductible may cost less overall. Frequent claimants pay the deductible more often, which erodes the premium savings.
- Account for percentage deductibles on your home. Texas homeowners face wind and hail deductibles that scale with home value. On a $400,000 home, a 2% deductible means $8,000 out of pocket before coverage begins. Know that number before you buy.
- Consult a licensed professional before finalizing. Financial advisors recommend selecting deductibles based on personal financial capacity and emergency funds, not just monthly premium minimization. An independent agent can model multiple scenarios for you at no extra cost.
One common mistake is assuming that doubling your deductible will halve your premium. Premium reductions are typically disproportionately smaller than the deductible increase. You may double your financial exposure for a 15% premium reduction. That trade-off only makes sense if your savings are strong enough to absorb the larger deductible comfortably.
Understanding average car insurance costs in your area also helps you calibrate whether a higher deductible is producing meaningful savings or just shifting risk onto your own balance sheet.
What I have learned after years of watching clients choose deductibles
Most clients walk in focused on the monthly premium. That is the wrong starting point. The premium is what you pay every month whether or not anything goes wrong. The deductible is what you pay when everything goes wrong at once. Those are very different financial moments.
The clients who struggle most are the ones who chose a $2,500 deductible to save $40 a month, then faced a hail claim with $800 in savings. They technically had coverage, but they could not afford to use it without going into debt. That is not protection. That is a policy that looks good on paper and fails in practice.
The clients who make the best decisions treat the deductible as a savings target. They set it at the amount they can genuinely afford to pay on a bad day, then revisit it every year as their financial situation changes. A higher deductible makes sense when your emergency fund grows. It stops making sense when your cash reserves shrink.
Reviewing your deductibles annually, especially after major life changes like buying a home, changing jobs, or having children, is one of the most underused tools in personal financial planning. Your deductible should reflect your current financial reality, not the one you had when you first signed the policy.
— Ron Hettler
Hettler Insurance Agency can help you find the right deductible
Choosing the right deductible is easier when you have an experienced, independent agent running the numbers with you.

Hettler Insurance represents over 30 top-rated carriers across Texas, which means the team can compare deductible and premium combinations across multiple policies to find the structure that fits your budget and your risk tolerance. Whether you are protecting a home in Lubbock, a vehicle in West Texas, or a business across the state, the agency’s Certified Insurance Counselors bring over 40 years of experience to every conversation. If you are also building a business and want to understand your coverage baseline, the guide on minimum insurance for entrepreneurs is a practical starting point. Call Hettler Insurance Agency for a no-pressure review of your current deductibles and coverage.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What is the role of a deductible in insurance?
Q2 ?: Does a higher deductible always lower your premium?
Q3 ?: How do health insurance deductibles differ from auto deductibles?
Q4 ?: What deductible amount should a homeowner choose?
Q5 ?: Do deductibles apply to all types of coverage on a policy?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com