
TL;DR summary:
- A commercial package policy combines multiple coverage parts into one policy, offering cost savings and administrative efficiency. It is tailored for businesses with complex risks, providing modular coverage options while excluding workers’ compensation and auto unless specifically added. Regular review and working with an independent agent are essential to ensure comprehensive protection aligned with evolving business needs.
A commercial package policy, known in the insurance industry as a CPP, is defined as a single bundled policy that combines two or more separate coverage parts under one unified contract. If you own a small business in Texas and you’re trying to figure out what is commercial package policy and whether it fits your situation, this guide gives you a direct, practical answer. A CPP is not a one-size-fits-all product. It is a modular system designed to match your specific business risks, and understanding how it works can save you money, reduce coverage gaps, and simplify your insurance management significantly.
Table of Contents
- Key takeaways
- What is a commercial package policy and how does it work?
- CPP vs. BOP: which one does your business need?
- What are the benefits of a package policy for Texas businesses?
- How to choose and customize a commercial package policy
- Common misconceptions about commercial package policies
- What I’ve learned after years of watching business owners get this wrong
- How Hettler Insurance Agency helps Texas businesses get coverage right
- Frequently Asked Questions
Key takeaways
A commercial package policy protects Texas small businesses by bundling modular coverages under one policy, reducing gaps, simplifying administration, and delivering premium savings of 5%–15%.
| Point | Details |
|---|---|
| CPP definition | A CPP bundles two or more coverage parts into one unified, modular policy. |
| Premium savings | Bundling delivers 5%–15% savings compared to separate standalone policies. |
| CPP vs. BOP | Choose a CPP for complex risks; a BOP suits simpler, lower-revenue businesses. |
| Workers’ comp and auto | Neither is included by default; both require separate policies or endorsements. |
| Annual review | Review your CPP declarations every year to match your current business operations. |
What is a commercial package policy and how does it work?
A commercial package policy bundles at least two coverage parts into one policy, and CPPs offer premium discounts of 5% to 15% compared to purchasing each coverage separately. That discount reflects real savings, not a marketing claim. The average monthly CPP cost runs around $90, though your actual cost depends heavily on your industry and risk profile.
The structure of a CPP has four core components:
- Common Policy Declarations: This page identifies the named insured, policy period, and total premium. Every coverage part shares this single declarations page.
- Common Policy Conditions: These are the rules that apply across all coverage parts, including cancellation terms, audit rights, and how changes are made.
- Coverage Parts: These are the individual modules you select, such as commercial property, general liability, commercial crime, inland marine, or commercial auto.
- Endorsements: These are add-ons that modify or expand specific coverage parts to fit your business more precisely.
The shared declarations and conditions across all coverage parts create administrative efficiency that separate policies simply cannot match. You get one renewal date, one billing cycle, and consistent policy language throughout.
| CPP Component | Monoline Policy Equivalent |
|---|---|
| Common Policy Declarations | Separate declarations per policy |
| Shared conditions across all parts | Each policy has its own conditions |
| Modular coverage parts added or removed | Requires separate policy changes |
| Single renewal and billing | Multiple renewal dates and invoices |
| Endorsements modify any part | Endorsements limited to one policy |
.
Pro Tip: Ask your agent to walk you through the declarations page of any CPP quote. If a coverage part you expected is missing from that page, it is not in your policy.
CPP vs. BOP: which one does your business need?
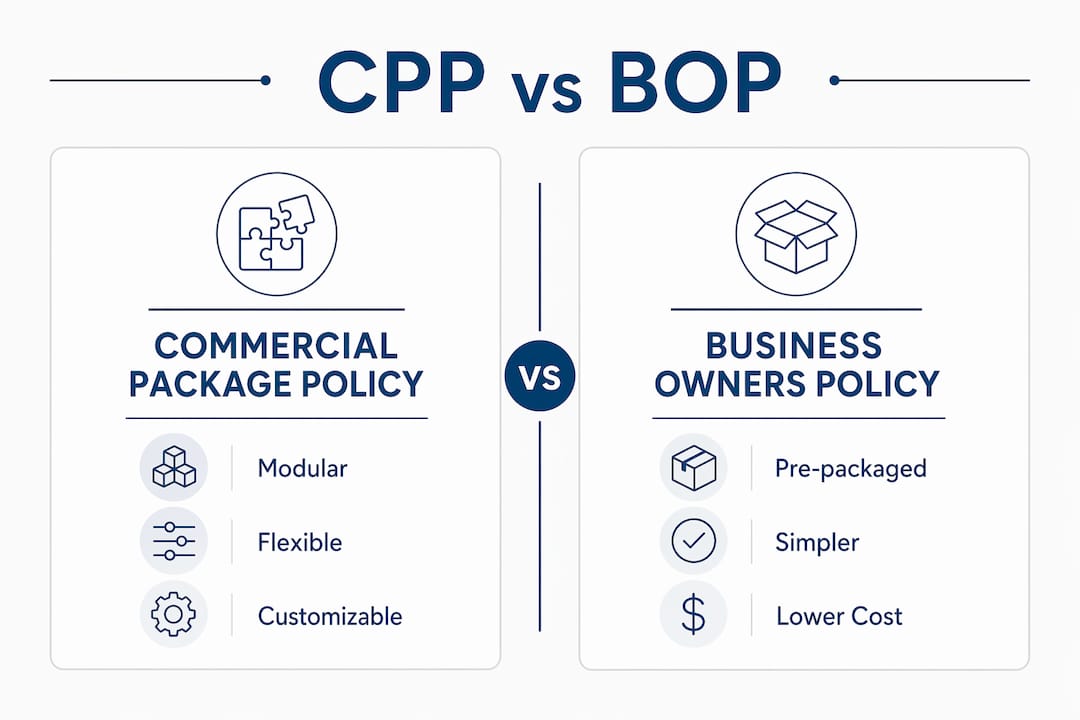
A Business Owners Policy, or BOP, bundles general liability, commercial property, and business income coverage at a lower combined cost. A BOP fits small to mid-size businesses with less complex coverage needs, typically those with under $5 million in annual revenue. The BOP is a pre-packaged product with limited flexibility.
A CPP is the right choice when your business has more complex or varied exposures. Construction companies, manufacturers, businesses with large vehicle fleets, and operations with significant crime exposure all benefit from the CPP’s modular design. A CPP allows businesses to customize coverage by adding property, general liability, crime, commercial auto, and more, which a BOP simply cannot accommodate.
| Feature | CPP | BOP |
|---|---|---|
| Coverage flexibility | High, fully modular | Low, pre-packaged |
| Eligible business types | Most industries, complex risks | Small, lower-risk businesses |
| Revenue threshold | No strict limit | Typically under $5M |
| Cost | Higher, reflects complexity | Lower, standardized |
| Customization via endorsements | Extensive | Limited |
| Workers’ comp included | No, separate policy required | No, separate policy required |
.
Neither a CPP nor a BOP automatically includes workers’ compensation or commercial auto. Both require separate policies or specific endorsements. This is one of the most common and costly misunderstandings Texas business owners encounter.
What are the benefits of a package policy for texas businesses?
The benefits of a package policy go well beyond the premium discount. Bundling in a CPP coordinates coverage to reduce conflicting terms and administrative overhead, which is a practical advantage that shows up when you actually file a claim.
Here are the key benefits Texas small business owners gain from a commercial insurance package:
- Premium savings of 5%–15% compared to buying each coverage part as a standalone policy
- Single renewal date so you never miss a coverage lapse because one policy expired while another was still active
- Consistent policy language across all coverage parts, which reduces disputes about which policy applies to a given claim
- Reduced coverage gaps because all parts are reviewed together and coordinated by one agent
- Easier compliance tracking since Texas industries like construction and transportation face specific liability requirements that are easier to manage under one policy
- Scalability as your business grows, you can add coverage parts without starting over with a new insurer
Texas-specific risks matter here. West Texas businesses face hail damage, wind events, and commercial property losses that require well-structured property coverage. A CPP lets you build that property coverage alongside your liability protection without juggling two separate insurers.
Pro Tip: Before you finalize any CPP, ask your agent to run a coverage gap analysis. Compare what your current policies cover against what the CPP includes. Gaps often appear in crime coverage and equipment breakdown.
How to choose and customize a commercial package policy
Choosing the right commercial insurance package requires a clear-eyed look at your actual business risks before you ever talk price. Follow these steps to get it right.
- List every asset and operation your business depends on. Include your building or leased space, equipment, inventory, vehicles, and any employees who handle cash or sensitive data.
- Identify your liability exposures. Do customers visit your location? Do you perform work at job sites? Do you manufacture a product? Each scenario carries different liability risks.
- Check Texas regulatory requirements. In Texas, workers’ compensation is not mandatory for most private employers, but it is highly recommended and often required by contracts. Confirm what your clients and contracts require before you finalize coverage.
- Select your coverage parts. Most Texas small businesses start with commercial property and general liability, then add commercial auto, crime, or inland marine based on their specific operations.
- Review endorsements carefully. Endorsements modify your base coverage. A data breach endorsement, for example, can add cyber liability protection to a general liability part without requiring a separate cyber policy.
- Work with an independent agent. Independent brokers identify hidden risks and confirm compliance with state mandates that standard online policies often miss. This is not optional advice. It is the difference between a policy that pays and one that doesn’t.
For businesses with vehicles, a commercial auto package policy is a separate but related consideration. Commercial auto does not automatically attach to a CPP. You must add it as a coverage part or purchase it separately, and the limits need to reflect your actual fleet exposure.
Pro Tip: Never assume a coverage part is included because your agent mentioned it in conversation. Verify every coverage part on the declarations page before you sign.
Common misconceptions about commercial package policies
The most dangerous misconception about a CPP is that it covers everything your business needs by default. It does not. Most CPPs exclude workers’ compensation and commercial auto by default, and coverage gaps appear when owners assume otherwise. A denied claim after a workplace injury or a vehicle accident is a costly way to learn this lesson.
Watch out for these common pitfalls:
- Choosing on price alone. Owners who choose the cheapest policy without identifying their specific exposures first are the most likely to face denied claims. Price is a factor, but risk alignment is the priority.
- Not reviewing the policy annually. Your business changes. Your coverage must keep pace. Reviewing CPP declarations annually against your current operations prevents claims denials tied to outdated policy terms.
- Assuming endorsements are automatic. Endorsements must be explicitly added and documented. If you added a new service line or hired drivers, call your agent before the change takes effect.
- Ignoring coordination between policies. If you carry a CPP and a separate commercial auto policy with different insurers, conflicting terms can create gaps. One agent managing all your coverage prevents this.
The real value of a CPP is in closing coverage gaps and simplifying complexity, not just cutting costs. Keep that priority in order.
What I’ve learned after years of watching business owners get this wrong
Most small business owners in Texas come to us after a problem, not before one. They bought the cheapest policy they could find, assumed it covered everything, and then discovered a gap when they needed the coverage most. That pattern is predictable and preventable.
The mistake is treating insurance as a checkbox rather than a risk management decision. A CPP is not just a discount bundle. It is a coordinated system of protections that only works well when it is built around your actual operations. A restaurant in Lubbock has different exposures than a contractor in Midland-Odessa. The policy structure needs to reflect that.
My strongest advice is to stop optimizing for the lowest premium and start optimizing for the fewest gaps. Work with an independent insurance agent who represents multiple carriers and can compare real options across the market. That agent should know Texas regulations, ask about your contracts, and flag what your base policy does not cover before you sign anything.
Review your CPP every year without exception. Businesses grow, add employees, buy vehicles, and take on new contracts. Each change is a potential coverage gap if your policy does not keep pace. Call before the change, not after the claim.
— Ron Hettler
How Hettler Insurance Agency helps texas businesses get coverage right
Hettler Insurance Agency has served Texas small businesses since 1992, and the team understands the specific risks that come with operating in West Texas, from hail and wind damage to contractor liability and commercial fleet exposure. As an independent agency representing over 30 top-rated carriers, Hettler Insurance Agency shops the market to find the right CPP structure for your business at a competitive price.

Ron Hettler and Meghan Hettler are both Certified Insurance Counselors (CIC), which is the gold standard credential in the industry. That expertise means they ask the right questions, spot the gaps other agents miss, and build policies that actually perform when you need them. If you are ready to review your current coverage or build a CPP from scratch, start with minimum coverage requirements for Texas entrepreneurs, then call Hettlerinsurance for a no-pressure consultation. Get Hettler, Get Better.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What does a commercial package policy cover?
Q2 ?: Is a commercial package policy necessary for my Texas business?
Q3 ?: How is a CPP different from a BOP?
Q4 ?: Does a commercial package policy include commercial auto in Texas?
Q5 ?: How much does a commercial package policy cost in Texas?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com