
TL;DR summary:
- Hail damage insurance covers repairs or replacements of property structures damaged by hailstorms. It is essential for Texas homeowners due to the high frequency of hail in “Hail Alley” and increasing insurer deductibles and premiums. Proper coverage, including understanding deductibles and considering parametric options, helps prevent significant out-of-pocket costs after storms.
Hail damage insurance is defined as property coverage that pays for repairs or replacement of structures damaged by hailstorms, protecting you from potentially catastrophic out-of-pocket costs. In Texas, this coverage is not optional in any practical sense. Severe convective storms caused $42 billion in insured losses in 2025 across the U.S., with hail driving up to 80% of those losses. Understanding why insure against hail damage matters starts with knowing what that financial exposure looks like for a Texas homeowner. The numbers are not abstract. They show up on your roof, your bank account, and your next renewal premium.
Table of Contents
- Key takeaways
- Why insure against hail damage in Texas?
- What does homeowners insurance cover for hail damage?
- How do percentage-based deductibles affect your costs?
- What is parametric hail insurance and how does it help?
- How to protect your property and strengthen your hail claim
- What I’ve learned after years of watching Texas hail claims go wrong
- Get the right hail coverage for your Texas home
- Frequently Asked Questions
Key Takeaways
Insuring against hail damage in Texas is a financial necessity, not a precaution, because hail losses now rival hurricanes in dollar impact and percentage-based deductibles can leave homeowners with five-figure out-of-pocket costs before insurance pays a cent.
| Point | Details |
|---|---|
| Hail losses are enormous | Severe storms caused $42 billion in insured losses in 2025, with hail driving up to 80% of that total. |
| Percentage deductibles are costly | A 2% deductible on a $300,000 home means $6,000 out of pocket before your insurer pays anything. |
| Fortified roofs save money | Upgrading to IBHS Fortified roofing standards can cut your wind and hail premium by up to 55%. |
| Parametric coverage fills the gap | Products like Sola pay within 7–10 days based on weather data, covering deductibles without affecting your base policy. |
| Documentation wins claims | Annual roof photos and inspection reports are your strongest defense against a denied or reduced hail claim. |
Why insure against hail damage in Texas?
Hail damage coverage is the single most financially consequential protection a Texas homeowner can carry. Texas sits inside what meteorologists call “Hail Alley,” a corridor stretching from West Texas through the Panhandle where large hail events are more frequent than almost anywhere in the country. Hail is now on par with major hurricanes in financial impact on property insurance claims. That comparison should stop you cold. Most Texans prepare for hurricanes. Far fewer treat hail with the same urgency, and that gap is where financial disaster lives.
Insurance companies are raising premiums and restructuring deductibles specifically because hail losses have become so frequent and so expensive. If you are a homeowner or renter in Lubbock, Midland, Amarillo, or anywhere across West Texas, your property faces this risk every spring and summer. Skipping or underbuying hail coverage means absorbing those costs yourself.
What does homeowners insurance cover for hail damage?
Standard homeowners insurance policies cover hail damage to your home’s primary structure, detached structures like garages and fences, and personal property damaged by hail that penetrates the building. Most policies written in Texas include wind and hail as named perils under the dwelling coverage section. Here is what a typical policy covers and where the limits begin:
- Roof damage: Covered when hail causes sudden, direct physical damage. Age and condition of the roof affect whether you receive replacement cost value or actual cash value.
- Siding and gutters: Covered under dwelling coverage when hail causes measurable physical damage.
- Detached structures: Garages, sheds, and fences are typically covered at 10% of your dwelling limit.
- Personal property: Items damaged inside the home when hail breaches the structure are covered, subject to your personal property limit.
- Cosmetic exclusions: Many Texas policies now include cosmetic damage exclusions, meaning dents to metal roofing or siding that do not affect function are not covered.
- Wear and tear: Pre-existing deterioration is never covered. Insurers will deny claims where damage is attributed to deferred maintenance rather than storm impact.
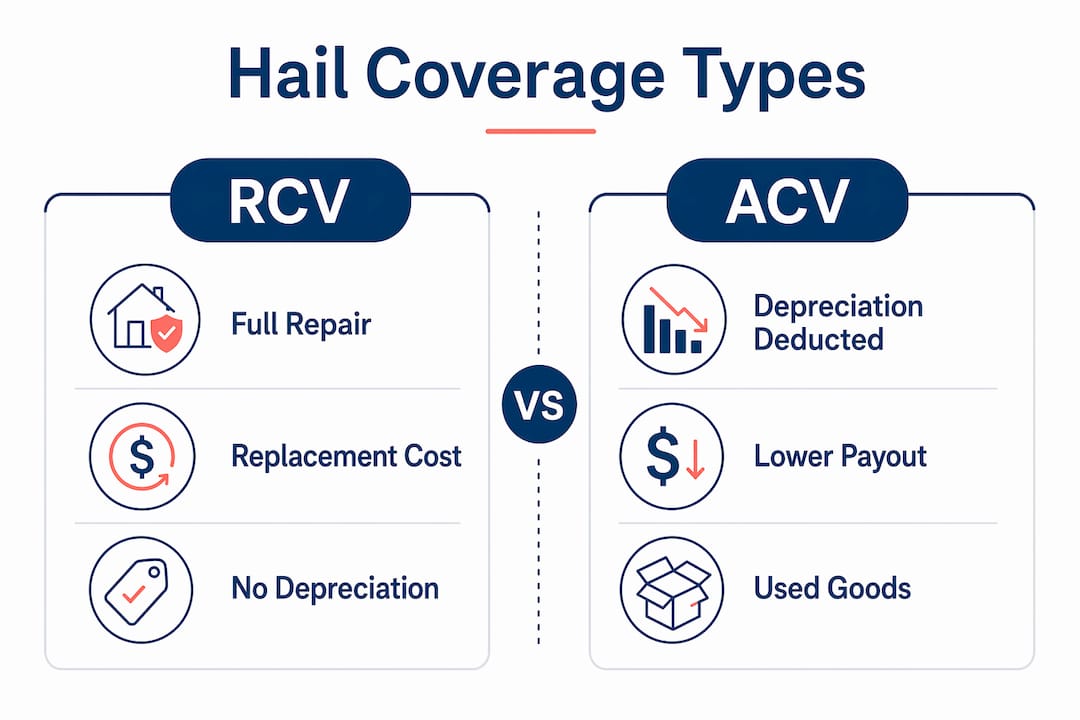
The distinction between replacement cost value (RCV) and actual cash value (ACV) is critical. RCV pays what it costs to replace your roof today. ACV pays that amount minus depreciation. On a 15-year-old roof, ACV could leave you with a fraction of actual repair costs. Many homeowners carry underinsured policies that do not fully cover rising repair costs due to construction inflation and labor shortages. Review your coverage limits annually, not just when you renew.
How do percentage-based deductibles affect your costs?
A percentage-based deductible is calculated as a fixed percentage of your home’s insured value, not a flat dollar amount. This distinction costs Texas homeowners thousands of dollars every year without warning.
Here is how the math works in practice:
- Identify your insured value. If your home is insured for $300,000, your deductible baseline is that number.
- Apply the percentage. Typical wind and hail deductibles range from 1% to 5% of insured value. At 2%, your deductible on a $300,000 home is $6,000. At 5%, it is $15,000.
- Compare to repair costs. A full roof replacement in Texas averages $10,000–$20,000. Your deductible may consume most or all of that cost.
- Check your policy language. Your declarations page will show whether your wind and hail deductible is a flat dollar amount or a percentage. Many homeowners discover the percentage structure only after a storm.
At a 2% deductible on a $500,000 home, the homeowner pays $10,000 before the insurer contributes a single dollar. That is a figure most families are not prepared to absorb. The trend in 2026 is moving further toward higher percentage deductibles as carriers respond to mounting hail losses. Understanding your Texas deductible structure before a storm hits is not optional. It is the difference between a manageable claim and a financial crisis.
Pro Tip: Pull out your declarations page right now and look for the wind and hail deductible line. If it shows a percentage rather than a dollar amount, call your agent to calculate your exact out-of-pocket exposure before the next storm season.
What is parametric hail insurance and how does it help?
Parametric insurance is a policy type that pays out based on verified weather data rather than a traditional damage assessment by an adjuster. For hail coverage, this means your payout triggers automatically when a storm of a defined size hits your location, with no inspection required and no claim filed against your standard policy.
Sola is one example of a parametric wind and hail product designed specifically to cover deductibles and other out-of-pocket costs after a hailstorm. Sola uses NOAA and National Weather Service data to trigger payouts, with funds delivered within 7–10 days and no adjuster visit needed. Payouts can reach up to $25,000. The claim is not reported to CLUE (Comprehensive Loss Underwriting Exchange), so it does not affect your standard policy’s claims history or future premiums.
Key benefits of supplemental parametric coverage include:
- Speed: Funds arrive in 7–10 days, not weeks or months after adjuster backlogs.
- Deductible coverage: Designed specifically to offset the high out-of-pocket costs created by percentage-based deductibles.
- No premium impact: Because the claim does not touch your homeowners policy, your base premium is not affected.
- Simplicity: No damage documentation required for payout. The weather data does the work.
Parametric supplemental insurance gives homeowners a practical tool to manage the financial gap that large deductibles create. This type of coverage makes the most sense when your wind and hail deductible exceeds $5,000, when you live in a high-frequency hail zone like West Texas, or when a large unexpected expense would create real financial hardship.
Pro Tip: Ask your independent agent whether a parametric product like Sola is available in your area. The annual premium is typically far lower than the deductible it protects against.
How to protect your property and strengthen your hail claim
Preparation before a storm is as important as the coverage you carry. The steps below reduce your financial exposure and improve your odds of a successful claim.
- Document your roof annually. Take dated photos of your roof’s condition every year and after every major storm. Roof age, condition, and maintenance documentation directly affect claim approval and compensation amounts. An undocumented roof in poor condition gives an insurer grounds to deny or reduce your claim.
- Upgrade to Fortified roofing standards. The IBHS (Insurance Institute for Business and Home Safety) Fortified program certifies roofs built to resist wind and hail damage. Roofs upgraded to Fortified standards can earn premium discounts of up to 55% on the wind and hail portion of your policy. That is a direct return on your investment.
- File claims promptly. Texas law requires you to notify your insurer of a loss within a reasonable time. Delays give adjusters reason to question whether damage is storm-related or pre-existing.
- Know when not to file. If repair costs fall near or below your deductible, paying out-of-pocket protects your claims history and keeps your premium stable. Filing a claim for $500 above your deductible is rarely worth the long-term premium impact.
- Review your coverage limits before storm season. Construction costs have risen sharply. A coverage limit set three years ago may not cover a full rebuild today.
Climate change is expanding hail risk area and frequency, which means the storms hitting Texas are becoming more frequent and more severe. Preparation is your first line of defense. Insurance is your financial backstop.
Pro Tip: Schedule a roof inspection every spring before storm season begins. A written inspection report from a licensed contractor is the strongest evidence you can have if a claim is disputed.

What I’ve learned after years of watching Texas hail claims go wrong
I have worked with Texas homeowners long enough to see the same painful pattern repeat. A major hailstorm rolls through Lubbock or Midland. Homeowners call to file a claim. Then they discover their deductible is $12,000, their roof is depreciated to almost nothing under an ACV policy, and their coverage limit has not kept pace with construction costs. The storm did not create their financial problem. The policy they never fully read did.
The insurance market in 2026 is not the same as it was five years ago. Carriers are tightening underwriting, raising percentage deductibles, and adding cosmetic exclusions. Hail frequency and severity are increasing due to shifting storm patterns, and that pressure is flowing directly into policy terms and premiums. Homeowners who treat their policy as a set-and-forget document are the ones who get hurt.
My honest advice: read your declarations page every year. Understand whether you have RCV or ACV on your roof. Know your deductible in dollars, not just as a percentage. And seriously consider a supplemental parametric product if your deductible is above $5,000. The annual cost is small compared to what it protects. Smart coverage planning is not about spending more. It is about spending right.
— Ron
Get the right hail coverage for your Texas home

Hettler Insurance Agency has helped Texas homeowners navigate hail damage coverage since 1992. As an independent agency representing over 30 top-rated carriers, Hettler Insurance Agency shops your coverage across the market to find the right fit at the right price. Whether you need to review your current deductible structure, upgrade to replacement cost coverage, or add a supplemental parametric policy, the team at Hettler Insurance Agency gives you real options without pressure. Ron Hettler and Meghan Hettler are both Certified Insurance Counselors (CIC), the gold standard credential in the industry. Get the coverage your home actually needs. Review your home coverage with Hettlerinsurance today, and check out this guide on storm insurance essentials to understand what West Texas homeowners face every storm season.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What is hail damage insurance?
Q2 ?: Why is hail insurance important for Texas homeowners?
Q3 ?: How does a percentage-based hail deductible work?
Q4 ?: What is parametric hail insurance and do I need it?
Q5 ?: Does filing a hail claim raise my insurance premium?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com