
TL;DR summary:
- Insurance compliance involves following laws and policies that govern insurance practices and protect organizations from penalties. Non-compliance leads to severe fines, regulatory sanctions, reputational damage, and increased operational risk. Implementing continuous monitoring, clear ownership, accurate documentation, and leveraging AI technology enhances organizational compliance and risk management.
Insurance compliance is defined as the practice of adhering to all laws, regulations, and internal policies that govern how insurance products are sold, managed, and administered. For individuals and businesses alike, it determines legal standing, financial exposure, and long-term protection. The penalties for getting it wrong are steep. COBRA notice failures alone can cost up to $110 per day per beneficiary in 2026. Understanding why insurance compliance matters is not optional. It is the foundation of every sound risk management strategy.
Table of Contents
- Key takeaways
- Why insurance compliance matters for every policyholder
- How does insurance compliance benefit individuals and businesses?
- What risks do organizations face without insurance compliance?
- How is insurance compliance evolving with technology?
- What practical steps ensure strong insurance compliance?
- The compliance mindset most organizations still get wrong
- How Hettler Insurance Agency helps you stay protected and compliant
- Frequently Asked Questions
Key takeaways
Insurance compliance protects individuals and businesses from legal penalties, financial losses, and reputational harm by requiring adherence to licensing, reporting, consumer protection, and anti-fraud standards.
| Point | Details |
|---|---|
| Penalties are per-day and compounding | COBRA, ERISA, and Transparency in Coverage violations each carry daily fines that add up fast. |
| Outsourcing does not remove liability | Employers retain fiduciary responsibility even when a TPA or broker manages compliance tasks. |
| Compliance failures are usually preventable | Siloed teams and poor documentation cause most violations, not intentional wrongdoing. |
| Technology is reshaping compliance | AI-driven monitoring replaces annual checklists with real-time regulatory tracking and automated audit trails. |
| Documentation is your primary defense | Clean, organized records of notices, decisions, and vendor communications protect you in any regulatory examination. |
Why insurance compliance matters for every policyholder
Insurance compliance, known formally as regulatory compliance in insurance, covers a wide range of obligations. These include state licensing, financial reporting, anti-fraud controls, data protection, and consumer protection standards. Every insurer, employer offering benefits, and business purchasing coverage operates within this framework whether they realize it or not.
The regulatory scope is broader than most people expect. Federal laws like ERISA, COBRA, and the Transparency in Coverage rule set minimum standards for employer-sponsored benefits. State-level frameworks, including NAIC model regulations, govern how insurers are licensed and how they handle claims. Anti-money laundering (AML) and know-your-customer (KYC) requirements add another layer for carriers processing large transactions.
Here is a quick overview of the major compliance areas and what they require:
| Compliance Area | Key Requirement | Who It Affects |
|---|---|---|
| COBRA | Timely notices to beneficiaries | Employers with 20+ employees |
| ERISA | Plan document availability | Employers offering benefit plans |
| Transparency in Coverage | Public cost-sharing disclosures | Health insurers and employers |
| State Licensing | Valid license in each operating state | All insurance carriers |
| AML/KYC | Customer identity verification | Carriers and brokers |
.
The core obligations break down into four categories:
- Licensing: Insurance companies must maintain valid licenses in every state where they operate. Letting a license lapse means unauthorized selling and direct regulatory penalties.
- Financial reporting: Insurers must file accurate, timely financial statements with state regulators. Errors here trigger audits and can result in license restrictions.
- Consumer protection: Complaint handling is both a legal requirement and a trust factor. Transparent complaint management directly affects a company’s reputation and customer relationships.
- Data protection and anti-fraud: Carriers must protect policyholder data and report suspicious activity under AML and KYC rules.
How does insurance compliance benefit individuals and businesses?
The insurance compliance benefits are concrete and measurable. They go well beyond avoiding fines.
- Avoiding costly penalties. The numbers are specific and serious. ERISA document request failures carry penalties of up to $195 per day. Transparency in Coverage violations reach $100 per day per affected person. These are not theoretical risks. Nearly half of insurers face fines or refunds due to compliance errors, even as 70% plan to spend more time on regulatory compliance in 2026.
- Protecting consumer rights. Compliance frameworks require insurers to handle claims fairly, disclose costs accurately, and respond to complaints within defined timeframes. When these standards are met, policyholders receive the protection they paid for.
- Building brand trust. Businesses that demonstrate clean compliance records attract better carrier relationships and lower premiums over time. Regulators and clients both notice when an organization operates with consistent accountability.
- Reducing operational risk. Compliance programs force organizations to document processes, assign ownership, and review outcomes regularly. That discipline catches errors before they become violations.
- Gaining a competitive edge. Regulators now demand evidence of real outcomes, not just policies on paper. Companies that build data-driven compliance programs respond faster to regulatory changes and outperform competitors who treat compliance as a checkbox.
Pro Tip: Review your benefits compliance calendar at the start of each quarter. COBRA and ERISA deadlines are fixed, and missing a single notice triggers per-day penalties that compound fast.
What risks do organizations face without insurance compliance?
Non-compliance is rarely the result of bad intentions. Operational gaps such as siloed teams and poor process design are the most common causes of compliance failures. That distinction matters because it means most violations are preventable with the right systems in place.
The consequences of ignoring insurance regulations impact every level of an organization:
- Regulatory audits and examinations. State insurance departments conduct market conduct exams. An organization without clean documentation faces extended scrutiny and potential corrective action orders.
- License restrictions or revocation. Repeated violations can result in a carrier losing the right to sell in a specific state. For a business, that means losing coverage options or facing gaps in protection.
- Reputational damage. Enforcement actions are public record. A single publicized penalty can erode years of client trust, especially for small businesses and independent agents.
- Financial exposure. Per-day penalties under COBRA, ERISA, and Transparency in Coverage accumulate quickly. A 30-day ERISA documentation failure costs up to $5,850 per incident.
“Employers retain primary fiduciary responsibility for benefits compliance even when outsourcing tasks to vendors like TPAs or brokers.” — Apex Benefits, 2026
This point catches many business owners off guard. Hiring a third-party administrator (TPA) or broker to manage your benefits does not transfer your legal liability. The fiduciary duty stays with you. If your vendor makes an error, you are still the responsible party in the eyes of the regulator.
Slow adaptation to new regulations compounds these risks. When laws change and internal processes do not, the gap between what is required and what is practiced widens. That gap is where violations live.
How is insurance compliance evolving with technology?
The compliance function in insurance is changing faster than most organizations realize. Static compliance programs built on annual checklists are giving way to intelligence-driven approaches that use AI for real-time regulatory monitoring and operational insight.
Here is how the old model compares to the new one:
| Traditional Compliance | Intelligence-Driven Compliance |
|---|---|
| Annual policy reviews | Continuous regulatory monitoring |
| Manual audit trails | Automated evidence collection |
| Reactive to violations | Proactive risk identification |
| Siloed compliance teams | Integrated, cross-functional oversight |
| Board receives annual reports | Board receives real-time data dashboards |
.
AI technology enables insurance firms to anticipate regulatory risks before they become violations. That shift transforms compliance from a cost center into a strategic function. Wolters Kluwer describes this as moving from static to dynamic compliance, where continuous monitoring and automated alerts replace periodic reviews.
One concept gaining traction in this space is Humanomation®, a philosophy developed by Benekiva that pairs automation with human empathy and expertise. The idea is that technology handles data processing and regulatory tracking while trained professionals handle judgment calls and client-facing decisions. That combination creates programs that are both scalable and defensible.
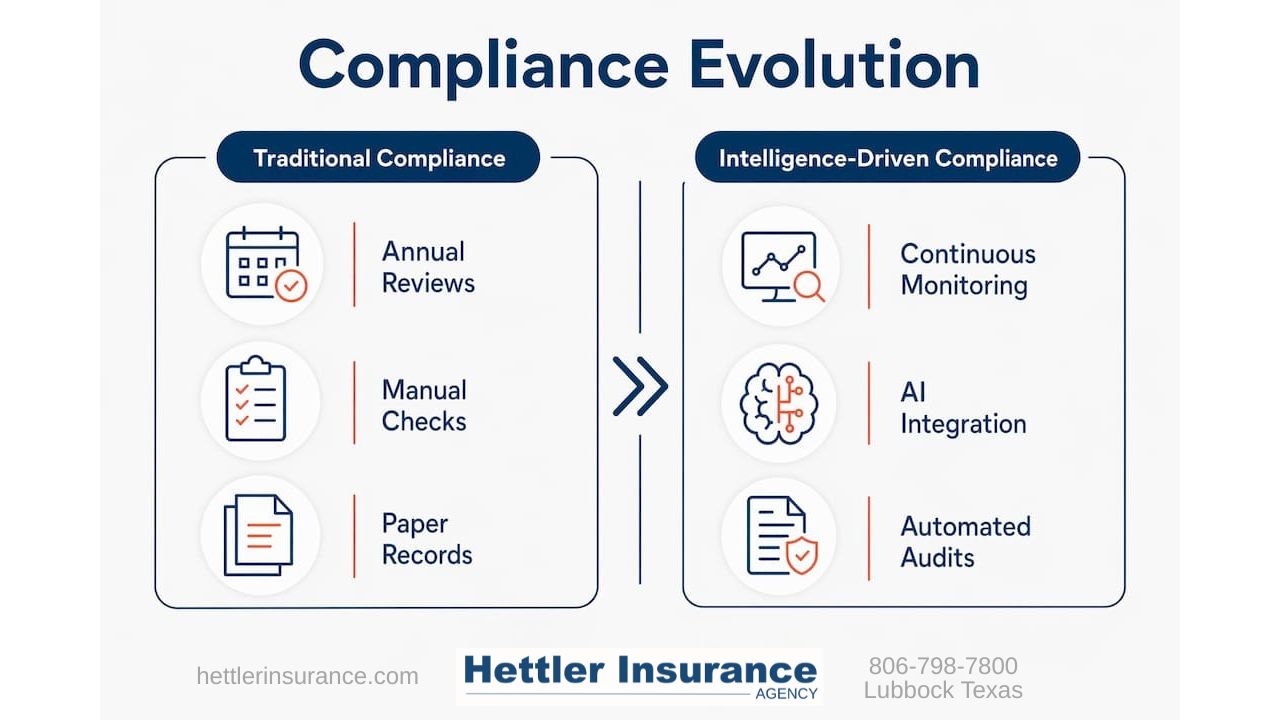
Compliance leaders now emphasize that Boards and management must actively demonstrate oversight, moving beyond passive governance to measurable, data-backed accountability. Regulators expect to see evidence of real outcomes, not just written policies.
Pro Tip: If your organization uses a TPA or compliance software, schedule a mid-year internal audit. Catching documentation gaps in July is far less costly than discovering them during a December regulatory examination.
What practical steps ensure strong insurance compliance?
Building a solid compliance program does not require a large legal team. It requires structure, ownership, and consistency. Here is how to get there:
- Assign clear ownership. Every compliance obligation needs a named responsible party. Shared responsibility means no one acts when a deadline approaches.
- Conduct regular audits. Evidence-based compliance programs with clean, automated audit trails significantly improve regulatory examination outcomes. Schedule mid-year reviews, not just year-end ones.
- Document everything. Regulators do not accept verbal explanations. Written records of decisions, notices sent, and vendor communications are your defense in any audit.
- Monitor regulatory changes in real time. Subscribe to NAIC bulletins, state insurance department updates, and federal agency notices. Assign someone to review these weekly.
- Engage leadership with data. Present compliance outcomes to your board or ownership group using metrics, not just status updates. Show what was tested, what passed, and what was corrected.
For individuals managing personal insurance, the same logic applies at a smaller scale. Review your policy terms annually, confirm your coverage meets state minimums, and keep records of all communications with your carrier. If you are a Texas contractor navigating compliance, the stakes are especially high because licensing and liability requirements vary by project type and contract terms.
Pro Tip: Keep a dedicated compliance folder, digital or physical, with copies of all insurance certificates, policy declarations, and renewal notices. If a dispute arises, that folder is your first line of defense.
The compliance mindset most organizations still get wrong
After working in and around insurance for years, the pattern I see most often is this: organizations treat compliance as a task to complete rather than a condition to maintain. They build a checklist, run through it once a year, and consider the job done. Then a regulation changes in March, no one updates the process, and by December they are facing a penalty that a single calendar alert would have prevented.
The organizations that handle compliance well share one trait. They treat it as continuous risk management, not a periodic project. They assign real ownership, review outcomes with data, and involve leadership in the conversation. That approach is not complicated. It is just disciplined.
The Humanomation® model resonates with me because it acknowledges what checklists cannot do. Automation handles the volume and speed of regulatory tracking. Human judgment handles the interpretation and the client relationship. You need both. A compliance program built entirely on software will miss context. One built entirely on manual review will miss changes.
For individuals, the lesson is simpler but equally important. Know what your policy requires of you. Understand the consequences of going uninsured or underinsured. And when you are unsure, ask your agent before you sign anything. That one conversation can prevent a coverage gap that costs you far more than the premium you were trying to avoid.
— Ron
How Hettler Insurance Agency helps you stay protected and compliant
Hettler Insurance Agency has guided Texas individuals and businesses through insurance decisions since 1992. Ron Hettler and his daughter Meghan are both Certified Insurance Counselors (CIC), the gold standard credential in the industry. That expertise means they understand not just what coverage costs, but what it requires.

Whether you are a small business owner trying to meet state minimums or an entrepreneur figuring out minimum insurance coverage for your new venture, Hettler Insurance shops across more than 30 top-rated carriers to find the right fit. You get real choice, expert guidance, and no extra fees. Call Hettler Insurance Agency today and make sure your coverage actually protects you when it counts.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What is insurance compliance?
Q2 ?: What are the penalties for insurance compliance failures in 2026?
Q3 ?: Does outsourcing compliance to a TPA remove my liability?
Q4 ?: How does technology improve insurance compliance programs?
Q5 ?: Why do most insurance compliance failures happen?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com