
TL;DR summary:
- Coverage limits define the maximum amount your insurer will pay for covered losses, and exceeding these limits results in out-of-pocket expenses. Different limit types, such as per-occurrence, aggregate, sublimits, and single limits, shape your financial protection, especially for high-value items and specific coverage categories. Regularly reviewing and updating your policy ensures it reflects current rebuilding costs and asset values, reducing the risk of underinsurance during a claim.
A coverage limit is the maximum dollar amount your insurance company will pay for any covered loss or claim. Once a claim exceeds that ceiling, you pay the difference out of pocket. For Texas homeowners and renters, this number is not a formality. It is the actual boundary of your financial protection against property damage, liability claims, and personal property loss. Your declarations page lists every limit that applies to your policy, and reviewing it regularly is the single most important step you can take to avoid a costly gap.
Coverage limits apply across property damage, liability, and personal belongings. Understanding the coverage limit definition in your specific policy tells you exactly how much risk you are carrying versus how much your insurer has agreed to absorb.
Table of Contents
- Key Takeaways
- What types of coverage limits exist in insurance policies?
- How do coverage limits affect homeowners and renters in Texas?
- What is the difference between coverage limits, deductibles, and exclusions?
- How to choose the right coverage limits for your policy
- Why coverage limits deserve more attention than most Texans give them
- Hettler Insurance Agency helps Texas homeowners find the right coverage limits
- Frequently Asked Questions
Key Takeaways
A coverage limit is the hard ceiling on your insurer’s payout, and choosing limits below your actual exposure transfers financial risk directly back to you.
| Point | Details |
|---|---|
| Coverage limit definition | The maximum dollar amount your insurer pays for a covered loss; you pay any amount above it. |
| Sublimits create hidden gaps | Items like jewelry or electronics often carry sublimits far below the overall policy limit. |
| Deductibles reduce actual payout | Your real payout equals the covered loss minus your deductible, not the full coverage limit. |
| Rebuild cost drives dwelling limits | Set Coverage A at estimated rebuild cost, not market value, to avoid a shortfall after a total loss. |
| Minimum limits are not enough | Legal minimums satisfy financial responsibility laws but leave policyholders exposed in large claims. |
.
What types of coverage limits exist in insurance policies?
Insurance policies include two core limit structures: per-occurrence limits and aggregate limits. A per-occurrence limit caps the payout for a single incident. An aggregate limit caps the total payout across all claims within a policy period. A common structure pairs a $1,000,000 per-occurrence limit with a $2,000,000 aggregate limit. That means one storm can trigger up to $1,000,000 in coverage, but two or more claims in the same year cannot exceed $2,000,000 combined.
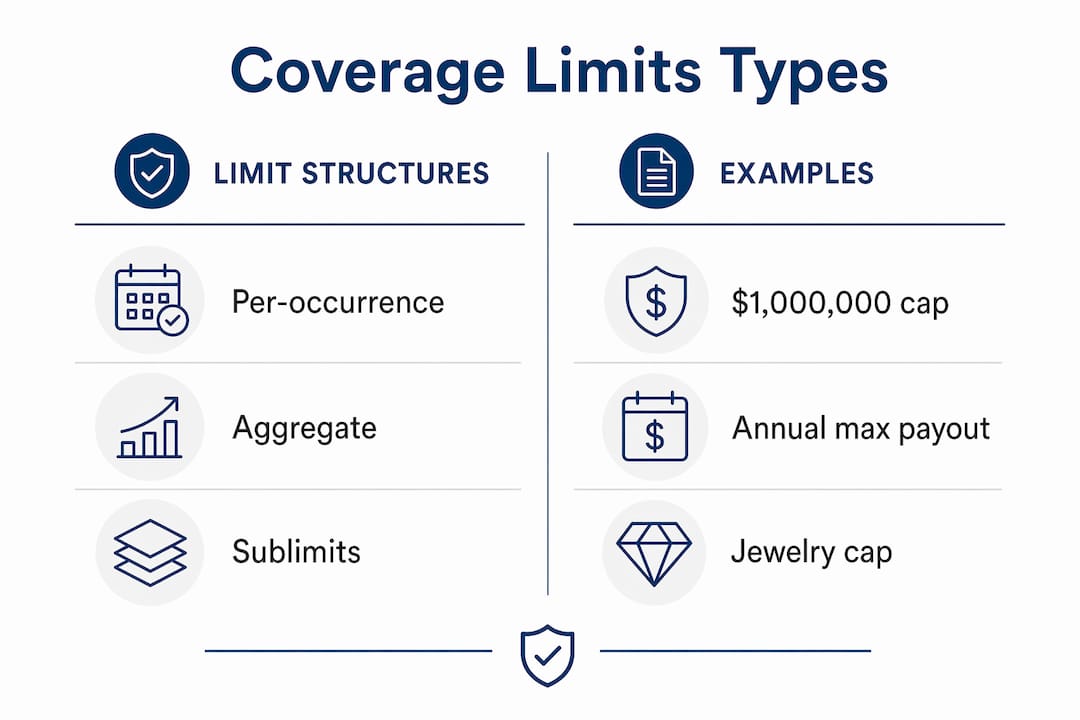
Beyond those two structures, policies also use sublimits and single limits. Sublimits cap coverage for specific items like jewelry, electronics, or artwork at amounts far below the overall policy limit. A policy with $100,000 in personal property coverage might only pay $1,500 for stolen jewelry. That gap surprises policyholders who never read the fine print. A single limit policy, by contrast, applies one combined dollar amount across multiple coverage categories rather than splitting them.
| Limit Type | How It Works | Example |
|---|---|---|
| Per-occurrence | Maximum payout per single incident | $1,000,000 per claim |
| Aggregate | Maximum total payout per policy period | $2,000,000 per year |
| Sublimit | Cap on specific item categories | $1,500 for jewelry |
| Single limit | One combined limit across categories | $300,000 total coverage |
| Split limit | Separate limits per coverage category | $200,000 dwelling, $50,000 personal property |
.
Pro Tip: Pull out your declarations page and locate every sublimit listed. If you own high-value items like jewelry, art, or musical instruments, ask your agent about a scheduled personal property endorsement to raise those sublimits.
How do coverage limits affect homeowners and renters in Texas?
Typical homeowners policies split coverage limits into four categories: Coverage A for the dwelling, Coverage B for other structures, Coverage C for personal property, and Coverage D for additional living expenses. Each carries a separate limit. Your dwelling limit should reflect the estimated cost to rebuild your home, not its market value. In West Texas, where construction costs have risen sharply, a home that sells for $250,000 might cost $320,000 to rebuild from the ground up after a hailstorm.
That gap between market value and replacement cost is where Texas homeowners get hurt. If your Coverage A limit is set at market value and a total loss occurs, you face a five-figure or six-figure shortfall. Renters face a different version of the same problem. A renter with $20,000 in personal property coverage who loses electronics, furniture, and clothing in a fire may find that amount falls well short of actual replacement costs.
| Coverage Category | What It Covers | Common Limit Range |
|---|---|---|
| Coverage A (Dwelling) | Structure of the home | Set at estimated rebuild cost |
| Coverage B (Other structures) | Fences, detached garages | Typically 10% of Coverage A |
| Coverage C (Personal property) | Furniture, electronics, clothing | Typically 50–70% of Coverage A |
| Coverage D (Additional living expenses) | Hotel, meals during repairs | Typically 20% of Coverage A |
| Liability | Bodily injury or property damage claims | $100,000–$500,000 |
.
The declarations page is the legally binding document that confirms every one of these limits. Review it every year, especially after renovations, major purchases, or significant changes in local construction costs.
Pro Tip: Ask your agent to run a replacement cost estimator for your home every two to three years. Construction costs shift, and your Coverage A limit needs to keep pace or you risk being underinsured when a claim hits.
What is the difference between coverage limits, deductibles, and exclusions?
Coverage and limits are frequently confused with deductibles and exclusions, but all three work differently. Together, they define your real financial protection. Understanding each one separately prevents costly surprises at claim time.
A coverage limit is the ceiling on what your insurer will pay. A deductible is the amount you pay first before your insurer pays anything. An exclusion removes certain risks from coverage entirely, regardless of your limit.
Here is how they interact in practice:
- Coverage limit: Your policy pays a maximum of $300,000 for dwelling damage. Any repair cost above that amount is your responsibility.
- Deductible: Your policy has a $2,500 deductible. A $50,000 hail repair claim results in your insurer paying $47,500 after you cover the first $2,500.
- Exclusion: Flood damage is excluded from standard homeowners policies in Texas. No matter how high your coverage limit is, a flood claim pays nothing without a separate flood policy.
The coverage limit listed in your policy applies before deductibles and valuation methods are factored in. Your actual payout is the covered loss minus your deductible, calculated using either actual cash value or replacement cost. Actual cash value subtracts depreciation. Replacement cost pays what it actually costs to replace the item new. That distinction alone can mean thousands of dollars on a single claim.
Knowing your limit, deductible, and exclusions together gives you the complete picture of your financial protection under your policy. Knowing only one of the three leaves you guessing.
How to choose the right coverage limits for your policy
Selecting the right policy coverage limits requires four concrete steps. Skip any one of them and you risk carrying a gap you will not discover until a claim is already filed.
- Calculate your home’s rebuild cost, not its sale price. Contact a local contractor or ask your insurance agent to run a replacement cost estimate. In Texas, material and labor costs vary significantly between Lubbock, Houston, and the Dallas Metroplex. Your Coverage A limit must reflect local rebuild costs.
- Inventory your personal property. Walk through your home and document every item of value. Total the replacement cost of electronics, appliances, furniture, clothing, and tools. That number is your minimum Coverage C limit. Most homeowners underestimate this figure by a wide margin.
- Review every sublimit in your policy. Sublimits hidden in policy fine print can leave high-value items severely underprotected. If you own jewelry, collectibles, firearms, or musical instruments, ask your agent about scheduled endorsements that raise those specific sublimits.
- Set your liability limit based on your assets, not the minimum. State-mandated minimum insurance limits satisfy legal financial responsibility requirements but do not provide adequate personal protection. If someone is injured on your property and sues for $400,000, a $100,000 liability limit leaves you personally responsible for the remaining $300,000.
Policyholders can increase coverage limits by purchasing higher limits, which raises premiums but reduces the risk of out-of-pocket losses. The premium increase for doubling a liability limit from $100,000 to $300,000 is typically modest compared to the financial exposure it eliminates.
Pro Tip: Review your declarations page every year at renewal. If you renovated your kitchen, added a room, or bought significant new furniture, your existing limits may no longer reflect your actual exposure. Call your agent before your renewal date, not after a claim.
Avoiding minimum-limit policies is the single most important piece of advice for Texas homeowners and renters. Minimum limits exist for legal compliance only. They are not designed to protect your finances in a serious loss. Learn how much home insurance is enough for your specific property before you accept any policy at face value.
Why coverage limits deserve more attention than most Texans give them
Most policyholders treat their coverage limit as a number on a page. I have seen what happens when that number turns out to be wrong at the worst possible moment.
The most common mistake I see in Texas is homeowners who set their dwelling limit at the purchase price of their home. That number reflects market value, land included. It has almost nothing to do with what it costs to rebuild four walls and a roof after a West Texas hailstorm or a fire. When a total loss claim comes in and the rebuild estimate is $80,000 above the Coverage A limit, the shock is real and the financial damage is lasting.
The second mistake is ignoring sublimits entirely. A policyholder with $150,000 in personal property coverage assumes they are well protected. Then a burglary claim comes in for $12,000 in jewelry and electronics, and the policy pays $3,000 because of sublimits they never read. That is not a coverage failure. That is a communication failure between the policyholder and their policy.
My advice is direct: read your declarations page line by line, at least once a year. If a number does not make sense, call your agent and ask. A good independent agent will walk you through every limit, every sublimit, and every exclusion without pressure. That conversation costs nothing. A coverage gap costs everything.
— Ron
Hettler Insurance Agency helps Texas homeowners find the right coverage limits
Choosing the right insurance coverage limits is not a one-size-fits-all decision. It depends on your home’s rebuild cost, the value of your personal property, your liability exposure, and your budget.

Hettler Insurance Agency has served Texas homeowners and renters since 1992. As an independent agency representing over 30 top-rated carriers, Hettler Insurance shops and compares policies to find the right limits at the right price for your specific situation. Ron Hettler and Meghan Hettler are both Certified Insurance Counselors (CIC), the gold standard credential in the industry. They will review your declarations page, identify gaps, and recommend limits that actually protect you. Read about minimum coverage requirements and then call Hettler Insurance to build a policy that goes well beyond the legal floor.
Recommended
About the Author
Ronald J. Hettler, CIC is a Certified Insurance Counselor (CIC) [the gold-standard credential in the independent insurance industry]. Ron has over 46 years of real-world experience in the insurance industry. He is the owner/president of Hettler Insurance Agency in Lubbock, Texas and is licensed by the Texas Department of Insurance (License #666862). (Why Trust Hettler Insurance Agency? It’s a Local independent insurance agency representing multiple carriers. Hettler Insurance Agency has established business roots going back to it’s predecessor in the late 1800’s. Local expertise in Lubbock Texas and West Texas risks. Focused on clarity before a claim occurs.) Ron and his daughter Meghan, also a CIC, lead a team that represents 30+ carriers and serves clients across Texas.
Ron specializes in helping individuals, families, and small business owners understand complex insurance concepts in clear, practical terms so they can make informed decisions about their coverage. He specializes in helping individuals and families understand coverage gaps, deductible structures, and real-world claim outcomes before a loss occurs. Ron helps you to understand how insurance policies respond in real-world claim situations.
License verification available through the Texas Department of Insurance.
Frequently Asked Questions ?
Q1 ?: What is a coverage limit in simple terms?
Q2 ?: What are the main types of coverage limits?
Q3 ?: How do I know if my coverage limits are high enough?
Q4 ?: What happens if my claim exceeds my coverage limit?
Q5 ?: Can I increase my coverage limits after buying a policy?
— Life Insurance Instant Quote and Apply Tool @ GetLifePolicy.com > * Quick self-service term life insurance quote. With or without medical exam.
— Call us about Auto, Home, Business, Life, or Health insurance. * Click to Call (806) 798-7800, Mon-Fri 8:30am-5pm (lunch closed Noon-1pm)
— Come see us @ our new address 4720 S Loop 289 Lubbock, TX 79414 (maps link), or get your online quote started at https://GetHettler.com